Jiangsu Pacific Quartz, a high-purity quartz (HPQ) producer from China, is already supplying its HPQ material to leading domestic and overseas producers of chipmaking tools, including Lam Research and Tokyo Electron. More recently, the company's materials/components have passed certification by a domestic DRAM manufacturer. Analyst TP Huang, who hosts the China Tech Talk podcast, believes that the DRAM maker is CXMT.
While Pacific Quartz's achievements are significant, the company's components are used in semiconductor production equipment after the silicon wafer has been made. Meanwhile, Ingots for semiconductor wafers are grown in crucibles made from high-purity fused quartz, typically over 99.999% SiO₂ (5N+), with much tighter limits on individual critical contaminants. For now, such quartz can only be obtained in significant volumes from Sibelco and The Quartz Corp., which operate in Spruce Pine, North Carolina, and from Russian Quartz LLC, which can produce modest volumes.
Pacific Quartz has supplied Lam Research and Tokyo Electron with ultra-high-purity quartz consumables, such as LPCVD diffusion tubes, wafer boats, quartz ingots, quartz plates, and high-purity quartz tubes, since 2019–2020. Typically, quartz used for process equipment is 4N5 – 5N purity (~99.995–99.999% SiO2). So Pacific Quartz's products are good enough for semiconductor tools.
More recently, Pacific Quartz said its quartz products manufactured from its own high-purity quartz sand passed qualification at a leading Chinese DRAM manufacturer, apparently CXMT, for use in 300-mm wafer production. This is particularly significant because it demonstrates a largely domestic supply chain for Chinese quartz that starts with Pacific Quartz's purified high-purity sand, which is then processed into semiconductor furnace-tube material that goes to a DRAM fab. While CXMT certainly uses equipment from Lam Research and Tokyo Electron, we cannot say for sure that all the quartz consumables that these tools use are made by Pacific Quartz.
Semiconductor furnace tubes are typically made from roughly 5N-class high-purity fused quartz, with stringent limits on electrically active and mobile contaminants, as they can migrate onto/into hot silicon wafers and alter transistor characteristics, ultimately creating defects and lowering yield.
While China-based Pacific Quartz can produce components for semiconductor production equipment, it still cannot produce crucibles good enough to grow silicon wafers with 9N–11N purity. Will it change in the foreseeable future? Only time will tell.
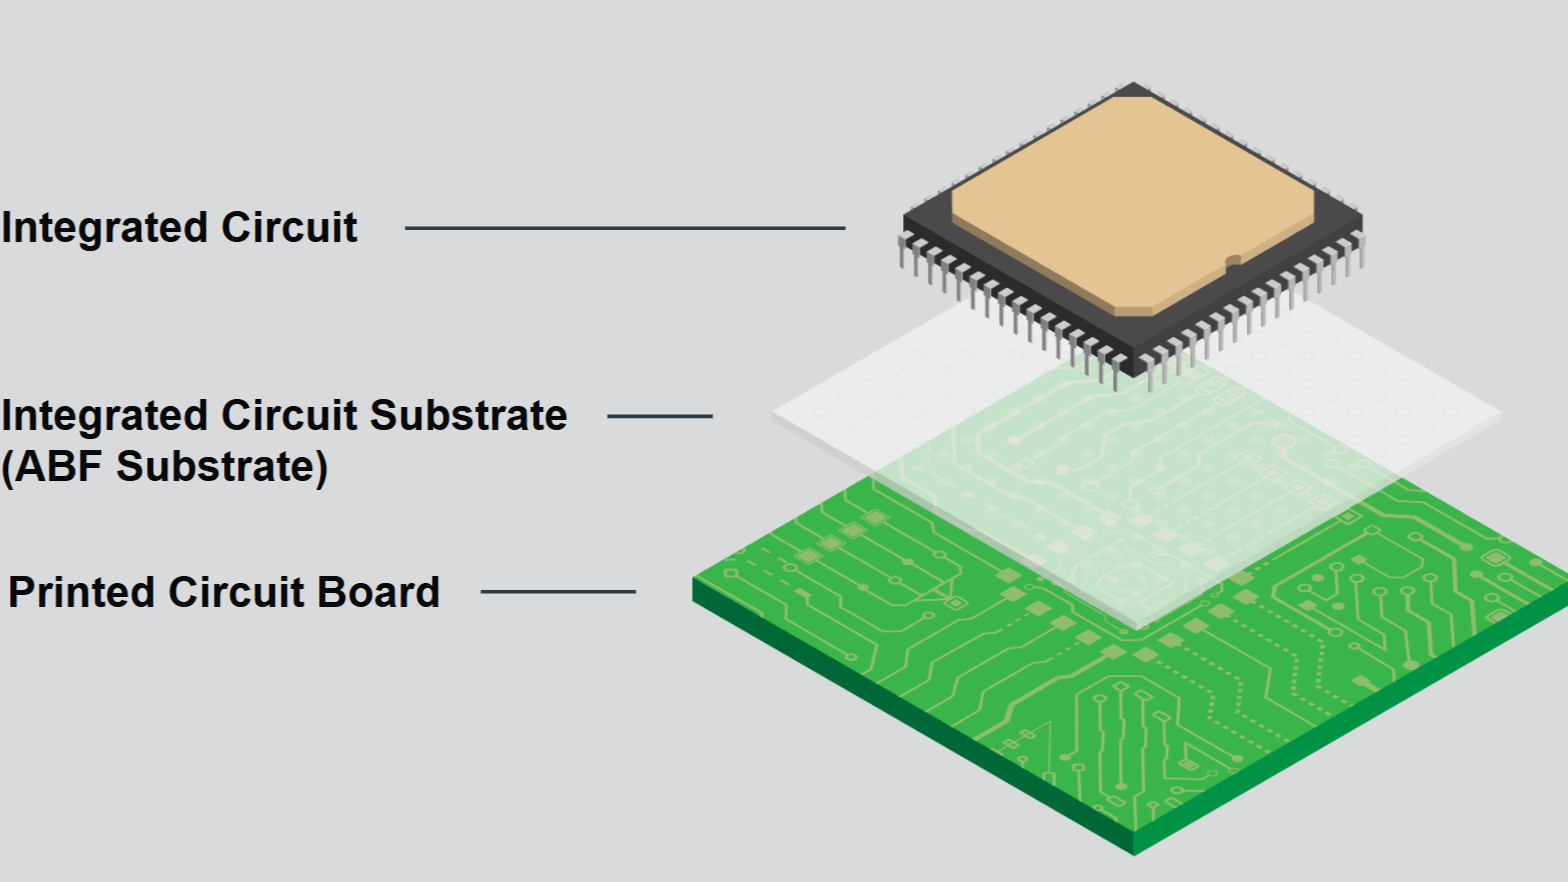
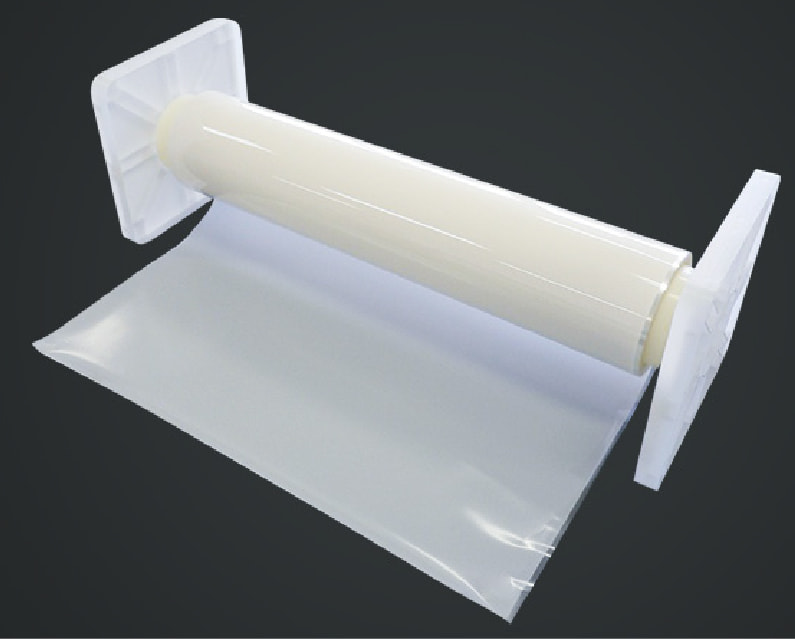
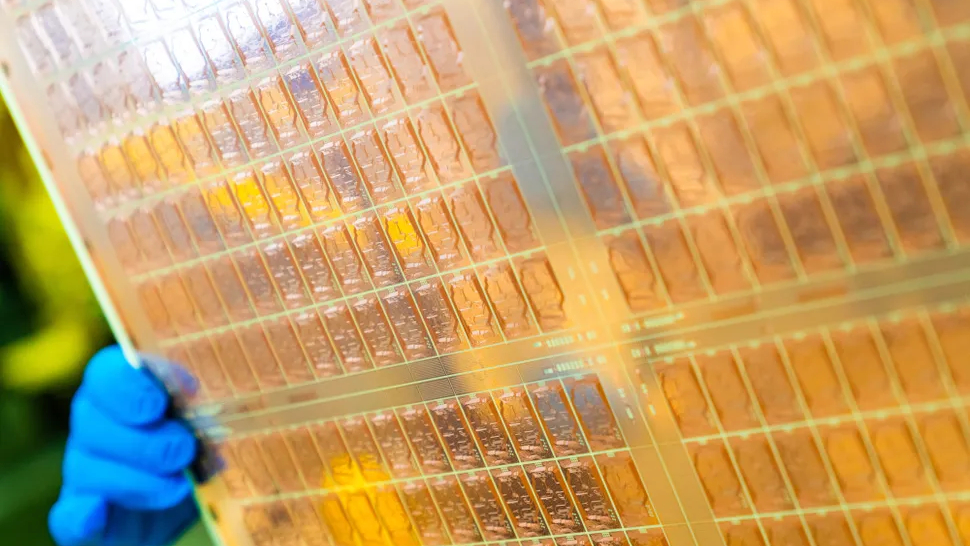
ABF substrates, the specialized insulating and wiring bases that connect tiny silicon chips above them to the much larger printed circuit boards below, sit beneath most high-end CPUs, GPUs, and AI accelerators. Featuring the Ajinomoto build-up film (ABF), these substrates have been critical to the semiconductor industry since the late 1990s, with personal computers, workstations, servers, and networking silicon driving steady demand for decades.
The artificial intelligence boom has multiplied that demand exponentially. Training and inference for frontier models now run across data centers, each housing hundreds of thousands of accelerators and providing hundreds of megawatts of compute. Nvidia alone shipped an estimated 3.2 million Blackwell GPU packages through the end of 2025, with every one of those accelerators packaged on an ABF substrate. Meanwhile, the industry is already entering the gigawatt era with humongous data center buildouts, each expected to house millions of AI accelerators.
This edifice rests on a remarkably narrow supply chain. Practically every advanced logic and AI chip made today by Intel, AMD, and Nvidia depends fundamentally on ABF substrates. These substrates are the conventional default for high-performance packaging. They are made by a small group of specialists, including Unimicron, Ibiden, Kinsus, Shinko Electric Industries, Samsung Electromechanics, and Nan Ya PCB. The upstream supply chain gets much tighter.
The one common denominator across ABF substrates, regardless of manufacturer, is the Ajinomoto build-up film itself. Each substrate maker laminates its build-up layers using dielectric film supplied by Japan's Ajinomoto, which controls a reported 95% or more of the global market. A single company, better known for food seasoning than microelectronics, sits at the base of one of the most concentrated supply chains in computing, almost singlehandedly supplying a material for hundreds of millions of semiconductor devices. Not surprisingly, demand is now growing beyond what the supply chain can comfortably supply.
Compounding this crunch, modern AI accelerators now pack multiple compute, memory, and supporting components onto a single board. As a result, the substrate is getting larger across the X-Y footprint to accommodate the expanding package. Manufacturers are also adding more build-up layers to the substrate to route the growing number of signals and power connections. Each additional layer requires another ABF layer, further multiplying demand across millions of accelerators and extending manufacturing times.
Unfortunately, the complications don't stop there. Beyond further straining the supply chain, expanding the substrates is creating technical problems, such as warpage, yield issues, and electrical losses within the component itself. This leaves the ABF substrate ecosystem facing two related challenges: producing enough advanced substrates for a rapidly expanding fleet of AI accelerators, while simultaneously re-engineering these substrates so they can continue to scale without becoming unmanufacturable or impractical.
The ABF substrate roadmap is consequently as much about supply-chain capacity as it is about the hardware itself, with suppliers such as Ajinomoto and Ibiden outlining plans to expand material and manufacturing capacity, respectively. At the same time, the wider industry — Intel, Samsung, and SK's Absolics among them — is exploring glass-core substrates and other material technologies to push past the limits of organic ABF.
ABF substrates
Silicon dies, including CPUs and GPUs, cannot communicate directly with the printed circuit board beneath them. The connection pads on a die are spaced micrometers apart, while the traces on a motherboard are spaced hundreds of micrometers to millimeters apart. Every high-performance chip, therefore, sits on an intermediary package substrate — a dense, multilayer board that fans the ultra-fine connections on the die outward into connections large enough for the motherboard to handle, while also providing signal routing, power and ground distribution, and mechanical support for the package.
ABF substrates used in AI accelerators typically consist of a rigid, glass-reinforced resin core sandwiched between successive build-up layers of copper wiring and insulating film. The core provides much of the mechanical rigidity, while the layers provide the increasingly dense wiring required close to the silicon.
To create the substrate, the manufacturer laminates the ABF dielectric onto the structure, forms microscopic vias — commonly with a CO2 laser — and then uses lithography and copper deposition to create a new wiring layer. High-end substrates typically use a semi-additive process (SAP), in which fine copper traces are plated up from a thin conductive seed layer. Another ABF layer is then laminated over it, and the process repeats. The film electrically separates successive copper layers, while plated microvias connect them vertically.
ABF substrate (Image credit: Ajinomoto)
Ajinomoto developed the film in the 1990s, after which it gradually became the industry default for its low dielectric loss, fine-line capability, and smooth lamination. The company reportedly accounts for roughly 95% of the substrate film market, with its nearest competitor, Sekisui Chemical, holding only a low-single-digit share.
The manufacturing tier above the film is more populated but still concentrated. Unimicron, Ibiden, and Shinko together account for roughly three-quarters of the substrate market by most estimates, with AT&S and Nan Ya PCB rounding out the leading group. These companies take ABF and other materials and manufacture the finished multilayer substrate. Semiconductor packaging companies, such as TSMC and Amkor, then integrate those substrates into packages containing the processor, memory, and other components.
AI accelerators are pushing substrates outward and upward
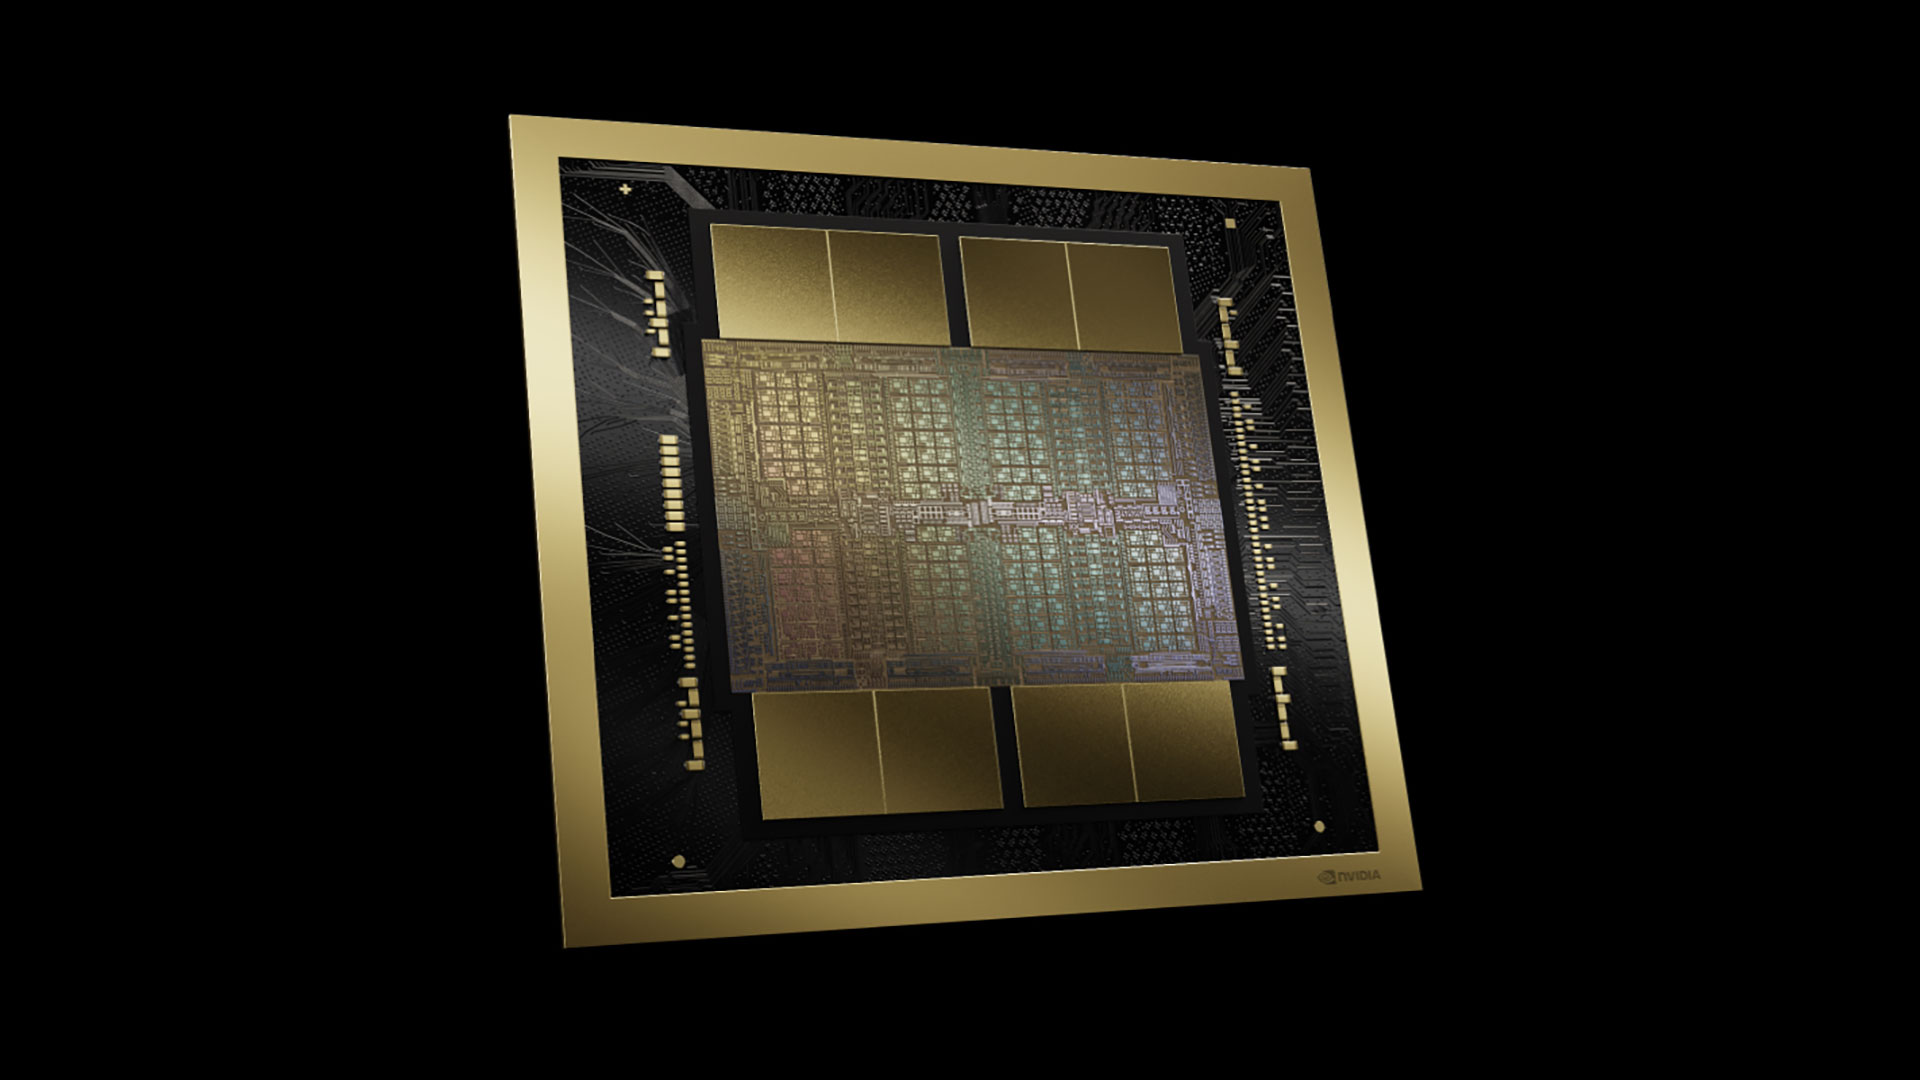
To deliver the compute and memory bandwidth that frontier models demand, the industry is packing ever more silicon onto each AI accelerator. Designers now place multiple large logic dies alongside a growing number of high-bandwidth memory stacks on a single package. Nvidia's Blackwell generation mounts two reticle-sized GPU dies and eight HBM3E stacks on a single package, with its upcoming Rubin and Rubin Ultra parts pushing it further still. TSMC's CoWoS packaging is scaling from around 3.3 reticles — each roughly 830 square millimeters of silicon — a generation ago to 5.5 reticles in volume production in 2026, with a roadmap reaching 9.5 reticles in 2027 and beyond 14 reticles by 2029, when a single package is expected to carry roughly ten compute dies and twenty or more memory stacks.
This expansion of the accelerator package is driving the substrate’s expansion on two physical levels. The first expansion is the substrate's footprint in the X-Y axes. The base has to get wider and longer to accommodate the larger package footprint. Ibiden's current roadmap puts its cutting-edge substrate size at 90 × 90mm (3.54 x 3.54 inches) in 2026, 110 × 110mm (4.33 x 4.33 inches) in 2028, and 130 × 130mm (5.12 x 5.12 inches) and larger from 2030 onward. Ajinomoto independently expects the representative advanced AI packages its film goes into to grow from roughly 100 mm² in 2026 to about 120 mm² for 3D AI packages from 2031.
The second expansion is along the Z axis through additional layers. An expanded collection of compute dies and memory creates more signals to route, while the corresponding increase in power draw requires extensive power and ground distribution, all of which must be carried in a growing number of layers. Ibiden's roadmap targets a 10-X-10 buildup structure in 2026, 12-X-12 in 2028, and 14-X-14 from 2030. Here, the numbers represent the build-up layers on either side of the central substrate core: “10-X-10” means 10 build-up layers per side of the core — which is represented by the “X” — each comprising one dielectric layer (ABF) plus one patterned copper layer, working as a pair.
Nan Ya PCB's roadmap points in the same direction. From an 11+N+11 baseline, it targets 24-layer substrates in 2026 and more than 24 layers in the first half of 2027, while tightening line and space from a 9/12 µm baseline to 8/8 µm and then to 6/7 µm by early 2027. Layer-counting conventions differ between vendors, so a per-side figure and a total layer count don't necessarily line up directly.
Nvidia's Blackwell architecture mounts two reticle-sized GPU dies and eight HBM3E stacks on a single package (Image credit: Nvidia)
The substrate’s expansion in both directions creates several challenges. Increasing the X-Y area makes the package harder to keep flat. Silicon, copper, the substrate core, and the polymer build-up materials that make up the substrate expand by different amounts when heated. As the package is bonded during assembly at around 250⁰C and then cooled, these mismatches cause the layers to pull against one another, leading to warping — a problem that becomes harder to control as package dimensions increase.
Excessive warpage can undermine solder-joint formation, layer-to-layer alignment, and reliability, while a larger substrate also occupies more manufacturing-panel area and exposes more area to potential defects. Organic substrates are reported to lose usable flatness once packages exceed roughly 120mm per side, a threshold that the largest AI accelerators are now reaching and that Ibiden's own roadmap — climbing toward 130mm and beyond — is set to cross.
The growing layer count along the z-axis also creates manufacturing challenges around yield, capacity, and time. Every new substrate layer requires a full manufacturing sequence of several steps, all held to sub-ten-micron tolerances. Each added layer increases the chance of a defect or alignment error that can scrap the whole substrate.
Additionally, layer count consumes manufacturing capacity and time in proportion. This is why Ibiden frames future demand in terms of semi-additive processing load rather than a simple substrate count, as a single advanced substrate now consumes far more of a line's capacity than a finished-unit tally would suggest.
Overall, the simultaneous expansion in substrate area and layer count means ABF consumption is rising much faster than processor shipments alone suggest. Ajinomoto illustrated this in its 2025 integrated report with a larger AI substrate that had about 3.5 times the board area and three times as many ABF layers as a conventional design — 18 layers against six — consuming roughly ten times as much ABF overall. This surging material consumption, set against an extremely concentrated supply base, extends the ABF substrate story beyond a technical problem into a supply-chain constraint.
The supply chain constraint
Like many components in the semiconductor industry chain before the AI boom, demand for ABF substrates periodically swung both ways. A severe bottleneck through 2020-2022 — driven by pandemic-era PC and server demand — was followed by an oversupply in 2023, as substrate manufacturers expanded capacity. However, that capacity was built for low-layer-count, smaller consumer substrates, not the large-body, multi-layer packages AI demands.
These advanced products require sufficiently large manufacturing formats, fine SAP wiring, tight layer registration, acceptable warpage, and high yields across much larger structures. Ibiden captures this by measuring demand not in finished substrates but in semi-additive-process load — the actual processing work each part imposes on a line. Indexing 2024 at 1.0, it expects the SAP load of a single AI-server substrate to reach 1.8 times that in 2026 and 2.5 times in 2028, with the company stating that substrate expansion will push total SAP demand beyond industry supply capacity, indicating a constraint in the manufacturing process itself.
The bottleneck is even tighter at the ABF material level. Ajinomoto's film capacity was already running at full load in the second quarter of 2026, at a reported two million square meters per month, although the company has outlined plans to increase capacity. A near-monopoly supplier at full capacity while consumption surges paints a clear picture of the bottleneck’s severity.
Unsurprisingly, prices have moved accordingly. Ajinomoto notified substrate manufacturers in May 2026 that it would raise ABF film prices by approximately 30%, effective in the third quarter. The hike is coming alongside comparable increases in copper-clad laminates from Resonac and Mitsubishi Gas Chemical, compounding pressure across the whole stack. Further tightening the squeeze, Ajinomoto recently cut shipments of the critical ABF film to China by 30%.
Ajinomoto Build-up film (Image credit: Ajinomoto)
The growing ABF substrate problem cannot simply be attributed to Ajinomoto running out of film. In fact, while it's running at full capacity, the company says it has no concerns about its overall supply chain. The constraint stretches across the entire chain containing ABF, glass cloth, and other materials, SAP equipment, large-format substrate factories, yield, and customer-qualified production capacity.
The immense industry demand is progressively tightening the crunch. Several supply-chain analyses converge on an ABF supply-demand shortfall of roughly 10% in the second half of 2026, widening to around 21% in 2027 and potentially exceeding 40% by 2028, with demand for substrate area projected to grow at a compound annual rate near 39% from 2025 to 2028 as accelerators integrate more components.
The roadmap to recovery: more capacity, better materials
The industry is responding to ABF substrates' multifaceted constraints on multiple fronts: expanding manufacturing capacity to relieve near-term supply pressure while qualifying new materials and substrate architectures to break through the technical limits. Capacity expansion is already underway across the supply chain.
Ibiden is executing ¥500 billion ($3.1 billion) in capital investment across fiscal years 2026 to 2028 — the largest single substrate expansion on record — targeting 2.8 times its 2024 capacity for ASIC and AI-server substrates by 2028. Unimicron raised its 2026 capital spending to a record NT$34 billion ($1.07 billion), with a focus on ABF substrates. Meanwhile, Samsung Electro-Mechanics, Samsung's substrate arm, has committed $1.2 billion to expand ABF substrate production, with volume production expected by the third quarter of 2027.
Pegatron's substrate unit, Kinsus, has approved NT$23.5 billion ($722 million) for ABF equipment over three years and now focuses its most advanced lines almost entirely on AI clients, aiming to lift monthly output at its Taoyuan plant by roughly 25% by 2027. While these projects address the shortage directly, their lead times mean the crunch may continue for a while, as supply cannot respond instantly to the AI demand spike.
Ajinomoto is expanding upstream as well. A new plant in Gunma entered full operation in 2025. The company has invested roughly ¥25 billion ($157 million) in ABF production since 2023 and has said it will invest at least as much again by 2030, targeting a capacity increase of more than 50%. It is also adding a third Japanese base for varnish production — envisioned to provide capacity comparable to Gunma — with construction planned for 2028 and operations to begin in 2032.
However, capacity only solves the problem if the current substrate architecture can continue to scale. The material roadmap — aimed at addressing the physical constraints of ABF substrates — is therefore advancing parallel to the factory roadmap. Ajinomoto says present and future ABF generations are being engineered for larger, more multilayered substrates, high-bandwidth I/O, lower transmission loss, and improved resistance to warpage and humidity. The company expects newer, higher-value ABF grades to take an increasing share of its portfolio through 2030.
Substrate makers are addressing the problem from the process side. Nan Ya plans to move beyond 150 mm body sizes and 24 layers while shrinking copper line/space geometry toward 6/7 microns in the first half of 2027. Its materials roadmap includes an ultra-low-CTE core material with a CTE below 3 ppm/°C, alongside low-Dk, low-Df, and low-CTE dielectrics. Finer wiring allows a substrate to support more connections without relying solely on additional area or layers, while low-expansion materials help keep the growing structure flat.
Eventually, the substrate's central core itself may change to glass. Organic substrate cores are increasingly difficult to keep dimensionally stable as packages approach and surpass 100 mm. Glass can be matched more closely to silicon's thermal expansion — providing dimensional stability — and offers substantially lower dielectric loss for high-speed links. It has therefore emerged as one of the industry's main solutions to warpage.
(Image credit: Intel)
As we detailed in our glass substrate roadmap, the move to a glass core is drawing a broad field, as it sits at the intersection of substrate-making, glass manufacturing, and advanced packaging, pulling in chip-and-packaging houses, display and glass specialists, and the incumbent substrate makers alike. Intel demonstrated a package that combines EMIB with a glass substrate at NEPCON Japan in January 2026, although the company still places commercial glass-substrate deployment in the latter half of the decade.
SK Group subsidiary Absolics is operating a low-volume glass-substrate manufacturing facility in Covington, Georgia — backed by $100 million in US CHIPS Act funding — producing prototype and qualification samples for customers, such as AMD for its MI400-series accelerators, while Samsung Electro-Mechanics is producing prototypes on a pilot line in Sejong and now plans mass production through its glass-core joint venture after 2027.
TSMC, meanwhile, is pursuing panel-level packaging through its chip-on-panel-on-substrate (CoPoS) platform, moving to a 310 x 310mm panel format, with a pilot line at its VisEra subsidiary, trial production targeted for 2027 and mass production for the second half of 2028. Glass-core substrates are a separate, later step on TSMC's roadmap, with commercial scale projected after 2030. Ibiden also puts “glass core” on its substrate technology roadmap around 2030 as a solution for warpage control.
The glass core — most likely a late-2020s-to-2030s technology — is positioned as a solution to the warpage wall. It replaces the organic core, not the ABF itself, which would remain the buildup material. A glass core may soften ABF demand per package, as glass's flatness allows finer routing and potentially fewer buildup layers, but it does not remove the material or the dependency. There's the possibility that a future dielectric material will eventually replace ABF, although that doesn't seem to be the industry's main focus currently.
Regardless, the near-term roadmap centers on more advanced SAP capacity, rapidly expanding factories, improved materials, and increased supply. Through the late 2020s, finer wiring, lower-loss ABF, lower-CTE materials, and better warpage control will enable organic substrates to stretch toward 110 mm and beyond. Around 2030, glass cores offer a path toward the 130 mm-plus packages that Ibiden and others already have on their roadmaps.
ASML, Intel, Samsung, and TSMC are teaming up to drive the industry transition to 6×12-inch photomasks (reticles). This shift is paramount for High-NA EUV lithography, as the larger stencil would enable printing large chips in a single pass, instead of having to stitch smaller designs together, as ASML explained in a press release this week.
This kind of collaboration between chipmakers isn't entirely unheard of, but it is rare. But when they face an industry-wide challenge, they set aside their rivalry and join forces to move the industry forward. This happened several times in recent decades, first with the failed transition to 450-mm wafers co-funded by GlobalFoundries, IBM, Intel, Samsung, TSMC, and New York State, then with the EUV transition, which was spearheaded by Intel, TSMC, and Samsung.
Higher resolution comes with a nuance
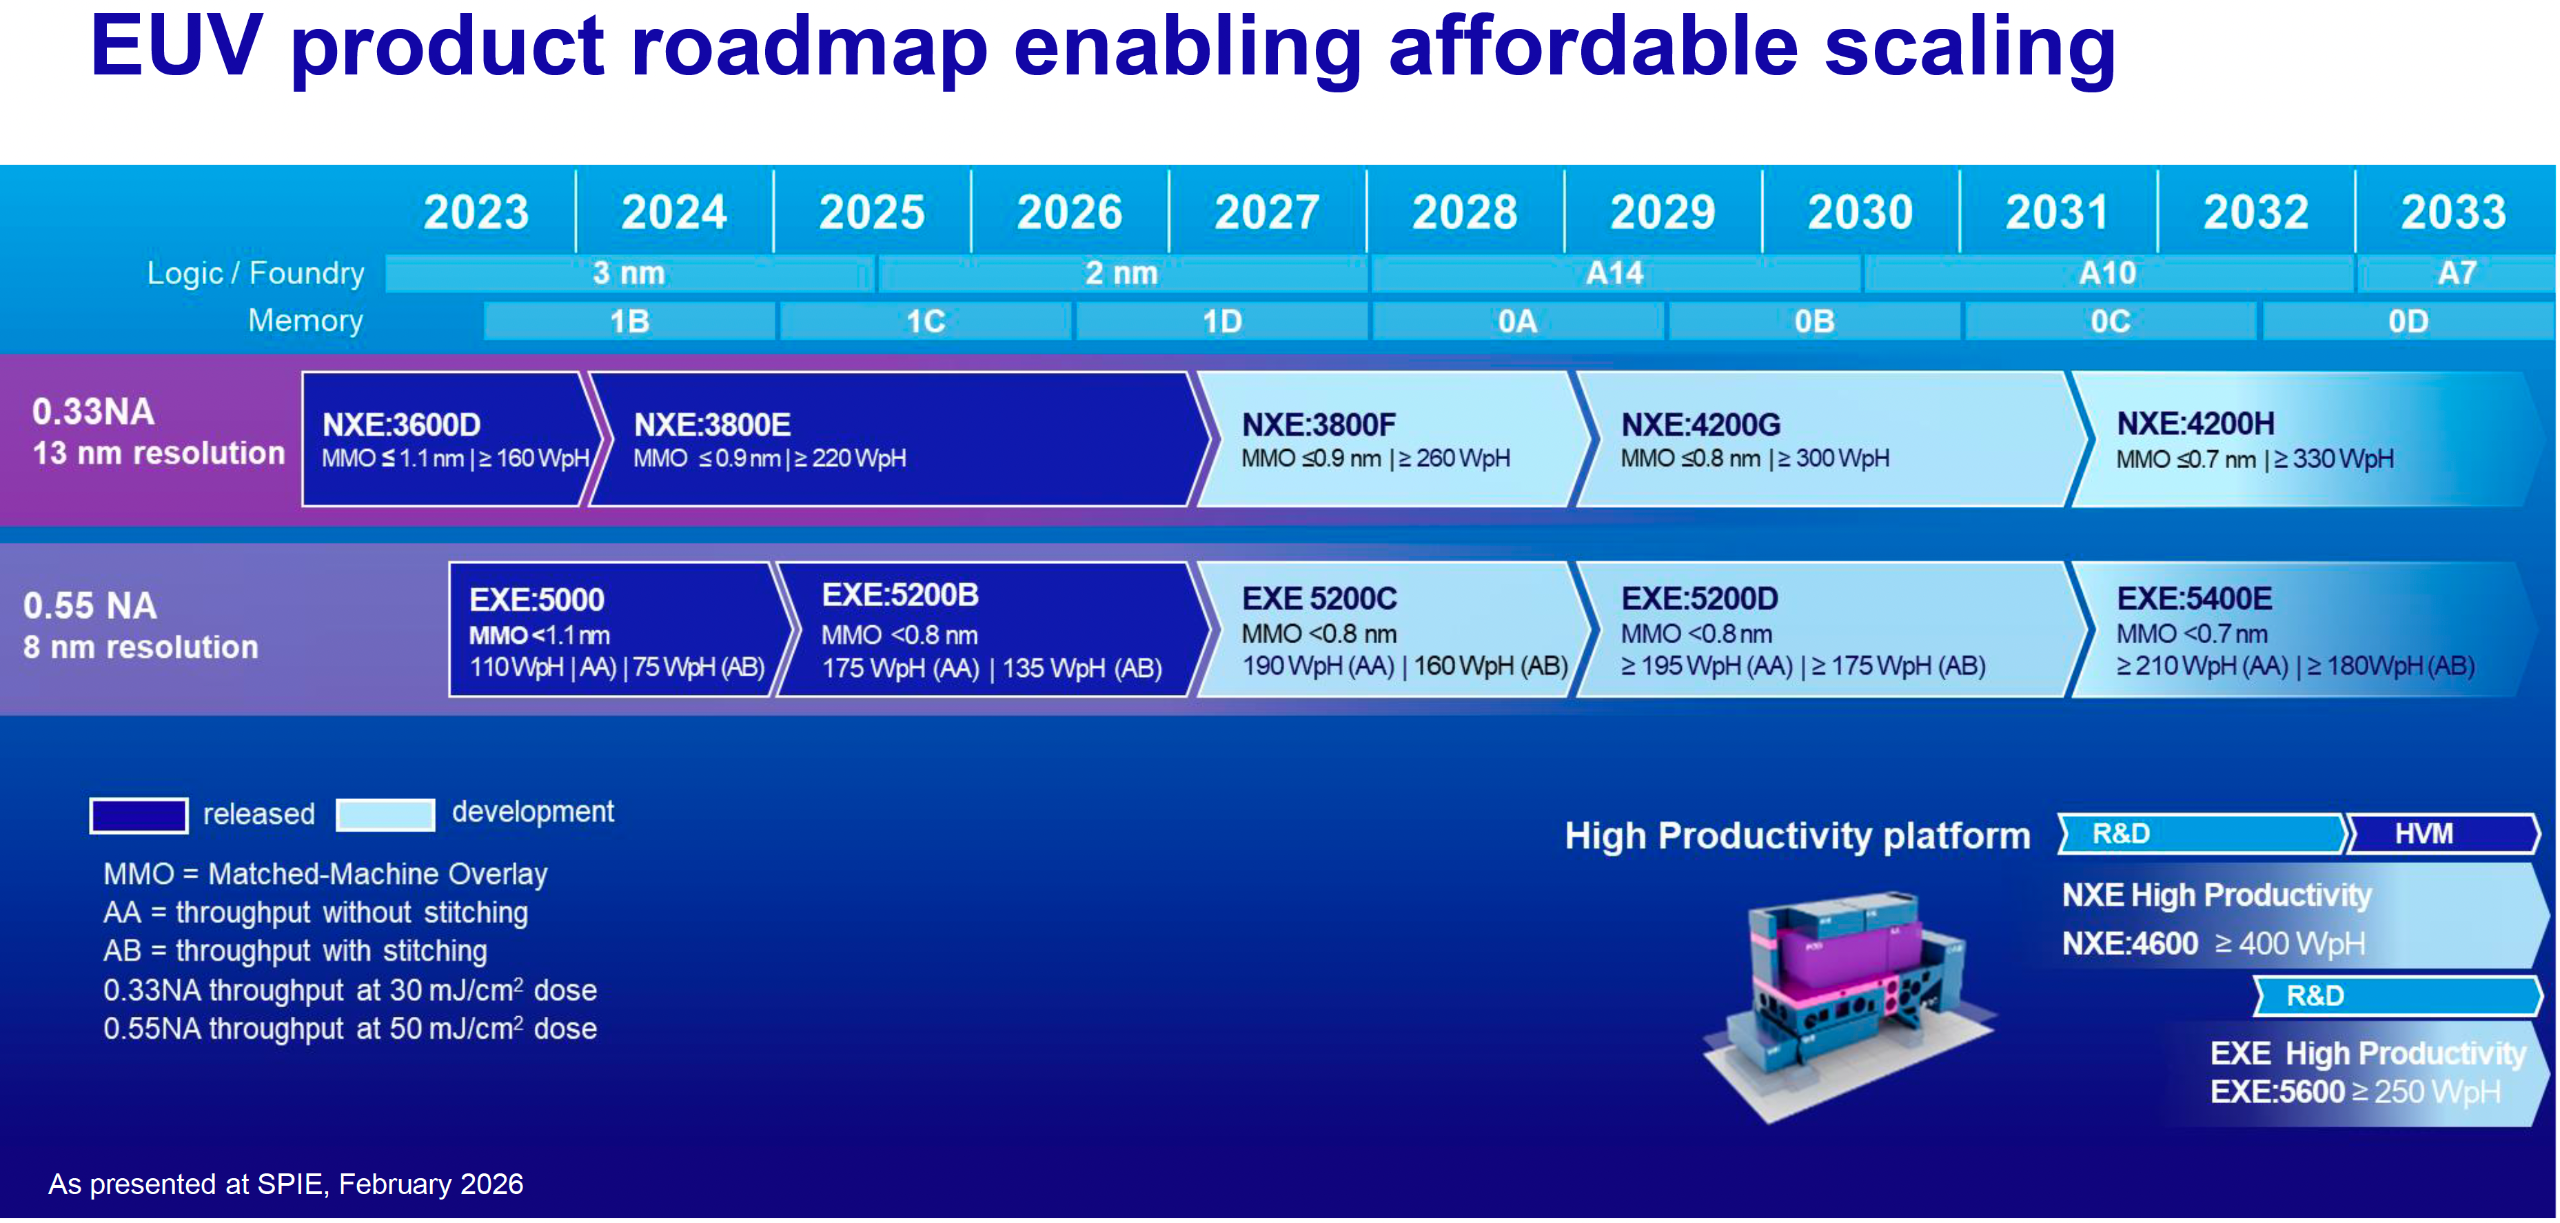
High-NA EUV lithography is a major step forward from today's Low-NA EUV tools. With a numerical aperture of 0.55, High-NA systems can achieve an 8nm single-exposure resolution, compared with 13nm for 0.33-NA EUV scanners. The higher resolution enables chipmakers to pattern smaller, denser features in a single exposure, replacing complex Low-NA EUV multipatterning schemes with a single High-NA exposure. This can reduce the number of masks and process steps, shorten manufacturing cycle times, and potentially improve pattern fidelity and yields, especially on critical layers of next-generation process technologies.
However, this improvement comes with a significant tradeoff. Conventional 0.33-NA EUV uses 4X reduction optics in both directions, which enables a 26×33 mm exposure field with standard 6×6-inch photomasks. By contrast, High-NA EUV uses 4X/8X anamorphic optics, so the same mask can only expose a 26×16.5 mm half-field, which is hardly a problem for client-oriented designs that are barely larger than 429 mm². However, large dies that fit within a conventional 26×33 mm EUV field must now be patterned using two High-NA exposures stitched together, or split into a multi-chiplet design.
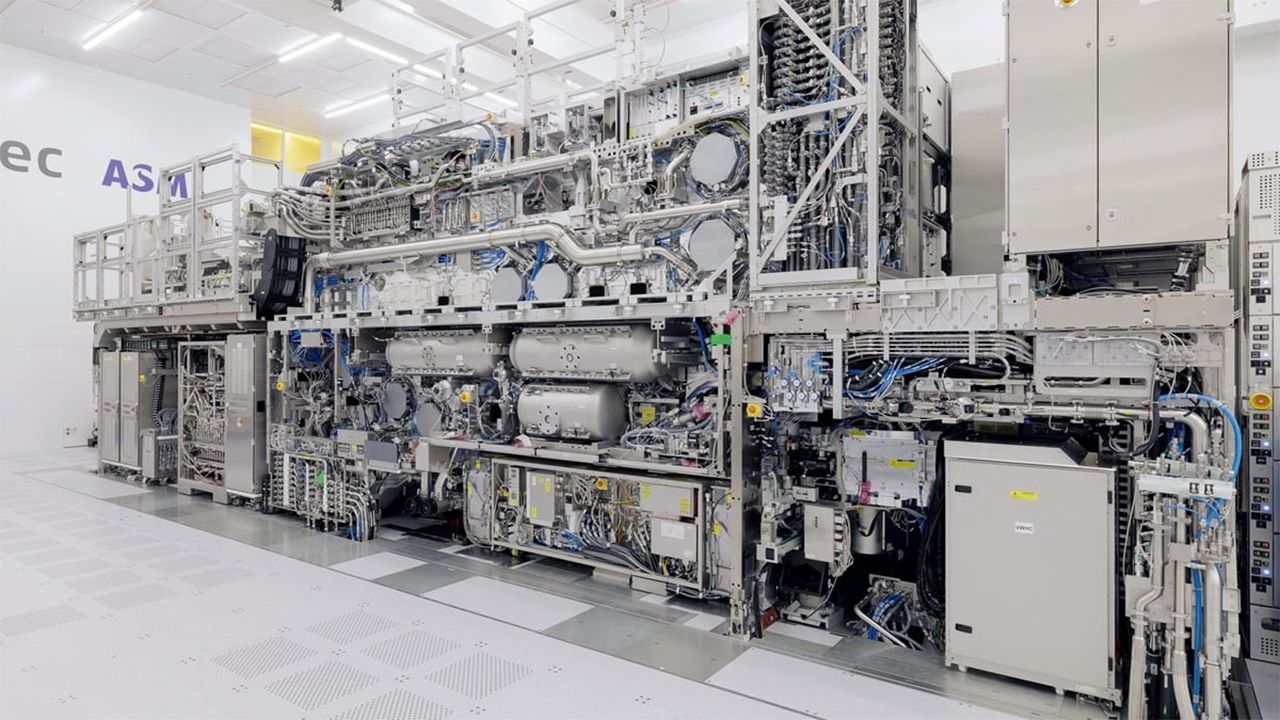
Stitching is a workable near-term solution that all chipmakers, including Intel, Samsung, and TSMC, use, but it comes with multiple drawbacks. First, it reduces the throughput of ASML's Twinscan EXE:5200B scanner from up to 175 wafers per hour for half-field exposures to around 125 wafers per hour when stitching is used. Secondly, chip designers must account for the stitching boundary, which means additional design rules and reduced floor planning freedom.
Finally, the two exposures must be aligned with extreme precision so that features crossing the boundary connect properly. Even tiny alignment errors can distort lines and vias, or compromise interconnects and thus potentially create defects and lower yields. Such yield loss is very expensive in the context of large CPUs and GPUs produced using Low-NA EUV systems. If yield is lost on more expensive High-NA EUV tools, the costs will be even higher, which greatly lowers the appeal of using these scanners.
New photomasks are needed
A Lego version of an ASML Lithography machine. (Image credit: ASML)
To eliminate the need for stitching, the industry is exploring larger orthogonal 6×12-inch photomasks to compensate for anamorphic optics. By doubling the reticle dimension corresponding to High-NA's 8X reduction direction, these masks are set to restore the traditional 26×33 mm full exposure field and enable even reticle-sized dies to be patterned without stitching.
However, 6×6-inch photomasks have been an industry standard for around three decades since the 1990s. Even the transition from DUV to EUV did not change the basic mask dimensions: EUV replaced transmissive masks with reflective multilayer masks but retained the 6×6-inch substrate form factor. As a result, the adoption of 6×12-inch reticles would require the industry to change the entire mask-making, mask handling, and lithography infrastructure built around the existing format.
Mask-blank suppliers like AGC and Hoya would need new or modified equipment to produce larger substrates and deposit uniform reflective EUV multilayers across a much larger area. Mask shops would need new or modified writers and etch tools to pattern the larger masks, as well as inspection and metrology systems capable of precise characterization of the new format. Cleaning equipment, pellicles, and pellicle-mounting devices would also require modifications.
The mask handling infrastructure would have to change as well. Suppliers would need larger mask pods, while fabs and mask shops would require compatible storage, transport, and automated handling systems. At the same time, they would have to retain support for existing 6×6-inch masks since existing and future Low-NA EUV and DUV scanners will continue to use the established format.
Perhaps the biggest changes would be required from ASML. Its High-NA EUV scanners would need modifications or a redesign to accept, clamp, move, and position the substantially larger reticles with the extreme precision required for EUV lithography.
Intel, Micron, Samsung, SK hynix, TSMC, and other chipmakers planning to adopt High-NA EUV lithography would then have to qualify the new masks, scanners, and other tools for their process flows and ensure that the full-field exposure capability works as intended.
As a result, the adoption of 6×12-inch masks would require a coordinated effort and significant investments from chipmakers, ASML, mask makers, and numerous equipment and materials suppliers.
To make matters more complicated, 6×12-inch masks will not replace the existing 6×6-inch format altogether, as noted above. The industry would therefore have to manufacture, inspect, transport, store, and handle two mask formats in parallel, which will add cost and complexity to an already expensive transition.
Timeline
The transition to 6×12-inch reticles is an industry effort currently supported by ASML, Intel, Samsung, and TSMC. It is going to take years and will happen well after High-NA EUV enters high-volume manufacturing with today's 6×6-inch photomasks, as the semiconductor industry prefers to adopt new technologies gradually.
Intel already uses High-NA EUV scanner(s) for select Intel 18A layers (patterned at Fab D1X) and supports both floorplanning within the half-field and stitching; Samsung plans to introduce High-NA EUV into DRAM high-volume manufacturing by 2028, and TSMC intends to deploy the technology for advanced-node production starting in 2030. All three companies plan to start High-NA EUV adoption with 6×6-inch masks.
Intel seems to be leading the pack with 6×12-inch reticles as it has been working for three years to make them a reality, but the company remains tight-lipped about the timing of its adoption of the new photomasks. Meanwhile, the ASML-TSMC initiative targets a 6×12-inch photomask pilot line by 2031, which should provide the foundry with a platform to develop and qualify the new mask format and associated manufacturing infrastructure. The ultimate target is full lithography-system readiness for advanced-node production by 2033.
That said, 6×6-inch and 6×12-inch photomasks for High-NA EUV patterning will likely co-exist on the market at least for some time rather than undergo an abrupt transition. At the end of the day, square 6×6-inch reticles that enable High-NA EUV scanners to expose fields as large as 26×16.5 mm (or 429 mm²) should be sufficient for the vast majority of client processors produced in the coming years. Larger 6×12-inch masks will matter primarily for much bigger designs, such as high-end AI accelerators, data center CPUs, DPUs, high-end GPUs, and FPGAs, where the ability to expose a full 26×33 mm field without stitching becomes considerably more valuable.
No company in the United States has ever restarted a reactor that was seemingly closed for good, but there are now three major efforts underway to do so.
No company in the United States has ever restarted a reactor that was seemingly closed for good, but there are now three major efforts underway to do so.
Leading chipmakers Samsung Electronics and Taiwan Semiconductor Manufacturing Co. announced plans to adopt ASML’s latest chipmaking machines in the next several years—and they also joined Intel in agreeing to a crucial technology change that could boost chip production on the new machines by 40 percent.
This signifies the semiconductor industry’s broader embrace of high NA EUV photolithography technology that can cost up to $400 million per machine and is only provided by the Dutch technology company ASML, Bloomberg reports. The technology would allow chip designers to implement even smaller features in potentially more powerful and efficient next-generation chips produced for AI data centers and consumer electronics such as smartphones, tablets, and laptops.
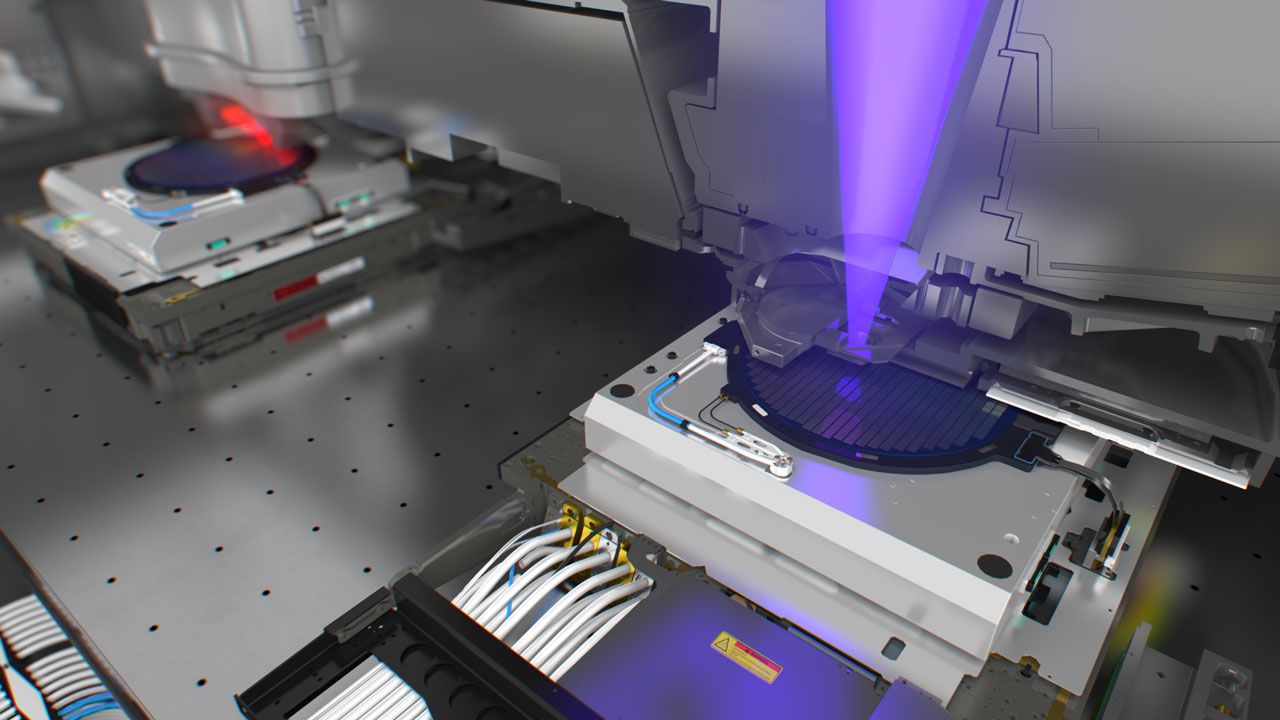
ASML’s EUV (extreme ultraviolet) lithography machines enable chipmakers to use powerful laser light to imprint patterns in silicon wafers, layer by layer, and gradually form the computer circuitry that makes silicon chips work. Compared to older deep ultraviolet lithography, EUV technology harnesses a more powerful source of light with a shorter wavelength to create even smaller features on silicon wafers.
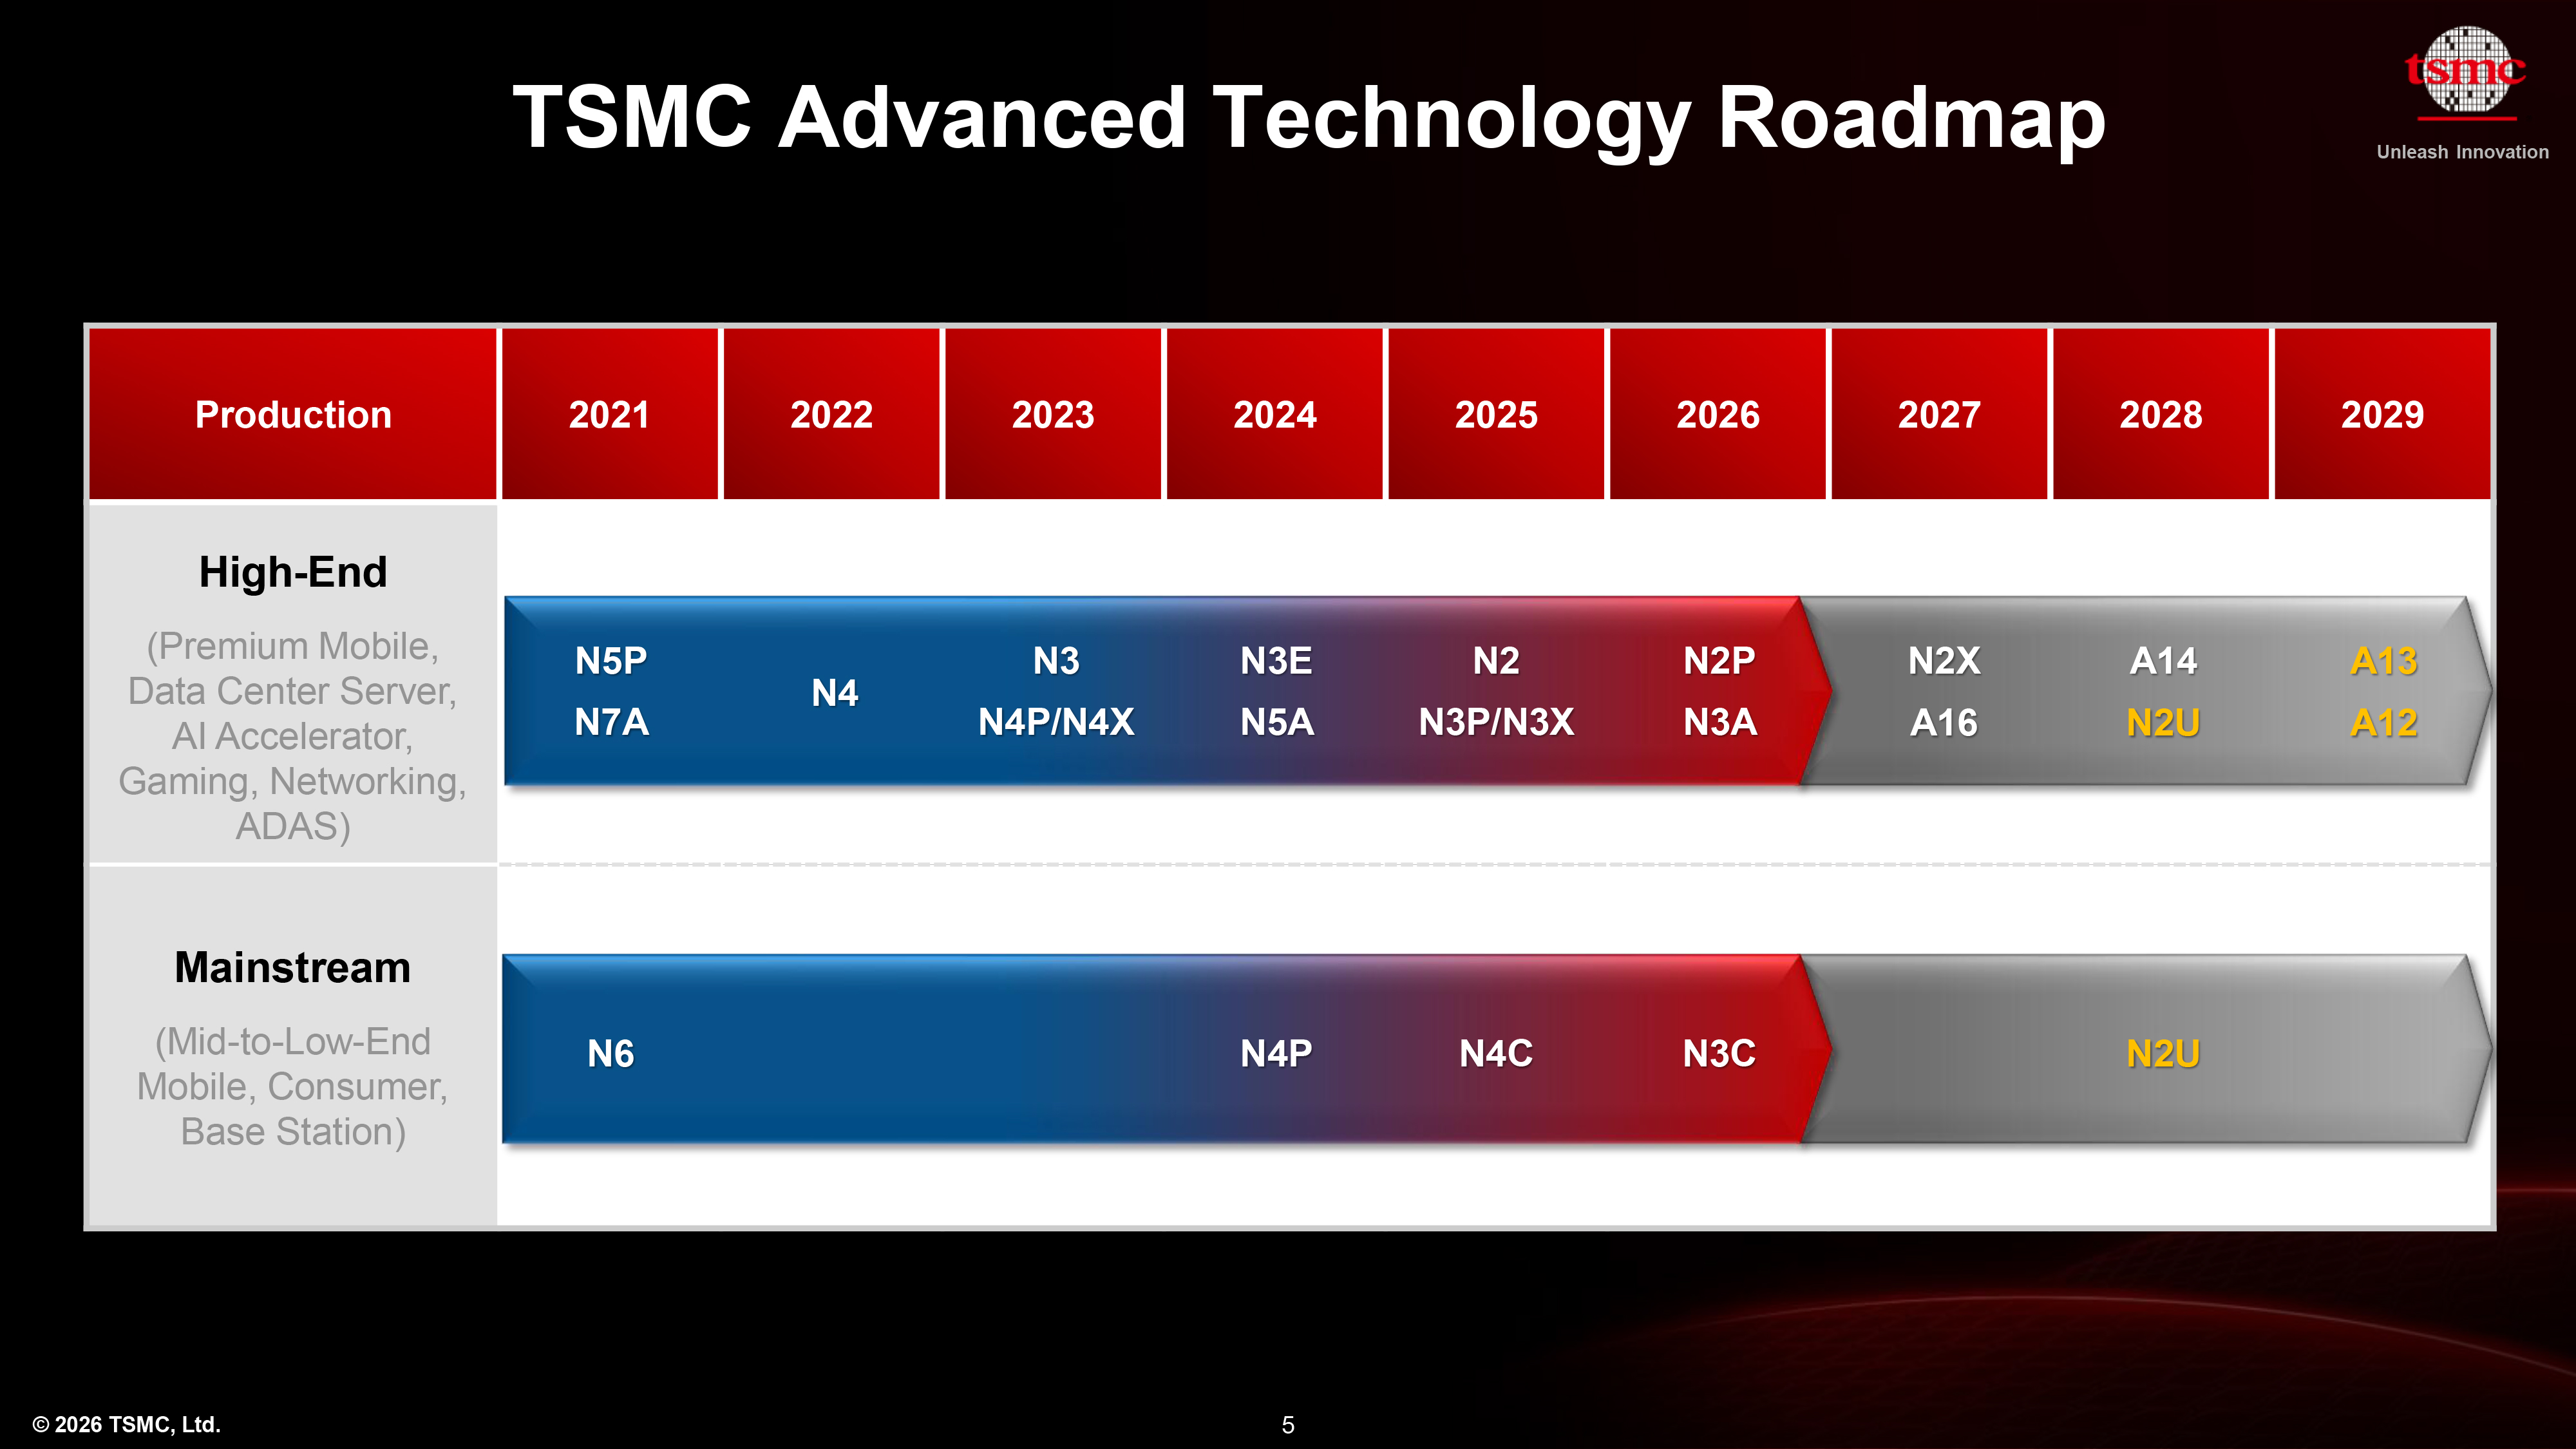
For years, TSMC has tried to avoid making public comments about its plans to use EUV lithography with a 0.55 numerical aperture optics, or High-NA EUV, because the company's developers had a good idea how to keep advancing process technologies without using $400 million scanners. However, TSMC cannot rely on Low-NA EUV systems forever, so this week the company announced plans to use High-NA EUV starting from 2030.
TSMC did not formally reveal which fabrication technology will be the first to adopt High-NA EUV, though the year 2030 points to a few candidates. What TSMC did say is that it expects the number of layers processed using High-NA EUV to eventually increase as its fabrication technologies become more complex, driven by increasing complexity of transistor architectures, which is probably an implication for more sophisticated implementations of gate-all-around (GAA) transistors as well as complementary field-effect transistors (CFETs) later on.
TSMC plans to start using High-NA EUV lithography tools for high-volume manufacturing in 2030 using conventional 6×6-inch photomasks. The company then plans to build a pilot line that uses 6×12-inch photomasks in 2031 with the goal of bringing 6×12-inch High-NA lithography systems into advanced node production by 2033.
High-NA EUV lithography tools can achieve an 8nm single-exposure resolution, as opposed to a 13nm single-exposure resolution offered by today's Low-NA EUV litho systems. However, when used with conventional 6×6-inch photomasks, High-NA EUV scanners have only half the exposure field of their Low-NA counterparts, which creates challenges for manufacturing very large dies. As a result, chipmakers building massive AI accelerators must either stitch multiple exposure fields together or adopt multi-chiplet designs, two approaches that have their own other challenges, such as tool productivity and power consumption. To circumvent the 6×6-inch photomask limitations, TSMC is working with ASML to set the stage for 6×12-inch photomasks.
Changing the size of photomasks is not a trivial endeavor as it requires changing everything from EDA software to tools that produce and write masks as well as systems that handle them, which essentially means that the entire industry must work on this change. ASML seems to be optimistic about the transition as it is supported not only by Intel and TSMC, but also by Samsung.
"We expect the adoption of High NA EUV to increase progressively along the device scaling roadmap, first using current 6-inch masks and then further supported by 12-inch masks, which enable greater scanner productivity and allow the industry to meet the demand for smaller, faster and more energy-efficient chips," said Christophe Fouquet, president & CEO, ASML. "We are pleased by the strong initial support of semiconductor manufacturers, mask suppliers and partners for this initiative."
(Image credit: TSMC)
Perhaps the biggest intrigue about TSMC's usage of High-NA EUV lithography is which process technology will be the first to use the new systems. Based on what we know about TSMC's roadmap, A10 or A11 (1/1.1nm-class) seems to be by far the strongest candidates to use High-NA EUV scanners for the most critical layers. TSMC's latest strategy separates its roadmap into annual client-oriented nodes (N2, N2P, N2X, A14, A13) and roughly biennial high-performance nodes (A16 in 2027, then A12 in 2029). The company has already confirmed that A12 and A13, due in 2029, will continue to rely on conventional EUV lithography.
Since A13 is an optical shrink of A14 that increases transistor density by only 6%, with performance and power improvements yet to be disclosed, its successor in 2030 will likely have to deliver considerably more substantial gains. It is therefore reasonable to expect A13’s successor — whether it is called A11 or A10 — to adopt more advanced lithography and/or TSMC's 3rd Generation nanosheet GAA transistors to deliver significantly higher transistor density as well as meaningful performance and power improvements over its predecessor. Yet, we are of course speculating.
A 52-year-old Belgian-Chinese man has been arrested on suspicion of espionage for allegedly transferring specialized semiconductor intellectual property and trade secrets from Belgian chipmaker BelGaN, where he worked, to China. According to an AP News report citing details released by Belgium's federal prosecutor’s office on September 7, the Beijing-born Belgian resident was taken into custody on May 10 at a Brussels airport while attempting to board a flight to China.
The suspect — identified by Belgian media only as H.L. — previously held a senior research position at the now-defunct BelGaN, which specialized in gallium nitride (GaN) semiconductors. Investigators suspect he was concurrently leading a Chinese chip firm, GanKool, which was developing the exact same specialized gallium nitride chip technology as BelGaN. The company was established only a few months after H.L. joined BelGaN and was financed by a Chinese investment fund. The suspect now faces charges of industrial espionage, membership in a criminal organization, misuse of company assets, and unlawful disclosure of business secrets.
The espionage allegations emerged from an investigation into BelGaN's collapse. When the company collapsed into bankruptcy in the summer of 2024, Belgian authorities launched a routine financial probe into the failure. Investigators eventually uncovered highly unusual corporate activity. Instead of trying to keep BelGaN financially viable, the managers and the researcher may have actively tried to make the Belgian company “disappear” after transferring its proprietary knowledge. This led to further investigations that revealed GanKool’s existence and its connections to BelGaN.
In addition to the researcher’s role, the investigators also found evidence linking BelGaN's last CEO, a Chinese national, to the same Chinese rival. The prosecutors have said a second suspect remains at large, with Belgian media speculating that the CEO is the suspect.
The incident highlights the increasingly intense competition over technology and intellectual property in the semiconductor industry, particularly as China pushes to reduce its reliance on foreign chip technology while the U.S. continues to restrict its access to advanced processors and semiconductor manufacturing equipment. Just last month, South Korean court documents accused Chinese memory maker CXMT of using a detailed “Project Hefei” roadmap to obtain Samsung's proprietary DRAM technology, including a 620-step process recipe. A former Samsung engineer has already been sentenced to seven years in prison over the scheme.
Intel announced on Monday that it had processed more than one million 300-mm wafers using its High-NA EUV scanners, less than two and a half years after its first tool was assembled. For now, the company intends to use industry-standard 6-inch photomasks, which can expose 26×16.5 mm half-fields and therefore require field stitching for larger chips. However, Intel is also working on larger 6×12-inch photomasks that would enable High-NA EUV scanners to expose full 26×33 mm fields without stitching.
One million High-NA wafers
Intel's one million wafers figure includes wafers processed during tool installation and certification, R&D, and production. Earlier this year, Intel certified using High-NA EUV scanners for its 18A process technology, so right now these tools are used to make some of Intel's Panther Lake processors. Intel currently has two ASML Twinscan EXE:5000 tools and at least one EXE:5200B scanner. As of late February 2025, Intel processes around 30,000 wafers using its High-NA EUV tool, so going from 30,000 wafers by February 2025 to over a million by September 2026 is an enormous increase in cumulative High-NA utilization.
Since Intel's fleet expanded from two EXE:5000 systems to three and now includes the much faster EXE:5200B, the million-wafer milestone is really a fleet and process-maturity milestone that Intel has achieved first in the industry. What makes the company's milestone even more important is that ASML announced this April that all of the High-NA EUV scanners shipped by then processed over 500,000 wafers which achieving over 80% availability, which means that Intel has now processed more wafers using High-NA tools than the rest of the industry combined.
Sticking to stitching
Conventional 0.33-NA EUV has 4X magnification in both directions, enabling the familiar 26×33 mm exposure field with traditional 6-inch photomasks. However, 0.55-NA EUV uses anamorphic 4X/8X magnification, so the same 6×6 mask can provide only approximately 26×16.5 mm on the wafer. As a result, large dies that fit within a conventional 26 × 33 mm EUV field must be exposed as two half-fields using High-NA EUV, which is called stitching. While stitching is a workable near-term solution, it has several drawbacks.
(Image credit: ASML)
Firstly, it greatly reduces throughput from 175 wafers per hour to 125 wafers per hour on an EXE:5200B. Secondly, chip designs must account for stitching and must be developed with stitching in mind, which means less floor planning freedom. Thirdly, the two exposures must be aligned extremely precisely so that features crossing the stitching boundary connect properly. Even a tiny misalignment can distort lines and vias, or break interconnects, which potentially creates defects and reduces yields, which will be a particularly costly problem for large CPU and GPU dies.
6×12 mask effort progressing
To avoid using stitching, the industry — led by Intel — plans to shift to larger 6×12 masks, which will enable a 26×33 mm full field in one exposure. While this looks easy on paper, make the mask twice as long, changing the mask represents an enormous ecosystem change.
Moving from 6×6-inch to 6×12-inch photomasks would require substantial changes across the existing mask ecosystem, including mask blanks and deposition, etching, inspection and metrology, cleaning, pellicles, mask writers, and mask handling systems. Crucially, High-NA EUV scanners would also have to be modified or redesigned to accommodate the larger masks, which will make the transition a major retooling effort across the semiconductor supply chain. While neither ASML nor Intel confirmed that existing or planned High-NA EUV scanners can be modified to handle larger masks, all of the future High-NA EUV scanners to be launched before and after 2033 are designed around 6×6-inch reticles and stitching, according to ASML's roadmap.
It remains to be seen whether the industry moves on to larger 6×12-inch photomasks, but Intel appears to be the main evangelist for changing the mask standard that has defined projection lithography infrastructure for decades. If the effort comes to fruition, then Intel will likely have a considerable first-mover advantage over its industry peers because it will define and set the standard for the projection lithography industry for decades to come, an advantage that is hard to overestimate.
Machine vision is becoming a practical part of Apple’s U.S. factory training strategy, giving smaller manufacturers access to techniques that help production systems inspect what they make. The recent opening of the Houston manufacturing training center extends that effort into a working electronics production campus, while courses developed with Michigan State University introduce businesses to image analysis, machine learning, and automated quality checks.
For a manufacturer, the attraction can be straightforward: finding a missing component before a product leaves the line, identifying a surface defect before more material is added, or recognizing an assembly error while it can still be corrected cheaply.
These are manageable problems with measurable costs. They also offer an accessible starting point for businesses interested in AI but unsure where it belongs inside their operations.
Machine Vision Enters the Manufacturing Curriculum
The Apple Manufacturing Academy’s current course catalog includes Machine Learning with Vision, a course introducing machine learning and deep learning through practical activities using Apple devices. It sits alongside instruction in automation, quality fundamentals, manufacturing data, maintenance, and process improvement.
That placement gives the subject useful context. A camera can produce an image, but a factory needs a decision: accept the part, flag it for review, check its position, or investigate a process that may be drifting out of tolerance.
Machine vision connects image capture to those operational decisions. Some applications use established rules to measure dimensions or identify patterns. Others use machine learning to recognize acceptable variations and defects that are difficult to describe through fixed rules.
The academy’s public description confirms introductory activities with Apple devices. It does not identify a particular iPhone, Mac configuration, software framework, or industrial camera package that every participant must use.
For smaller businesses, the educational value is learning how to define an inspection problem before purchasing equipment. A company that understands what it needs to detect can have a much more productive conversation with an automation supplier.
Houston Brings Training Closer to Production
Apple opened its 20,000-square-foot Advanced Manufacturing Center on August 13. According to the Houston opening announcement, the free program offers small and medium-sized businesses instruction in advanced manufacturing, interactive labs, and experience with representative production equipment.
The first cohort worked with machine learning for quality control and advanced automation. Participants also explored production challenges, used a holographic table, and assembled and laser etched a product.
The location adds context: the center occupies the same Houston facility that builds advanced AI servers and is scheduled to begin Mac mini manufacturing this year. Its teaching program includes final assembly principles and design considerations for printed circuit board assembly.
Houston is the company’s second U.S. manufacturing learning site, following the Detroit academy established with Michigan State University in August 2025. By the Houston opening, Apple said the academy had helped nearly 1,000 workers, students, and entrepreneurs.
That figure measures people reached through the program. It should not be interpreted as 1,000 factories already operating AI inspection systems.
Apple Machine Learning Adapters
A Useful Inspection Starts With a Specific Problem
Imagine a small business assembling control panels. Each panel needs the same set of connectors, positioned correctly before the enclosure closes. A machine vision station could check for a missing connector while the assembly remains accessible.
The value comes from catching that error at the right moment. Discovering it after packaging creates extra handling and rework. Discovering it after delivery may involve a return, a service visit, and an unhappy customer.
A useful pilot would therefore begin with that single inspection point. The business could compare the existing process with the assisted one, recording missed defects, unnecessary rechecks, inspection time, and the cost of correcting mistakes.
The camera is only part of the exercise. Workers must agree on what constitutes a defect, collect representative examples, and decide what happens when the result is uncertain.
Those decisions draw heavily on experience already present on the factory floor. An operator may know that an unusual mark is harmless, while a barely visible change in alignment predicts a later assembly problem. Turning that knowledge into consistent inspection criteria is valuable work in its own right.
These are examples of how manufacturers could apply the training, rather than projects Apple has announced for individual participants.
Teaching Machine Vision to Handle Ordinary Variation
A demonstration can look impressive when every part arrives clean, centered, and evenly lit. Production introduces variation: different surface finishes, reflections, changing positions, and batches that look slightly different while remaining within specification.
The inspection system must distinguish those acceptable differences from actual failures. Otherwise, it can reject good products or allow defective ones to continue.
Industrial vision supplier Cognex’s deployment guidance recommends validating systems across product models, defect types, and manufacturing lines. It also describes an approach in which automated inspection handles preliminary checks while experienced inspectors review borderline cases.
For a business learning machine vision, that offers a realistic way to introduce the technology. Employees can compare its decisions with their own, investigate disagreements, and determine whether the results justify extending its role.
An inspection system also needs an owner after installation. Someone must understand when a product change requires new examples, when equipment needs attention, and when performance has slipped. Training that responsibility into the workforce helps prevent an initially successful project from becoming an unreliable fixture.
Smaller Manufacturers Are Already Applying the Training
The academy’s reach extends beyond companies producing consumer electronics. In its May update on participating manufacturers, Apple highlighted Block Imaging, a Michigan business that services and refurbishes medical imaging equipment.
The company hosted visitors during the academy’s Spring Forum and described applying techniques learned from Apple engineers and Michigan State experts to its operations. Apple reported that the academy had supported more than 150 American businesses at that point.
The announcement did not identify a particular machine vision deployment at Block Imaging or publish a percentage improvement attributable to visual inspection. It does provide an example of the training reaching businesses whose work differs substantially from building an iPhone.
That wider participation could benefit Apple indirectly. More capable domestic manufacturers can support equipment maintenance, tooling, components, and specialized production services. Participation itself does not establish a supplier relationship, but the skills can be used across customers and industries.
Access Without a Large Training Budget
The academy’s participation information says eligible small and medium-sized U.S. manufacturers can take courses free of charge. Online learning includes on-demand materials and interactive modules, while in-person sessions add workshops and more personalized instruction.
Digital badges are available for different topics, and completed course materials remain accessible for review. That gives a business room to train an employee around existing production commitments and return to the material when an actual project begins.
Free instruction does not remove the eventual cost of cameras, lighting, integration, maintenance, or employee time. It can help a manufacturer understand those costs before committing to a system.
The first proposal brought back to the factory might be modest: inspect one recurring defect at one station and record the results for several weeks. A supervisor can then weigh the time saved against the extra reviews, maintenance, and mistakes. That is the kind of evidence a business owner can use when deciding whether to install a second station.
Intel is set to raise $19.7 billion by selling new common stock in a bid to finance the building out of new production capacity, the development of next-generation leading-edge process technologies like 14A and others, and day-to-day operations. While the company does not assign money to a particular project, Intel needs to build capacity to land orders from large external clients, so capacity expansion will likely be a priority. According to Bloomberg, the share sale attracted $100 billion in demand.
Intel will sell 210,526,315 shares for $95 apiece through an underwritten public offering. In addition, participating banks have 30 days to acquire as many as 31,578,947 more shares at the same $95 price, minus applicable underwriting discounts. Should they exercise all their options, Intel could sell approximately 242.1 million shares altogether and increase the proceeds to roughly $23 billion. Without the additional shares, Intel expects net proceeds of approximately $19.7 billion after underwriting discounts, commissions, and estimated expenses. The transaction is scheduled to close on August 12, 2026.
Intel's market capitalization increased from roughly $90 billion last August to $491 billion at press time, so the time is right to sell some shares and raise some much-needed cash, as the company must compete against giants like TSMC and Samsung, which spend tens of billions of dollars every year on new fabs and advanced process technologies. Meanwhile, Intel's capitalization reached its all-time high of $673 billion on June 20, 2026.
Intel has not assigned the money it is going to raise to particular projects and says the capital can be used across the business, including for capital expenditures and working capital. The company is currently ramping up its Fab 52 in Arizona and is on track to start using adjacent Fab 62 when it needs to. In addition, the company still has to build its fab complex in Ohio, which is expected to cost over $100 billion when fully built, so it badly needs money.
In its risk disclosures, the company specifically mentioned Intel 14A — which is due to enter mass production in 2028 — and other advanced process technologies, manufacturing expansion required to support them, and the need to secure design wins and volume commitments from major external foundry customers. While Intel does caution that these long-term investments amounting to tens of billions may not generate adequate returns, it is impossible to land sizeable contracts from external customers without having production capacity readily available.
Interestingly, Intel also mentioned alternative financing arrangements, government grants, and the U.S. government's significant equity position in the company among relevant factors.
House Select Committee on China Chairman John Moolenaar has written a letter that demands the U.S. government enforce an existing export control measure designed to prevent Chinese companies from getting advanced chips produced by contract chipmakers like TSMC or Samsung Foundry.
When Joe Biden was about to leave the office in early 2025, he signed a law that required chipmakers to determine their end customers in a bid to prevent contract manufacturers from unknowingly fabricating chips using American technologies for companies that served as intermediaries for restricted organizations tied to the Communist Party or the People Liberation Army. The regulation was introduced after it was discovered that chips made by TSMC for China-based Sophgo were actually Huawei's Ascend 910B AI accelerators. However, the Trump administration announced in May 2025 that it would not enforce this semiconductor regulation known as the 'Foundry Due Diligence Rule,' which naturally created uncertainty about whether the foundry-focused requirements would be actively implemented at all.
"The announcement created ambiguity as to whether front-end fabricators like TSMC can export unpackaged advanced dies to non-approved designers located outside of China, without performing the due diligence specified in the Foundry Due Diligence Interim Final Rule (IFR)," the letter reads. "These exports enabled Huawei to obtain millions of controlled Ascend logic dies from TSMC, using its front company, Sophgo in 2023 and 2024."
Before the adoption of the 'Foundry Due Diligence Rule,' Chinese companies and/or their intermediaries could misrepresent chip specifications and end users when placing orders with TSMC or other foundries, which allowed restricted devices to be made despite U.S. export controls. Under the rule, foundries and OSAT providers exporting chips produced on 14/16nm-class process technologies or more advanced nodes must presume those devices qualify as controlled AI processors subject to a global licensing requirement, unless they meet an exemption. According to the letter, foundries have generally complied with these requirements since the rule took effect. As a result, Moolenaar essentially asks the government to enforce the existing controls rather than introduce stricter export controls.
Moolenaar believes that the Commerce Department's Bureau of Industry and Security could clarify its current stance on the Foundry Due Diligence Rule in two ways:
By issuing guidance, which confirms that the worldwide Regional Stability (RS) licensing requirement still applies to exports from front-end foundries;
By formally annulling the AI Diffusion IFR and amending §744.23 to explicitly restore that requirement for both foundries and OSAT providers.
Either approach would eliminate conflicting interpretations and reinforce enforcement of existing export controls, Moolenaar believes.
Apple used to be among a few companies willing to buy memory and other components worth billions of dollars under long-term supply contracts at fixed prices. But the artificial intelligence era represents a new reality with new purchasing champions, marking a tectonic shift in the high-tech world. Alphabet, Microsoft, Meta, and Amazon have purchase commitments totaling about $2 trillion, and a significant portion of these commitments are for memory, according to estimates by analyst Claus Aasholm. While the commitments are approximate, span many years, and should be generally taken with a grain of salt, they still reflect the direction the industry is moving.
Combined purchasing commitments from the four major hyperscalers shown in the chart —Amazon, Alphabet, Meta, and Microsoft — reached nearly $2 trillion by Q2 2026, with Alphabet and Microsoft accounting for the overwhelming majority of the total.
The rapid expansion suggests several major findings. Firstly, the AI infrastructure race is accelerating, not stabilizing. Secondly, AI infrastructure investments are driven by a handful of hyperscale cloud service providers (CSPs) whose long-term procurement commitments now vastly exceed those of traditional consumer electronics companies such as Apple.
Thirdly, memory has become a strategic asset — perhaps a competition weapon — rather than a commodity. Fourthly, suppliers of memory — both 3D NAND and DRAM — are gaining pricing power. Finally, demand for memory will likely drive major capacity expansion at Micron, Samsung, and SK hynix, even though so far these companies have been exceptionally disciplined about their capacity investments.
Almost $2 trillion commitments
Google shows by far the most aggressive increase in purchasing commitments, rising from roughly $140 – $150 billion in Q3 2025 to around $811 billion by Q2 2026 (though these are total purchase commitments by Alphabet, not specifically memory purchase commitments), while Microsoft follows a similar trajectory and reaches approximately $678 billion in total obligations, which includes, but is not limited to memory.
Meta is also ramping commitments substantially to around $349.3 billion (again, these are total commitments), whereas Amazon increased its commitments more gradually to roughly $130 billion. By contrast, Apple — which makes the world's most popular smartphone, and which was the largest consumer of memory just a couple of years ago — remains almost flat throughout the period at approximately $57 billion (of which $56.2 billion is payable within 12 months). Apple's commitments fall well short of Nvidia's commitments of $119 billion.
Memory suppliers used to buzz around Apple like fruit flies, but now they have discovered larger commitments.Apple's purchasing commitments have not changed, suggesting a reluctance to follow the new market rules.https://t.co/0pRbk8aYVJ pic.twitter.com/t2VNm7uw1dAugust 6, 2026
Again, we are talking about total purchase commitments, which include foundry capacity, 3D NAND, and DRAM memory, but are not limited to them. Alphabet, Amazon, Meta, and Microsoft all build custom silicon and custom servers, so a significant portion of these commitments is to various EMS providers.
While $1.968 trillion of purchase commitments for memory and storage alone would be an absurdly large amount of money, a huge portion of these commitments consists of contract manufacturing obligations as well as memory chips. This suggests that the foundry, 3D NAND, and DRAM markets are entering a new phase in which hyperscalers are willing to make vastly larger forward purchasing commitments than traditional consumer-electronics companies, giving suppliers a strong incentive to prioritize customers prepared to secure future capacity on that scale.
Strategic assets
While Claus Aasholm's chart is explicitly dedicated to memory, it does describe total purchase commitments of tech giants, so the chart can reasonably be read as evidence that memory and capacity at TSMC, Samsung Foundry, and GlobalFoundries are becoming a strategic asset rather than merely another component to procure at the best available price.
AI infrastructure requires enormous quantities of AI accelerators, DRAM (including HBM), and 3D NAND. Meanwhile, the supply of high-end memory (HBM) is constrained by fab capacity at major DRAM makers, whereas the supply of AI accelerators is constrained by both wafer capacity and foundries and packaging capacity at foundries and their OSAT partners. As a result, hyperscaler CSPs have an incentive to lock in supply years ahead, even if doing so requires exceptionally large purchasing commitments.
That also changes the relationship between semiconductor suppliers and their customers. In theory, a company willing to guarantee hundreds of billions of dollars of future purchases can effectively help underwrite expansions of foundry, memory, and advanced packaging capacity and, in return, secure priority access to scarce products and future process technologies. In reality, TSMC can well afford capacity expansion using the money it gets from hyperscalers and give priority to its largest customers. In this environment, access to DDR5, HBM, and 3D NAND memory becomes part of the competitive advantage rather than merely a procurement exercise.
This is also what makes Apple's position in the graph interesting: its purchasing commitments barely move while those of Alphabet, Amazon, Meta, and Microsoft surge. If the trend continues, Apple may remain one of the world's largest semiconductor buyers in absolute terms, but the question is whether it will be among the key customers that foundries, memory makers, and OSATs plan their future capacity expansions.
An inflection point
Perhaps the most interesting takeaway of the findings revealed by long-term purchase commitments is that the industry's center of gravity appears to have shifted.
During the smartphone era, foundries (well, TSMC has won) and memory suppliers often competed aggressively for Apple's business because of its enormous purchasing power. Today, hyperscalers building AI infrastructure are making purchasing commitments that dwarf those of traditional CE companies like Apple, which may well represent a strategic inflection point akin to the one Andy Grove described in his 'Only the Paranoid Survive' book.
Will this tectonic shift result in prioritization of customers capable of enabling future capacity expansions through massive long-term purchase agreements, or will foundries and memory makers remain more or less disciplined with their capacity expansions so as not to lose a lot when demand declines? This is a question that has yet to be asked.
In any case, the AI megatrend has transformed semiconductors — from foundries to advanced packaging and from DDR5 to HBM4 — into strategic assets that can no longer be treated as ordinary components procured on demand. And this is something that will continue in the long run.
As data centers gobble up memory chips, other industries that need the components, including electronics companies like Apple and medical device makers, are asking for government help.
Most megafactories usually take years to go from conceptualization to construction, but a recent drone flyover of the Terafab showed that progress has already started on the ground less than five months after Musk unveiled it. However, the video doesn’t do justice to the true scale of its footprint, so X user Nic Cruz Patane created a visualization to help us understand how large the chip manufacturing facility is.
Terafab approximate size comparison between Giga Texas, the Pentagon, Apple Park, and the Mall of America.There has never been a building this large. Elon Musk says it will be the most valuable building by far. pic.twitter.com/GCmpfeduJnAugust 6, 2026
The site will reportedly have a floor space of at least 100 million square feet, making it larger than Giga Texas (10 million sq. ft), the Pentagon (6.6 million sq. ft), Apple Park (2.82 million sq. ft), and the Mall of America (5.6 million sq. ft), combined. This also makes it significantly larger than New Century Global Center in Chengdu, China, with has an interior space of “just” 18.9 million sq. ft.
While this might seem like an absurd amount of space for chip manufacturing, it appears that the Terafab will need it because it’s going to be more than just a chip fab making AI processors — instead, it will be an all-in-one facility that will produce logic and memory chips, as well as have lithography, packaging, and testing under one roof.
Elon Musk started talking about building his own chip manufacturing facility in late 2025 and officially announced the project in March of this year. The reasoning behind this project is that both SpaceX and Tesla will require at least 1TW of compute, which is more than ten times that current global chip supply.
Nvidia CEO Jensen Huang warned that a project like this will be an “extremely hard” challenge, but it appears that Musk is willing to put his massive resources on the line for this. Intel CEO Lip-Bu Tan even said that he can “think of no better partner than Elon Musk” to explore “unconventional” ways of chip manufacturing.
Musk is no stranger to both leading and funding projects that otherwise seemed impossible. Although he did not found Tesla, his investment and leadership in the company led it to become an industry trailblazer in EVs. He fundamentally changed commercial space travel with SpaceX; something that used to be the purview of NASA and other national governments, and he also broke a record when he set up 100,000 Nvidia H200 GPUs in just 19 days back in 2024 — a process which Huang said usually takes four years.
It seems that Terafab is Musk’s biggest project to date, which is estimated to require up to $119 billion in investments. But even though it seems that this project already has a secure customer base in SpaceX and Tesla, the former acknowledges that there’s a risk that this ambitious megafactory may not be successful.
A new study is challenging one of the most persistent assumptions in space manufacturing: that building advanced composite structures beyond Earth is simply a matter of moving terrestrial production methods into orbit. Research published in npj Advanced Manufacturing examines how two defining features of the space environment—reduced gravity and reduced atmospheric pressure—can alter the manufacture of carbon-fiber-reinforced structures, materials widely regarded as essential for future spacecraft, habitats and large orbital infrastructure.
Carbon-fiber-reinforced polymers, commonly known as CFRPs, combine strong, lightweight carbon fibers with a polymer resin that binds the fibers into a rigid composite. Their exceptional strength-to-weight ratio makes them attractive for launch vehicles and spacecraft, where every kilogram matters. Yet manufacturing these materials is a delicate process. Fibers must be positioned accurately, resin must penetrate the reinforcement evenly, and gases or trapped voids must be removed before the material cures. On Earth, gravity and atmospheric pressure quietly assist—or complicate—each of these steps.
In space, those familiar forces change dramatically. Reduced gravity can alter how liquid resin flows through a carbon-fiber structure, while low pressure can encourage dissolved gases and volatile compounds to expand or escape. Together, these effects may influence impregnation, consolidation, curing and the final mechanical performance of a composite part. The new work by R. Strecker, T. Rieger, A. Tabelander and colleagues focuses on understanding these interactions before manufacturers attempt to produce increasingly complex structures in orbit.
The central issue is void formation. A composite that appears solid can contain microscopic pockets of air or vapor between its fibers. These voids interrupt the transfer of stress through the material and can reduce strength, stiffness and fatigue resistance. During conventional manufacturing on Earth, pressure is often applied to compress the layers and drive out unwanted gases while resin fills the spaces between fibers. In a reduced-gravity environment, however, buoyancy-driven movement is weakened, and the pathways through which bubbles travel may change. A bubble that would rise and escape during terrestrial processing could remain trapped inside the structure.
Pressure reduction introduces another layer of complexity. Lower ambient pressure can help remove volatile substances and trapped gases, but it can also cause dissolved gases in the resin to expand. If the resin is not sufficiently mobile, expanding bubbles may become locked in place as the material cures. The balance between degassing and bubble growth therefore becomes a critical manufacturing parameter. The study’s importance lies in treating pressure and gravity not as isolated variables, but as environmental conditions that can interact throughout the production cycle.
Resin flow is equally important. Carbon-fiber reinforcements are made from tightly packed filaments, creating narrow channels through which resin must travel. On Earth, gravity can influence resin distribution, especially in vertically oriented or large components. In reduced gravity, capillary forces and surface tension become relatively more significant. These forces can help draw resin into small spaces, but they may also create uneven wetting patterns depending on the fiber architecture, resin viscosity and processing orientation. Such changes could affect whether a component cures uniformly from its surface to its interior.
The findings carry implications far beyond laboratory samples. Future space manufacturers may seek to fabricate beams, pressure-vessel elements, antenna supports, solar-array components and repair patches directly in orbit. Producing these parts where they are needed could reduce the need to launch bulky finished structures from Earth. It could also enable designs too large to fit inside a rocket fairing, including trusses and habitation modules assembled gradually in space. But the economic and engineering promise of this approach depends on reliable quality control. A component that looks flawless may still fail if its internal fiber alignment, resin distribution or void content is inconsistent.
The research also highlights why manufacturing hardware designed for Earth cannot automatically be considered space-ready. Pumps, heaters, vacuum systems, molds and curing chambers must all operate under conditions in which heat transfer, fluid movement and gas removal behave differently. Temperature control is particularly important because resin viscosity changes strongly with temperature. A resin that flows readily during terrestrial processing might move more slowly or unevenly in orbit, while excessive heating could accelerate curing before impregnation is complete. Space-based production systems will therefore need carefully coordinated control of pressure, temperature, resin chemistry and processing time.
For engineers, the study provides a foundation for developing manufacturing protocols tailored to reduced-gravity environments. Instead of copying Earth-based workflows, future systems may need staged pressure changes, specialized fiber preforms, modified resin formulations or active bubble-management techniques. Sensors could monitor pressure, temperature and resin flow in real time, allowing automated systems to detect defects before a part is finished. Non-destructive inspection, including imaging and ultrasonic testing, will also be essential for verifying the integrity of components that cannot easily be returned to Earth for analysis.
The broader message is that space manufacturing is not merely an extension of industrial production—it is a new manufacturing regime governed by different physics. Understanding how gravity and pressure reshape the behavior of fluids, gases and composite materials could determine whether orbital fabrication remains a promising experiment or becomes a practical industrial capability. By examining the production of carbon-fiber-reinforced structures under space-relevant conditions, Strecker, Rieger, Tabelander and their colleagues are helping identify the hidden variables that will decide how safely and efficiently humanity can build beyond Earth.
Subject of Research: Effects of reduced gravity and reduced atmospheric pressure on the in-space manufacturing of carbon-fiber-reinforced structures
Article Title: Effects of reduced gravity and reduced atmospheric pressure on in-space manufacturing of carbon-fiber-reinforced structures
Article References: Strecker, R., Rieger, T., Tabelander, A. et al. Effects of reduced gravity and reduced atmospheric pressure on in-space manufacturing of carbon-fiber-reinforced structures. npj Adv. Manuf.3, 26 (2026). https://doi.org/10.1038/s44334-026-00104-w
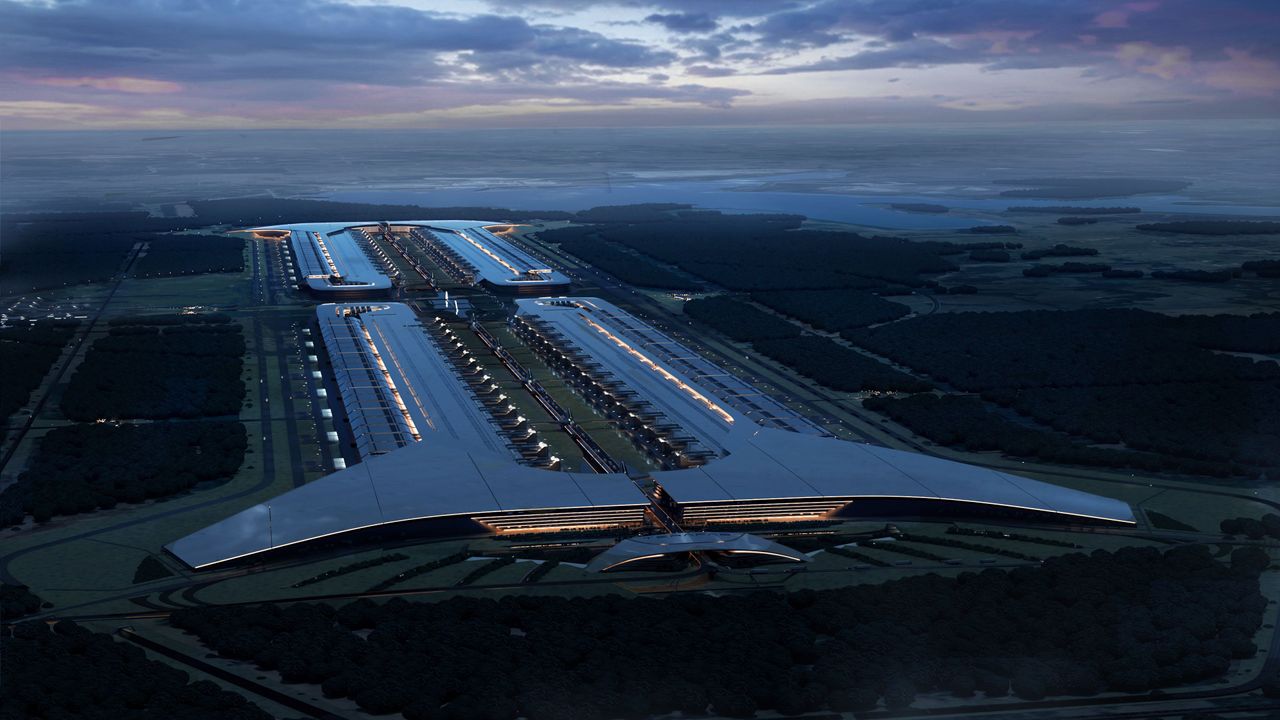
SpaceX and Tesla on Thursday formally unveiled plans for the initial phase of their Terafab project. The first stage of the plan — which is expected to use Intel's 14A process technology — is expected to require $16.8 billion in investment, while the completed campus is planned to encompass more than 100 million square feet of manufacturing space. The massive semiconductor manufacturing complex will be built in Grimes County, Texas, at a location that belongs to SpaceX.
According to SpaceX and Tesla, their combined demand for semiconductors is projected to exceed 1 terawatt (TW) of compute per year, which significantly exceeds today's global supply. In fact, SpaceX, Tesla, and xAI already consume a significant portion of contract chipmaking services available today, and can potentially justify building a dedicated fab that will exclusively serve Elon Musk's companies. In particular, Terafab is envisioned to exclusively produce AI inference processors for Tesla Optimus humanoid robots and Cybercab autonomous vehicles, as well as 'high-power' processors intended for SpaceX's space-based data centers. Meanwhile, SpaceX and Tesla have not disclosed when their combined demand for compute per year will hit the 1 TW benchmark.
Unlike a conventional semiconductor fab, Terafab is envisioned as a vertically integrated manufacturing campus where advanced logic devices, memory chips, packaging, and testing operations are housed together. Normally, logic and memory are produced at different fabs using different process technologies, whereas packaging and testing services are performed at different facilities. However, the companies believe that consolidating logic, memory, packaging, and testing in one location will not only shorten the production cycle but will also shorten time-to-yield by enabling faster iterative improvements.
Given the description and the goal of the project, this will be a massive facility. Yet, SpaceX and Tesla have said little about its capabilities; The only thing they have disclosed is that the current facility in Grimes County will feature '100 million square feet of manufacturing space.' The 100 million square feet (9.3 million square meters) figure immediately stands out because it is far beyond anything ever announced for a semiconductor manufacturing facility. For example, the total area of Samsung's Pyeongtaek campus is approximately 2.89 million square meters, or 31.1 million square feet. A single Samsung fab occupies about 120,000 square meters, or 1.29 million square feet. However, the key wording is important: '100 million square feet of manufacturing space' does not mean 100 million square feet of cleanroom space.
Based on an image published by SpaceX, the Terafab facility will occupy four massive buildings. It is unclear whether these buildings will be four phases of the project (i.e., logic, memory, and packaging will be made under one roof) or will serve different purposes (i.e., one building makes logic, another produces memory, yet another does testing and packaging). In any case, when fully built, Terafab will be a massive semiconductor production campus that will require significantly more than $16.8 billion.
The announcement claims that the Terafab facility will employ at least 3,000 people, and that between 60% and 80% of them will be Grimes and nearby Brazos County residents.
Terafab is expected to use water from Gibbons Creek Reservoir instead of local groundwater and feature on-site wastewater treatment as well as water recycling and conservation measures.
The announcement follows Tesla's groundbreaking earlier this year on a research semiconductor facility at the North Campus of Tesla's Giga Texas campus, which the companies describe as a precursor to Terafab.
The administration will impose a minimum import price for polysilicon, a key component for semiconductors and solar panels, as well as tariffs for products made with the material.

 Login