❌

Reading view

Intel raises $19.7 billion to help fund future projects as 14A production looms — share sale attracted $100 billion in demand, report claims

Intel is set to raise $19.7 billion by selling new common stock in a bid to finance the building out of new production capacity, the development of next-generation leading-edge process technologies like 14A and others, and day-to-day operations. While the company does not assign money to a particular project, Intel needs to build capacity to land orders from large external clients, so capacity expansion will likely be a priority. According to Bloomberg, the share sale attracted $100 billion in demand.

Intel will sell 210,526,315 shares for $95 apiece through an underwritten public offering. In addition, participating banks have 30 days to acquire as many as 31,578,947 more shares at the same $95 price, minus applicable underwriting discounts. Should they exercise all their options, Intel could sell approximately 242.1 million shares altogether and increase the proceeds to roughly $23 billion. Without the additional shares, Intel expects net proceeds of approximately $19.7 billion after underwriting discounts, commissions, and estimated expenses. The transaction is scheduled to close on August 12, 2026.

Intel's market capitalization increased from roughly $90 billion last August to $491 billion at press time, so the time is right to sell some shares and raise some much-needed cash, as the company must compete against giants like TSMC and Samsung, which spend tens of billions of dollars every year on new fabs and advanced process technologies. Meanwhile, Intel's capitalization reached its all-time high of $673 billion on June 20, 2026.

Intel has not assigned the money it is going to raise to particular projects and says the capital can be used across the business, including for capital expenditures and working capital. The company is currently ramping up its Fab 52 in Arizona and is on track to start using adjacent Fab 62 when it needs to. In addition, the company still has to build its fab complex in Ohio, which is expected to cost over $100 billion when fully built, so it badly needs money.

In its risk disclosures, the company specifically mentioned Intel 14A — which is due to enter mass production in 2028 — and other advanced process technologies, manufacturing expansion required to support them, and the need to secure design wins and volume commitments from major external foundry customers. While Intel does caution that these long-term investments amounting to tens of billions may not generate adequate returns, it is impossible to land sizeable contracts from external customers without having production capacity readily available.

Interestingly, Intel also mentioned alternative financing arrangements, government grants, and the U.S. government's significant equity position in the company among relevant factors.

  •  

US lawmaker wants gov't to enforce regulation to ensure 'chipmakers conduct adequate due diligence on their customers' — House member calls for Biden-era export control to be enforced

House Select Committee on China Chairman John Moolenaar has written a letter that demands the U.S. government enforce an existing export control measure designed to prevent Chinese companies from getting advanced chips produced by contract chipmakers like TSMC or Samsung Foundry.

When Joe Biden was about to leave the office in early 2025, he signed a law that required chipmakers to determine their end customers in a bid to prevent contract manufacturers from unknowingly fabricating chips using American technologies for companies that served as intermediaries for restricted organizations tied to the Communist Party or the People Liberation Army. The regulation was introduced after it was discovered that chips made by TSMC for China-based Sophgo were actually Huawei's Ascend 910B AI accelerators. However, the Trump administration announced in May 2025 that it would not enforce this semiconductor regulation known as the 'Foundry Due Diligence Rule,' which naturally created uncertainty about whether the foundry-focused requirements would be actively implemented at all.

"The announcement created ambiguity as to whether front-end fabricators like TSMC can export unpackaged advanced dies to non-approved designers located outside of China, without performing the due diligence specified in the Foundry Due Diligence Interim Final Rule (IFR)," the letter reads. "These exports enabled Huawei to obtain millions of controlled Ascend logic dies from TSMC, using its front company, Sophgo in 2023 and 2024."

Before the adoption of the 'Foundry Due Diligence Rule,' Chinese companies and/or their intermediaries could misrepresent chip specifications and end users when placing orders with TSMC or other foundries, which allowed restricted devices to be made despite U.S. export controls. Under the rule, foundries and OSAT providers exporting chips produced on 14/16nm-class process technologies or more advanced nodes must presume those devices qualify as controlled AI processors subject to a global licensing requirement, unless they meet an exemption. According to the letter, foundries have generally complied with these requirements since the rule took effect. As a result, Moolenaar essentially asks the government to enforce the existing controls rather than introduce stricter export controls.

Moolenaar believes that the Commerce Department's Bureau of Industry and Security could clarify its current stance on the Foundry Due Diligence Rule in two ways:

  • By issuing guidance, which confirms that the worldwide Regional Stability (RS) licensing requirement still applies to exports from front-end foundries;
  • By formally annulling the AI Diffusion IFR and amending §744.23 to explicitly restore that requirement for both foundries and OSAT providers.

Either approach would eliminate conflicting interpretations and reinforce enforcement of existing export controls, Moolenaar believes.

  •  

Hyperscalers commit nearly $2 trillion to secure AI hardware and memory — Google leads $811 billion spending surge while Apple trails at $57 billion

Apple used to be among a few companies willing to buy memory and other components worth billions of dollars under long-term supply contracts at fixed prices. But the artificial intelligence era represents a new reality with new purchasing champions, marking a tectonic shift in the high-tech world. Alphabet, Microsoft, Meta, and Amazon have purchase commitments totaling about $2 trillion, and a significant portion of these commitments are for memory, according to estimates by analyst Claus Aasholm. While the commitments are approximate, span many years, and should be generally taken with a grain of salt, they still reflect the direction the industry is moving.

Combined purchasing commitments from the four major hyperscalers shown in the chart —Amazon, Alphabet, Meta, and Microsoft — reached nearly $2 trillion by Q2 2026, with Alphabet and Microsoft accounting for the overwhelming majority of the total.

The rapid expansion suggests several major findings. Firstly, the AI infrastructure race is accelerating, not stabilizing. Secondly, AI infrastructure investments are driven by a handful of hyperscale cloud service providers (CSPs) whose long-term procurement commitments now vastly exceed those of traditional consumer electronics companies such as Apple.

Thirdly, memory has become a strategic asset — perhaps a competition weapon — rather than a commodity. Fourthly, suppliers of memory — both 3D NAND and DRAM — are gaining pricing power. Finally, demand for memory will likely drive major capacity expansion at Micron, Samsung, and SK hynix, even though so far these companies have been exceptionally disciplined about their capacity investments.

Almost $2 trillion commitments

Google shows by far the most aggressive increase in purchasing commitments, rising from roughly $140 – $150 billion in Q3 2025 to around $811 billion by Q2 2026 (though these are total purchase commitments by Alphabet, not specifically memory purchase commitments), while Microsoft follows a similar trajectory and reaches approximately $678 billion in total obligations, which includes, but is not limited to memory.

Meta is also ramping commitments substantially to around $349.3 billion (again, these are total commitments), whereas Amazon increased its commitments more gradually to roughly $130 billion. By contrast, Apple — which makes the world's most popular smartphone, and which was the largest consumer of memory just a couple of years ago — remains almost flat throughout the period at approximately $57 billion (of which $56.2 billion is payable within 12 months). Apple's commitments fall well short of Nvidia's commitments of $119 billion.

Memory suppliers used to buzz around Apple like fruit flies, but now they have discovered larger commitments.Apple's purchasing commitments have not changed, suggesting a reluctance to follow the new market rules.https://t.co/0pRbk8aYVJ pic.twitter.com/t2VNm7uw1dAugust 6, 2026

Again, we are talking about total purchase commitments, which include foundry capacity, 3D NAND, and DRAM memory, but are not limited to them. Alphabet, Amazon, Meta, and Microsoft all build custom silicon and custom servers, so a significant portion of these commitments is to various EMS providers.

While $1.968 trillion of purchase commitments for memory and storage alone would be an absurdly large amount of money, a huge portion of these commitments consists of contract manufacturing obligations as well as memory chips. This suggests that the foundry, 3D NAND, and DRAM markets are entering a new phase in which hyperscalers are willing to make vastly larger forward purchasing commitments than traditional consumer-electronics companies, giving suppliers a strong incentive to prioritize customers prepared to secure future capacity on that scale.

Strategic assets

While Claus Aasholm's chart is explicitly dedicated to memory, it does describe total purchase commitments of tech giants, so the chart can reasonably be read as evidence that memory and capacity at TSMC, Samsung Foundry, and GlobalFoundries are becoming a strategic asset rather than merely another component to procure at the best available price.

AI infrastructure requires enormous quantities of AI accelerators, DRAM (including HBM), and 3D NAND. Meanwhile, the supply of high-end memory (HBM) is constrained by fab capacity at major DRAM makers, whereas the supply of AI accelerators is constrained by both wafer capacity and foundries and packaging capacity at foundries and their OSAT partners. As a result, hyperscaler CSPs have an incentive to lock in supply years ahead, even if doing so requires exceptionally large purchasing commitments.

That also changes the relationship between semiconductor suppliers and their customers. In theory, a company willing to guarantee hundreds of billions of dollars of future purchases can effectively help underwrite expansions of foundry, memory, and advanced packaging capacity and, in return, secure priority access to scarce products and future process technologies. In reality, TSMC can well afford capacity expansion using the money it gets from hyperscalers and give priority to its largest customers. In this environment, access to DDR5, HBM, and 3D NAND memory becomes part of the competitive advantage rather than merely a procurement exercise.

This is also what makes Apple's position in the graph interesting: its purchasing commitments barely move while those of Alphabet, Amazon, Meta, and Microsoft surge. If the trend continues, Apple may remain one of the world's largest semiconductor buyers in absolute terms, but the question is whether it will be among the key customers that foundries, memory makers, and OSATs plan their future capacity expansions.

An inflection point

Perhaps the most interesting takeaway of the findings revealed by long-term purchase commitments is that the industry's center of gravity appears to have shifted.

During the smartphone era, foundries (well, TSMC has won) and memory suppliers often competed aggressively for Apple's business because of its enormous purchasing power. Today, hyperscalers building AI infrastructure are making purchasing commitments that dwarf those of traditional CE companies like Apple, which may well represent a strategic inflection point akin to the one Andy Grove described in his 'Only the Paranoid Survive' book.

Will this tectonic shift result in prioritization of customers capable of enabling future capacity expansions through massive long-term purchase agreements, or will foundries and memory makers remain more or less disciplined with their capacity expansions so as not to lose a lot when demand declines? This is a question that has yet to be asked.

In any case, the AI megatrend has transformed semiconductors — from foundries to advanced packaging and from DDR5 to HBM4 — into strategic assets that can no longer be treated as ordinary components procured on demand. And this is something that will continue in the long run.

  •  

Musk’s Terafab projected to be larger than the Pentagon, Apple Park, Mall of America, and Giga Texas, combined — all-in-one chip manufacturing facility visualized to show the project’s massive footprint

Most megafactories usually take years to go from conceptualization to construction, but a recent drone flyover of the Terafab showed that progress has already started on the ground less than five months after Musk unveiled it. However, the video doesn’t do justice to the true scale of its footprint, so X user Nic Cruz Patane created a visualization to help us understand how large the chip manufacturing facility is.

Terafab approximate size comparison between Giga Texas, the Pentagon, Apple Park, and the Mall of America.There has never been a building this large. Elon Musk says it will be the most valuable building by far. pic.twitter.com/GCmpfeduJnAugust 6, 2026

The site will reportedly have a floor space of at least 100 million square feet, making it larger than Giga Texas (10 million sq. ft), the Pentagon (6.6 million sq. ft), Apple Park (2.82 million sq. ft), and the Mall of America (5.6 million sq. ft), combined. This also makes it significantly larger than New Century Global Center in Chengdu, China, with has an interior space of “just” 18.9 million sq. ft.

While this might seem like an absurd amount of space for chip manufacturing, it appears that the Terafab will need it because it’s going to be more than just a chip fab making AI processors — instead, it will be an all-in-one facility that will produce logic and memory chips, as well as have lithography, packaging, and testing under one roof.

Elon Musk started talking about building his own chip manufacturing facility in late 2025 and officially announced the project in March of this year. The reasoning behind this project is that both SpaceX and Tesla will require at least 1TW of compute, which is more than ten times that current global chip supply.

Nvidia CEO Jensen Huang warned that a project like this will be an “extremely hard” challenge, but it appears that Musk is willing to put his massive resources on the line for this. Intel CEO Lip-Bu Tan even said that he can “think of no better partner than Elon Musk” to explore “unconventional” ways of chip manufacturing.

Musk is no stranger to both leading and funding projects that otherwise seemed impossible. Although he did not found Tesla, his investment and leadership in the company led it to become an industry trailblazer in EVs. He fundamentally changed commercial space travel with SpaceX; something that used to be the purview of NASA and other national governments, and he also broke a record when he set up 100,000 Nvidia H200 GPUs in just 19 days back in 2024 — a process which Huang said usually takes four years.

It seems that Terafab is Musk’s biggest project to date, which is estimated to require up to $119 billion in investments. But even though it seems that this project already has a secure customer base in SpaceX and Tesla, the former acknowledges that there’s a risk that this ambitious megafactory may not be successful.

  •  

How Low Gravity and Pressure Affect Space Manufacturing of Carbon-Fiber Structures

A new study is challenging one of the most persistent assumptions in space manufacturing: that building advanced composite structures beyond Earth is simply a matter of moving terrestrial production methods into orbit. Research published in npj Advanced Manufacturing examines how two defining features of the space environment—reduced gravity and reduced atmospheric pressure—can alter the manufacture of carbon-fiber-reinforced structures, materials widely regarded as essential for future spacecraft, habitats and large orbital infrastructure.

Carbon-fiber-reinforced polymers, commonly known as CFRPs, combine strong, lightweight carbon fibers with a polymer resin that binds the fibers into a rigid composite. Their exceptional strength-to-weight ratio makes them attractive for launch vehicles and spacecraft, where every kilogram matters. Yet manufacturing these materials is a delicate process. Fibers must be positioned accurately, resin must penetrate the reinforcement evenly, and gases or trapped voids must be removed before the material cures. On Earth, gravity and atmospheric pressure quietly assist—or complicate—each of these steps.

In space, those familiar forces change dramatically. Reduced gravity can alter how liquid resin flows through a carbon-fiber structure, while low pressure can encourage dissolved gases and volatile compounds to expand or escape. Together, these effects may influence impregnation, consolidation, curing and the final mechanical performance of a composite part. The new work by R. Strecker, T. Rieger, A. Tabelander and colleagues focuses on understanding these interactions before manufacturers attempt to produce increasingly complex structures in orbit.

The central issue is void formation. A composite that appears solid can contain microscopic pockets of air or vapor between its fibers. These voids interrupt the transfer of stress through the material and can reduce strength, stiffness and fatigue resistance. During conventional manufacturing on Earth, pressure is often applied to compress the layers and drive out unwanted gases while resin fills the spaces between fibers. In a reduced-gravity environment, however, buoyancy-driven movement is weakened, and the pathways through which bubbles travel may change. A bubble that would rise and escape during terrestrial processing could remain trapped inside the structure.

Pressure reduction introduces another layer of complexity. Lower ambient pressure can help remove volatile substances and trapped gases, but it can also cause dissolved gases in the resin to expand. If the resin is not sufficiently mobile, expanding bubbles may become locked in place as the material cures. The balance between degassing and bubble growth therefore becomes a critical manufacturing parameter. The study’s importance lies in treating pressure and gravity not as isolated variables, but as environmental conditions that can interact throughout the production cycle.

Resin flow is equally important. Carbon-fiber reinforcements are made from tightly packed filaments, creating narrow channels through which resin must travel. On Earth, gravity can influence resin distribution, especially in vertically oriented or large components. In reduced gravity, capillary forces and surface tension become relatively more significant. These forces can help draw resin into small spaces, but they may also create uneven wetting patterns depending on the fiber architecture, resin viscosity and processing orientation. Such changes could affect whether a component cures uniformly from its surface to its interior.

The findings carry implications far beyond laboratory samples. Future space manufacturers may seek to fabricate beams, pressure-vessel elements, antenna supports, solar-array components and repair patches directly in orbit. Producing these parts where they are needed could reduce the need to launch bulky finished structures from Earth. It could also enable designs too large to fit inside a rocket fairing, including trusses and habitation modules assembled gradually in space. But the economic and engineering promise of this approach depends on reliable quality control. A component that looks flawless may still fail if its internal fiber alignment, resin distribution or void content is inconsistent.

The research also highlights why manufacturing hardware designed for Earth cannot automatically be considered space-ready. Pumps, heaters, vacuum systems, molds and curing chambers must all operate under conditions in which heat transfer, fluid movement and gas removal behave differently. Temperature control is particularly important because resin viscosity changes strongly with temperature. A resin that flows readily during terrestrial processing might move more slowly or unevenly in orbit, while excessive heating could accelerate curing before impregnation is complete. Space-based production systems will therefore need carefully coordinated control of pressure, temperature, resin chemistry and processing time.

For engineers, the study provides a foundation for developing manufacturing protocols tailored to reduced-gravity environments. Instead of copying Earth-based workflows, future systems may need staged pressure changes, specialized fiber preforms, modified resin formulations or active bubble-management techniques. Sensors could monitor pressure, temperature and resin flow in real time, allowing automated systems to detect defects before a part is finished. Non-destructive inspection, including imaging and ultrasonic testing, will also be essential for verifying the integrity of components that cannot easily be returned to Earth for analysis.

The broader message is that space manufacturing is not merely an extension of industrial production—it is a new manufacturing regime governed by different physics. Understanding how gravity and pressure reshape the behavior of fluids, gases and composite materials could determine whether orbital fabrication remains a promising experiment or becomes a practical industrial capability. By examining the production of carbon-fiber-reinforced structures under space-relevant conditions, Strecker, Rieger, Tabelander and their colleagues are helping identify the hidden variables that will decide how safely and efficiently humanity can build beyond Earth.

Subject of Research: Effects of reduced gravity and reduced atmospheric pressure on the in-space manufacturing of carbon-fiber-reinforced structures

Article Title: Effects of reduced gravity and reduced atmospheric pressure on in-space manufacturing of carbon-fiber-reinforced structures

Article References: Strecker, R., Rieger, T., Tabelander, A. et al. Effects of reduced gravity and reduced atmospheric pressure on in-space manufacturing of carbon-fiber-reinforced structures. npj Adv. Manuf. 3, 26 (2026). https://doi.org/10.1038/s44334-026-00104-w

Image Credits: AI Generated

DOI: https://doi.org/10.1038/s44334-026-00104-w

Keywords: in-space manufacturing, carbon-fiber-reinforced polymers, reduced gravity, reduced atmospheric pressure, composite materials, resin flow, void formation, space technology

  •  

Elon Musk's massive Terafab chip-making facility starts to take shape — 100 million square feet of manufacturing space and $16.8B initial capital investment

SpaceX and Tesla on Thursday formally unveiled plans for the initial phase of their Terafab project. The first stage of the plan — which is expected to use Intel's 14A process technology — is expected to require $16.8 billion in investment, while the completed campus is planned to encompass more than 100 million square feet of manufacturing space. The massive semiconductor manufacturing complex will be built in Grimes County, Texas, at a location that belongs to SpaceX.

According to SpaceX and Tesla, their combined demand for semiconductors is projected to exceed 1 terawatt (TW) of compute per year, which significantly exceeds today's global supply. In fact, SpaceX, Tesla, and xAI already consume a significant portion of contract chipmaking services available today, and can potentially justify building a dedicated fab that will exclusively serve Elon Musk's companies. In particular, Terafab is envisioned to exclusively produce AI inference processors for Tesla Optimus humanoid robots and Cybercab autonomous vehicles, as well as 'high-power' processors intended for SpaceX's space-based data centers. Meanwhile, SpaceX and Tesla have not disclosed when their combined demand for compute per year will hit the 1 TW benchmark.

Unlike a conventional semiconductor fab, Terafab is envisioned as a vertically integrated manufacturing campus where advanced logic devices, memory chips, packaging, and testing operations are housed together. Normally, logic and memory are produced at different fabs using different process technologies, whereas packaging and testing services are performed at different facilities. However, the companies believe that consolidating logic, memory, packaging, and testing in one location will not only shorten the production cycle but will also shorten time-to-yield by enabling faster iterative improvements.

Given the description and the goal of the project, this will be a massive facility. Yet, SpaceX and Tesla have said little about its capabilities; The only thing they have disclosed is that the current facility in Grimes County will feature '100 million square feet of manufacturing space.' The 100 million square feet (9.3 million square meters) figure immediately stands out because it is far beyond anything ever announced for a semiconductor manufacturing facility. For example, the total area of Samsung's Pyeongtaek campus is approximately 2.89 million square meters, or 31.1 million square feet. A single Samsung fab occupies about 120,000 square meters, or 1.29 million square feet. However, the key wording is important: '100 million square feet of manufacturing space' does not mean 100 million square feet of cleanroom space.

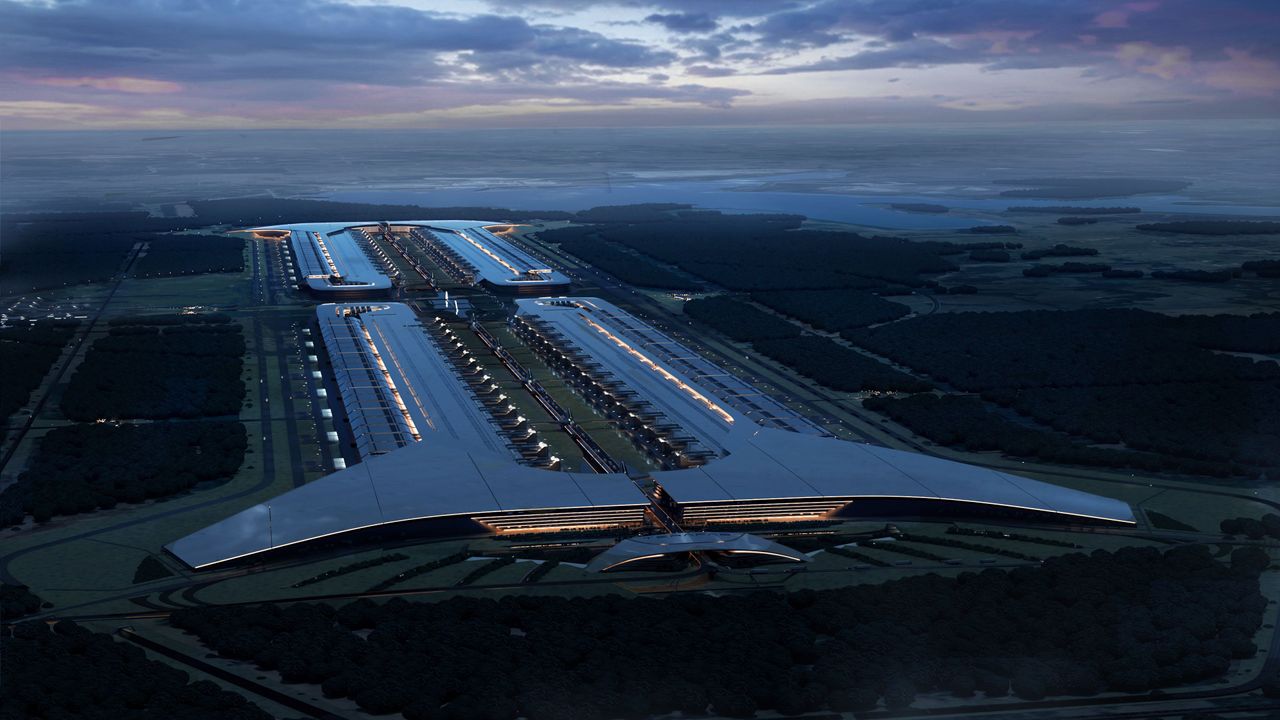
Based on an image published by SpaceX, the Terafab facility will occupy four massive buildings. It is unclear whether these buildings will be four phases of the project (i.e., logic, memory, and packaging will be made under one roof) or will serve different purposes (i.e., one building makes logic, another produces memory, yet another does testing and packaging). In any case, when fully built, Terafab will be a massive semiconductor production campus that will require significantly more than $16.8 billion.

The announcement claims that the Terafab facility will employ at least 3,000 people, and that between 60% and 80% of them will be Grimes and nearby Brazos County residents.

Terafab is expected to use water from Gibbons Creek Reservoir instead of local groundwater and feature on-site wastewater treatment as well as water recycling and conservation measures.

The announcement follows Tesla's groundbreaking earlier this year on a research semiconductor facility at the North Campus of Tesla's Giga Texas campus, which the companies describe as a precursor to Terafab.

  •  

Trump Issues Tariffs on Key Ingredient for Electronics and Solar Panels

The administration will impose a minimum import price for polysilicon, a key component for semiconductors and solar panels, as well as tariffs for products made with the material.

© Christian Monterrosa for The New York Times

A worker inspected solar panels at a factory in Dalton, Ga., in 2023.
  •  

Birds Are Dying. Clues Point to El Niño.

A die-off of seabirds has some experts thinking an El Niño weather pattern is to blame, a look at data centers and pollution, and more climate news.

© American Bird Conservancy

Seabird carcasses in Ecuador.
  •  

Satellite manufacturing thrives in California despite cost and regulatory pressures

California Gov. Gavin Newsom visited Vast Space headquarters in early June with Long Beach Mayor Rex Richardson. From left: Vast CEO Max Haot, Newsom, Vast chief operating officer Kris Young and Richardson. Credit: Vast Space

The mood was celebratory at the ribbon-cutting for Muon Space’s San Jose, California, manufacturing facility in June. State, local, United States Space Force and Pentagon representatives lauded the startup and, […]

The post Satellite manufacturing thrives in California despite cost and regulatory pressures appeared first on SpaceNews.

  •  

Scientists Develop New 3D Printing Method That Can Build Directly Onto Existing Objects in Seconds

Researchers have demonstrated an unusual new form of 3D printing capable of building entirely new structures directly onto—and even around—existing objects in just seconds. In a series of experiments, the technique printed microscopic fluid channels around embedded glass spheres, fabricated precision gears onto polished steel rods, and even built a miniature lens directly onto the surface of a working LED.

The breakthrough, described in a paper published in Nature Communications, relies on an advanced form of tomographic volumetric additive manufacturing (TVAM) that allows researchers to “overprint” new structures onto components made from a wide range of materials, including metal, glass, and preassembled microfluidic components. Instead of constructing objects layer by layer like conventional 3D printers, the system projects precisely calculated light patterns into a rotating vat of photosensitive resin, causing an entire three-dimensional object to solidify almost simultaneously within seconds.

The advancement could represent a major step toward making volumetric 3D printing practical in real-world manufacturing environments, where new components often must be integrated with parts that already exist.

It additionally highlights the growing sophistication of computational techniques that can accurately model how light behaves as it passes through materials that absorb, scatter, refract, or reflect light.

“Tomographic Volumetric Additive Manufacturing (TVAM) is a light-based 3D printing technique capable of producing centimeter-scale objects within seconds,” researchers write. “This work demonstrates a broad range of overprinting scenarios, where new structures are directly printed onto or around pre-existing components made from different materials.”

Unlike conventional stereolithography or fused-filament printers that gradually build an object from one direction, tomographic volumetric printing projects hundreds of two-dimensional light patterns into a rotating container filled with liquid resin.

As the resin accumulates enough light energy, the desired three-dimensional structure appears almost simultaneously throughout the volume rather than emerging layer by layer. The approach can produce centimeter-scale objects in mere seconds.

However, until now, one of the technology’s greatest challenges has been accurately calculating how light travels through complicated environments.

Existing objects inside the resin can block, scatter, or bend incoming light, degrading print quality. Conventional models often assume these objects are either completely transparent or completely opaque. This is an oversimplification that breaks down in realistic manufacturing scenarios.

To overcome those limitations, the team developed an upgraded computational framework called Dr.TVAM. Built upon physically based ray tracing, the software models how light propagates through materials with different optical properties while simultaneously optimizing the projected light patterns needed to create the desired object.

Because the framework accounts for reflection, refraction, scattering, absorption, and arbitrary container shapes, it can successfully print structures around components that previously would have interfered with the process.

One of the study’s most compelling demonstrations involved manufacturing microfluidic channels directly inside sealed, preassembled square chambers. Microfluidic devices contain microscopic channels that transport tiny volumes of liquids and are widely used in biomedical research, diagnostics, and organ-on-a-chip systems.

Instead of fabricating the channels separately and assembling the device afterward—a process that can introduce contamination or leaks—the researchers successfully printed perfusable channels directly inside an already assembled chamber while accounting for inlet and outlet structures that would otherwise obstruct the light.

They demonstrated straight channels, branching networks, and spiral geometries capable of carrying fluid after fabrication. Supplementary demonstrations showed colored dye successfully flowing through the finished structures.

The researchers then pushed the concept even further by creating what they describe as context-aware printing. In this experiment, they embedded two tiny glass spheres inside a hydrogel-filled chamber, rapidly determined each sphere’s three-dimensional position using two camera images, and generated customized print patterns in less than a minute.

Those optimized projections produced hollow channels connecting each sphere to inlet and outlet ports while simultaneously printing protective cavities around the spheres themselves. The complete workflow—from detecting the embedded objects to generating printing instructions and fabricating the final structure—required less than three minutes.

That ability could eventually enable highly customized biomedical manufacturing, where printers automatically adapt to the precise location of living tissues, organoids, or other biological materials rather than requiring perfect positioning beforehand.

Another experiment highlighted why precisely modeling light matters.

Previous demonstrations of volumetric overprinting treated metal components as though they completely absorbed incoming light. In reality, polished metal reflects and scatters significant amounts of light, creating distortions that reduce print quality.

Researchers tested both assumptions by printing a gear directly onto a polished steel rod. When the software ignored scattered light, the gear’s fine holes became over-polymerized and poorly defined.

After including realistic scattering behavior into the optical model, however, the resulting gear preserved those elaborate features far more accurately, increasing simulated print fidelity substantially. The improvement was confirmed experimentally.

Researchers even went as far as demonstrating that the process could print directly onto an electronic component.

Using an LED-based volumetric printing system, the researchers fabricated both a miniature lens and a small cross-shaped symbol directly onto the surface of a red LED. When illuminated, the printed lens projected the symbol onto a screen, successfully transforming the LED into a tiny optical projector without requiring additional assembly. The experiment showcased how optical elements themselves could potentially be integrated directly onto existing electronic hardware during manufacturing.

Beyond the individual demonstrations, the work additionally underscores an important trend in additive manufacturing: increasingly sophisticated software is becoming just as important as advances in hardware.

Instead of relying on simplified mathematical approximations, the new framework performs physically based optical simulations capable of modeling arbitrary geometries along with material properties.

The software has been released as open source, along with configuration files and experimental data, allowing other researchers to reproduce and expand upon the 3D printing work.

Although the current demonstrations remain laboratory-scale, the possible implications could extend well beyond experimental 3D printing. Biomedical researchers could eventually fabricate sterile microfluidic systems without multi-step assembly. Optical engineers may integrate lenses directly onto light sources. Manufacturers could add custom features to finished components without redesigning entire production processes.

Researchers also note that future improvements could further increase realism through incorporating additional physical effects, including changes in refractive index during polymerization and the diffusion of chemical inhibitors during printing. Those refinements could expand the technology’s accuracy and enable even more complex manufacturing scenarios.

“In summary, Dr.TVAM, our computational framework, has shown to be capable of modeling different optical situations for TVAM,” researchers write. “We believe this significantly expands the application space for TVAM, enabling the creation of complex, functionalized, and multi-component devices from applications in mechanics, optics, or biofabrication.”

Study: Wechsler F, et al. “Overprinting with tomographic volumetric additive manufacturing.” Nature Communications (2026).

Tim McMillan is a retired law enforcement executive, investigative reporter and co-founder of The Debrief. His writing typically focuses on defense, national security, the Intelligence Community and topics related to psychology. You can follow Tim on Twitter: @LtTimMcMillan.  Tim can be reached by email: tim@thedebrief.org or through encrypted email: LtTimMcMillan@protonmail.com 

  •  

Lumentum CEO warns of impending bottleneck on critical material used for silicon photonics — fab and material shortfall already lags 30% below customer needs as co-packaged optics demand skyrockets

Lumentum CEO Michael Hurlston told an audience at the RAISE Summit in Paris earlier this month that indium phosphide, the compound semiconductor behind every laser in an AI data center, is heading into a supply squeeze worse than what we've already seen with DRAM / NAND, and that Nvidia's decision to fund Lumentum and its biggest competitor at the same time was a response to exactly that.

In his remarks, Hurlston said that telecom customers bought lasers in the hundreds, while Nvidia and the hyperscalers are asking for hundreds of millions. While Lumentum runs five indium phosphide fabs, it's still shipping more than 30% below what customers want. Nvidia's answer, in March, was to write $2 billion checks to Lumentum and Coherent, the two suppliers that, between them, make most of the world's high-speed datacom lasers, with purchase commitments and future capacity access attached to both.

"Between the two of us, I don't think we can service the demand that Nvidia and others are now putting on us to solve this resistance problem in the data center," Hurlston added.

Silicon doesn't emit light

Indium phosphide has a direct bandgap of roughly 1.34 eV, which lets it convert electrical current into photons efficiently. Silicon's bandgap is indirect, so it can guide, split, and modulate light but can't generate it. Every silicon photonics platform in production, including those of Nvidia, Broadcom, Marvell, and Cisco, still needs an indium phosphide laser somewhere in the package to supply the light for silicon to manipulate. Moving from pluggable transceivers to co-packaged optics changes where that laser sits and how it's mounted, but it doesn't remove it from the bill of materials.

Nvidia's marketing claims its photonics switches use four times fewer lasers than an equivalent pluggable deployment, alongside 3.5 times better power efficiency and ten times better network resiliency, all of which are vendor figures. Those savings are per port, and it's that port count that's exploding.

The high-end Spectrum-X Photonics configuration runs 512 ports at 800 Gb/s for 400 Tb/s of switching, and Quantum-X Photonics InfiniBand runs 144 ports at 800 Gb/s. Co-packaging also shifts the laser type toward high-power continuous-wave sources and external laser modules that feed multiple channels, which are harder to build than the electro-absorption modulated lasers inside a conventional pluggable. Coherent's Nvidia agreement covers that category of high-power CW lasers, external laser source modules, and fiber array units.

Capacity at Lumentum and Coherent

Lumentum posted record revenue of $808.4 million in its fiscal third quarter, up 90% year over year, with components revenue of $533 million and pump laser shipments up 80%. On the May earnings call, Hurlston told analysts the company expects its supply line to increase 50% measured from one December quarter to the next, and in the same breath said the supply-demand imbalance on EMLs had widened from the 25% to 30% given a quarter earlier to "somewhere greater than 30%," with pump lasers tighter still. A supplier growing output by half a turn per year and losing ground anyway is a clean measure of how steep the demand curve is.

Coherent's 6-inch indium phosphide line yields more than four times as many devices as its 3-inch line at less than half the cost, CEO Jim Anderson told investors on the company's fiscal Q3 call. Anderson said EMLs, CW lasers, and photodiodes are all in production on the 6-inch line with yields above the legacy 3-inch lines, and that internal capacity would double by the end of the June quarter, one quarter ahead of plan, then more than double again by the end of 2027. Coherent's revenue hit a record $1.8 billion, up 21%, with data center and communications now 75% of the total against roughly 41% a year earlier, and backlog stretching into 2028.

Logic and memory moved to 300mm wafers in the early 2000s. Indium phosphide is a brittle, expensive, small-boule material where the industry-wide upgrade currently underway is 3-inch to 6-inch, roughly the transition silicon completed in the 1980s. Lumentum's fifth fab, announced in March, is a converted Qorvo gallium arsenide plant in Greensboro, North Carolina, described as 4-inch and 6-inch compatible and ramping around 2028.

Running through China

Indium is recovered as a byproduct of zinc refining, so its output can't be scaled independently of zinc economics, no matter how much laser demand there is. The USGS Mineral Commodity Summaries 2026 put China at an estimated 760 tonnes of roughly 1,100 tonnes of global primary refined indium in 2025, about 69%, and recorded a 72% year-over-year fall in unwrought indium exports between September 2024 and September 2025 after Beijing placed the metal under export controls in February last year. The U.S. warehouse price averaged about $390 per kilogram in 2025 against $340 in 2024.

AXT's Chinese subsidiary Tongmei had to obtain Ministry of Commerce export permits, granted in June and August 2025, before it could resume shipping indium phosphide substrates out of China. The fabs Nvidia is funding sit downstream of that licensing regime, and the wafers going into them aren't made in the United States in meaningful volume.

DRAM contract prices rose 90% to 95% quarter over quarter in Q1 2026, the largest quarterly increase TrendForce has recorded, and the firm forecast a further 58% to 63% in Q2 with NAND up 70% to 75%. HBM is sold out for 2026. Hurlston is measuring his warning against a genuinely historic crunch, which makes it a strong claim rather than a throwaway one, and he runs a company whose valuation depends on the shortage persisting.

LightCounting's April 2026 market forecast puts current transceiver demand about 30% above supply, matching Lumentum's own figure, but states that the shortages should be gone by the end of 2026 and cuts expected Ethernet transceiver growth to 65% for the year after 82% in 2025 and 93% in 2024. Coherent, hitting its capacity doubling a quarter early, points the same way. The distinction from memory is that the fix here is a wafer-size transition already running in production with yields ahead of the old node, not a new fab that takes three years to build.

  •  

Shanghai Aishengna named as the maker of China's first domestic immersion DUV chipmaking tools — first viable domestic 7nm-capable scanner to be completed by 2038

Reuters has named Shanghai Aishengna Electronic Technology Group as the state-owned company producing China's first domestic immersion deep ultraviolet lithography (DUV) scanners, a day after news of the program broke without identifying the manufacturer. Aishengna was established in August 2023 with RMB 7 billion, around $1 billion, in registered capital and is thought to have absorbed engineering teams from Shanghai Yuliangsheng Technology and Shanghai Micro Electronics Equipment.

Aishengna has been named by a single source who declined to be named, and its shareholders, SMEE and Yuliangsheng, didn’t respond to requests for comment. SMIC has been testing a Yuliangsheng immersion tool since September 2025, and first deliveries are slated for SMIC, Hua Hong Semiconductor, and ChangXin Memory Technologies.

Photoresist, coater tracks, and light sources

Tokyo Electron held an 89% share of the global coater/developer market in 2022, per Shared Research's analysis of the company's own disclosures, with its chief executive putting the figure near 90% and at 100% for EUV production. A scanner only exposes the wafer, however. It’s the track that's responsible for applying the resist film, baking it, and developing the pattern after exposure, and it has to be mechanically and thermally matched to the scanner in a single cluster, which is why the two are bought together. Shenyang Kingsemi has reached 28nm-class track capability and is currently targeting 14nm.

JSR, Tokyo Ohka Kogyo, Shin-Etsu, and Fujifilm hold a combined 72.5% of the ArF photoresist market, while Chinese suppliers hold under 1% of ArF immersion resist specifically. Nata Opto-electronic built a 25-ton ArF line, later expanded to 50 tons, passed customer qualification in December 2020, and completed project acceptance in 2024 with little volume to show for it. Xuzhou B&C says its ArF immersion products cover 45nm to 28nm and can stretch to 14nm, and chairman Fu Zhiwei has put mass production of China's core advanced resists five years out.

Cymer, Gigaphoton, and Coherent hold more than 80% of the ArF excimer laser market between them, and Cymer has been an ASML subsidiary since 2013. Beijing RSLaser shipped China's first high-power domestic excimer laser in 2018 under the national Project 02 program and has a 4 kHz 193nm ArF prototype aimed at 90nm and 65nm-class tools, generations behind what 28nm immersion requires.

Carl Zeiss SMT has been ASML's sole projection optics supplier since 1983, and Zeiss SMT revenue grew from €1.2 billion in 2016 to €4.1 billion in 2024. It’s not currently known what, if any, Japanese tooling is inside the Aishengna machines, but excimer sources and precision optics are areas where Chinese substitution is believed to be lacking.

CXMT

CXMT is projected to reach around 350,000 wafer starts per month by the end of 2026, roughly 25,000 short of Micron, up from 40,000 in 2020. DRAM scaling at 1a and 1b-class nodes runs on immersion multipatterning because CXMT has no EUV access, which makes any potential ramp lithography-gated rather than cleanroom-gated. DRAM contract prices rose 93% to 98% quarter on quarter in Q1 2026, and TrendForce projected a further 58% to 63% in Q2, lifting DRAM industry revenue 81% to $97 billion. A domestic immersion source is therefore worth having to CXMT, even at inferior overlay and throughput.

A DUV-only 7nm flow needs roughly 19 spacer-defined multipatterning masks from the front end through the second metal layer, against about 10 for an EUV-based N7+ process, by one published comparison of SMIC's process. SemiAnalysis has put SMIC's 7nm defect density near 0.14, around double TSMC's N5 and N6. ASML CEO Christophe Fouquet told analysts during the company's July earnings call that rising DRAM lithography intensity partly reflects "the increased replacement of multi-patterning with more cost-effective single-exposure EUV." As such, every exposure China adds to compensate for the missing EUV burns scanner hours a thin domestic fleet doesn't have.

The MATCH Act

China fell to about 14% of ASML's sales in Q2 2026 from 33% across 2025, and installed base management, the service and upgrade business, brought in €2.8 billion of ASML's €9.3 billion in second-quarter revenue. H.R. 8170 would ban both the export and the servicing of immersion DUV systems to any destination in China and designate SMIC, Hua Hong, Huawei, CXMT, and YMTC as restricted entities by statute. Former ASML chief executive Peter Wennink has said the company can service most Chinese tools, but not with spare parts of U.S. origin that fall under export control, which is the mechanism that the MATCH Act would widen.

The bill remains in committee after clearing the House Foreign Affairs Committee in April, with a Senate companion filed as S. 4281, and no floor vote yet scheduled. Its 150-day allied-alignment clause would also reach Nikon, which sold 11 ArF immersion systems in FY2024 and none in the first three quarters of FY2025, and which plans to deliver a new immersion prototype to a major chipmaker by 2027. ASML expects about 130 immersion shipments this year and intends to raise immersion capacity 30% in 2027, with a further 30% under investigation for 2028.

As for Chinese providers, SMEE prototyped its SSA600 ArF tool in 2011 and never reached sustained commercial sales, and a late-2023 shareholder claim that the company had developed a 28nm machine was subsequently retracted. SiCarrier showed etch, CVD, PVD, and ALD tools at SEMICON China 2025 without a lithography system, and a December 2025 government contract reported as a lithography award turned out to cover a KrF tool at 110nm. We’ve previously assessed that China’s toolmakers are more than a decade behind the market leaders.

The AI Futures Project's June forecast puts a commercially viable domestic 7nm-capable immersion scanner between 2032 and 2038, with a median of 2035, and claims ASML holds 98.7% of the immersion market today. Five machines in 2026 would be under 4% of ASML's annual immersion output, and each would still need a coater track, a qualified ArF immersion resist, and an excimer source to print a single wafer; China leads in none of those three.

  •  

Fortastra and Hadrian join forces to streamline satellite production

SAN FRANCISCO – Fortastra, a Los Angeles startup focused on defending on-orbit infrastructure, is working with manufacturing specialist Hadrian to explore ways to apply precision machining and additive manufacturing to […]

The post Fortastra and Hadrian join forces to streamline satellite production appeared first on SpaceNews.

  •  

Varta Crisis Deepens After Apple Battery Defection

The Varta crisis has entered another severe phase after the German battery manufacturer lost the customer responsible for nearly all production at its specialized factory in Nördlingen.

Varta has not publicly identified that customer, but reports from German media and industry sources point to Apple. The iPhone maker is reportedly moving battery orders for a future AirPods generation to a lower-cost supplier in China.

The decision will lead Varta to stop producing rechargeable button cells in Nördlingen during fall 2026. Approximately 350 jobs will be eliminated across the factory and the company headquarters in nearby Ellwangen.

Describing the development as a complete corporate collapse would go too far. Varta continues operating other battery businesses and recently completed an extensive financial restructuring backed by Porsche. The loss of Apple, however, has destroyed the economic foundation of a production site created around one highly influential customer.

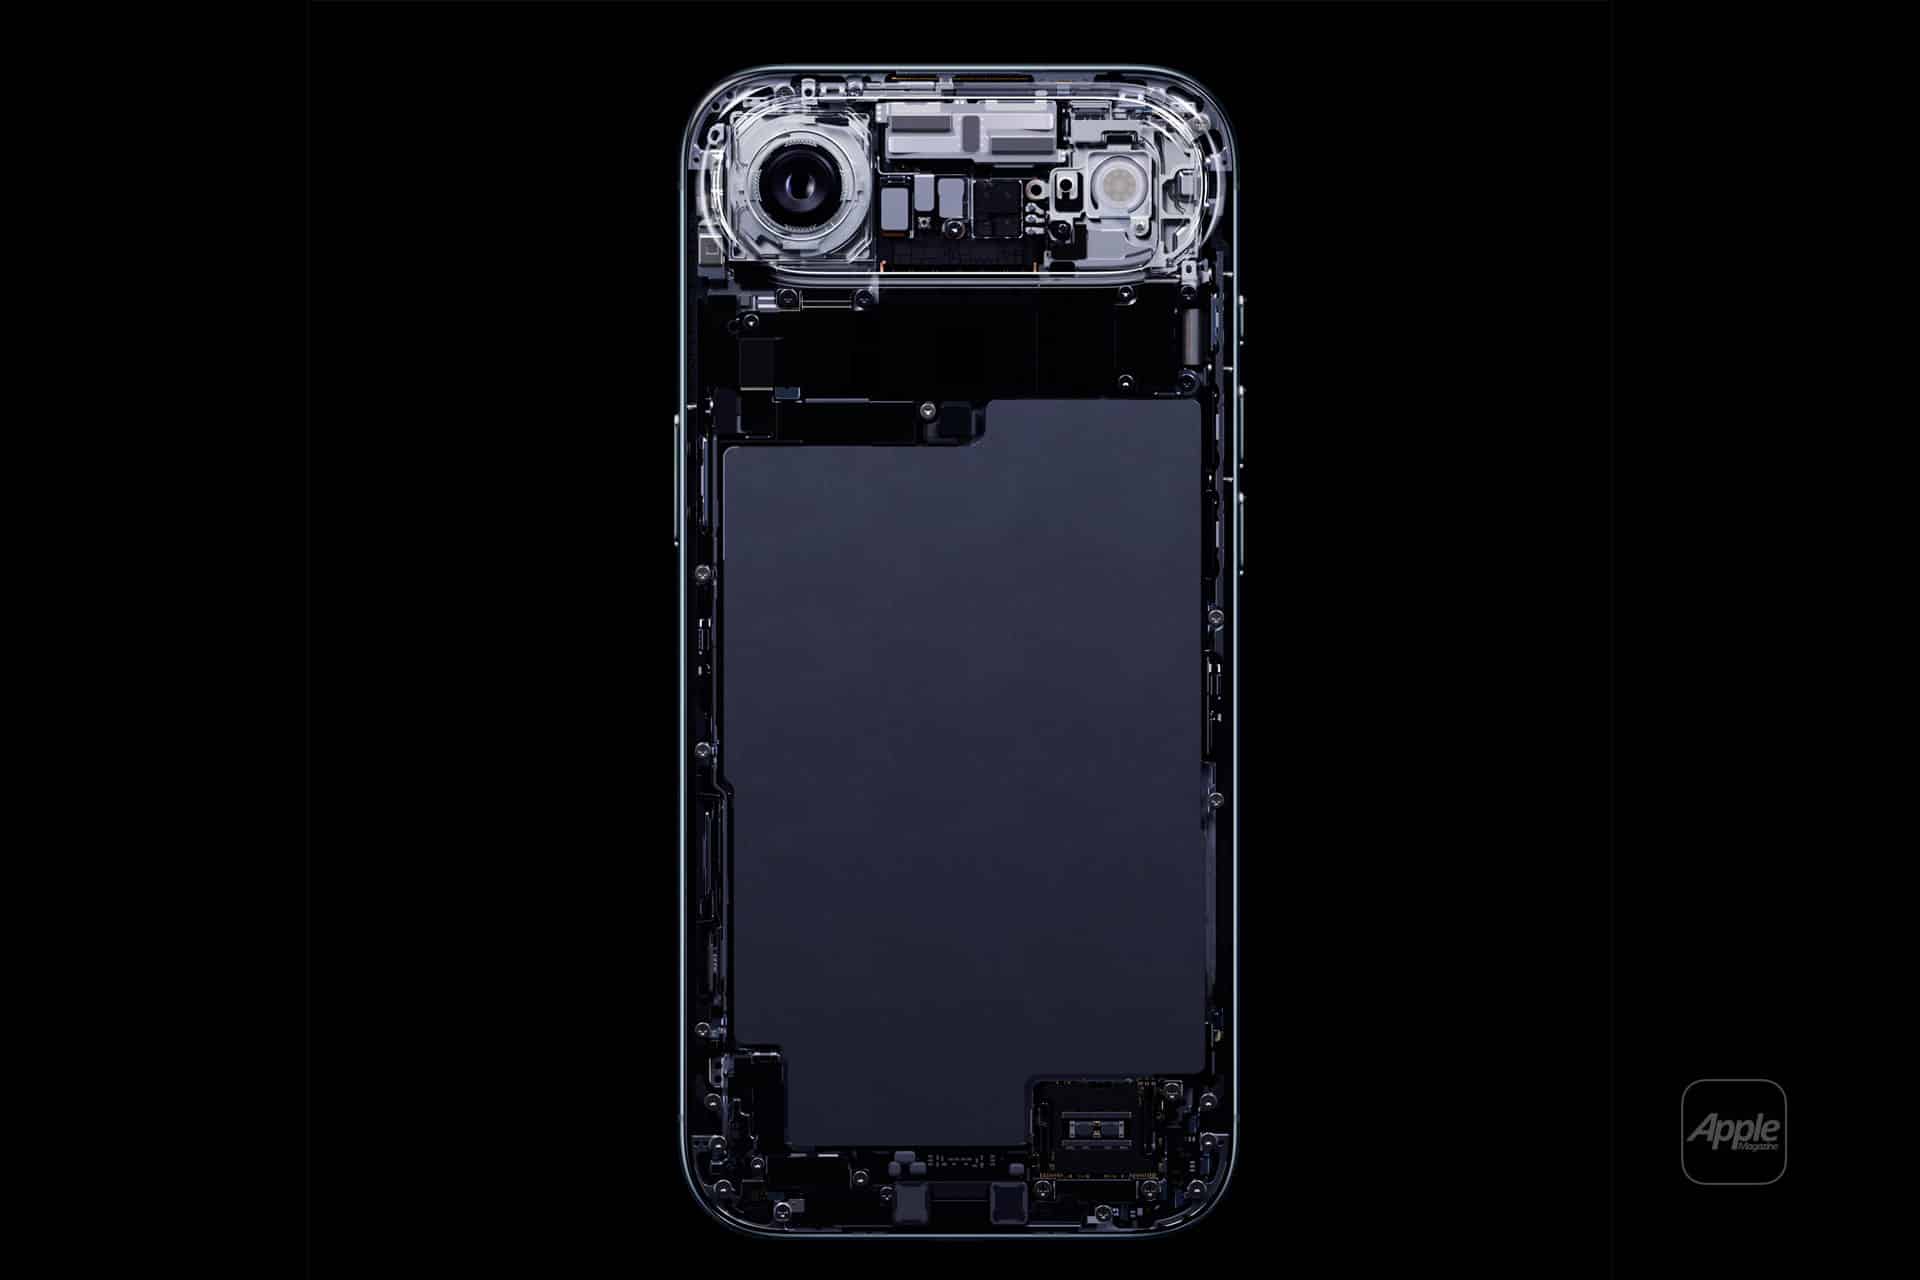
A smartphone with a transparent back, revealing internal components like the battery, camera, and circuitry—crafted with Apple 3D printing—displayed on a black background with a small Apple logo in the lower right corner.

Varta Crisis Exposes Dependence on Apple

The Varta crisis illustrates how a large technology customer can transform a supplier and then leave it with capacity that cannot easily be reassigned.

Varta became an important producer of CoinPower lithium-ion cells, small rechargeable batteries designed for wireless earbuds and other compact devices. Teardowns of AirPods Pro models identified Varta cells inside the earbuds, although Apple does not publicly discuss most component suppliers by product.

Demand from premium wireless headphones helped Varta expand rapidly. In 2020, its Microbatteries and Solutions division generated approximately €508 million in revenue, representing growth of 49% from the previous year.

The company invested heavily in production as wireless earbuds became a mass-market category. Apple demand provided the volume needed to justify specialized lines, equipment and hiring in Germany.

That dependence became dangerous when AirPods production weakened and Apple began adding other battery suppliers. A factory developed for unusually large orders could not operate efficiently once those orders declined.

The customer now leaving Nördlingen had previously accounted for nearly the entire capacity of the site. Varta says it has gained other customers, but their combined demand is not sufficient to keep the specialized factory running.

The plant is therefore closing not because rechargeable button cells have disappeared, but because replacing one customer of Apple scale requires far more than several smaller contracts.

Price Reportedly Decided the AirPods Order

German reports indicate that price was the decisive factor behind the supplier change.

Varta battery quality was reportedly equal to or better than the competing product. The German manufacturer could not, however, match the cost offered for the next generation of cells from China.

Battery production in Germany faces higher labor, energy and operating expenses than many Asian manufacturing centers. Chinese suppliers also benefit from extensive domestic electronics supply chains, access to materials and production volumes spread across numerous customers.

Apple has enormous leverage when negotiating component contracts. AirPods ship in sufficient quantities for a small difference in the cost of each battery to produce substantial savings across an entire product cycle.

The company regularly qualifies multiple suppliers for components when technical requirements and available capacity permit. Competition can reduce prices, protect production against interruptions and prevent one manufacturer from gaining excessive influence over the supply chain.

For Varta, that process brought the opposite effect. The supplier expanded to serve Apple and then faced declining utilization as the customer divided orders among additional manufacturers.

The latest move appears more final. Varta expects the contract to expire at the end of October, removing the volume that kept Nördlingen economically viable.

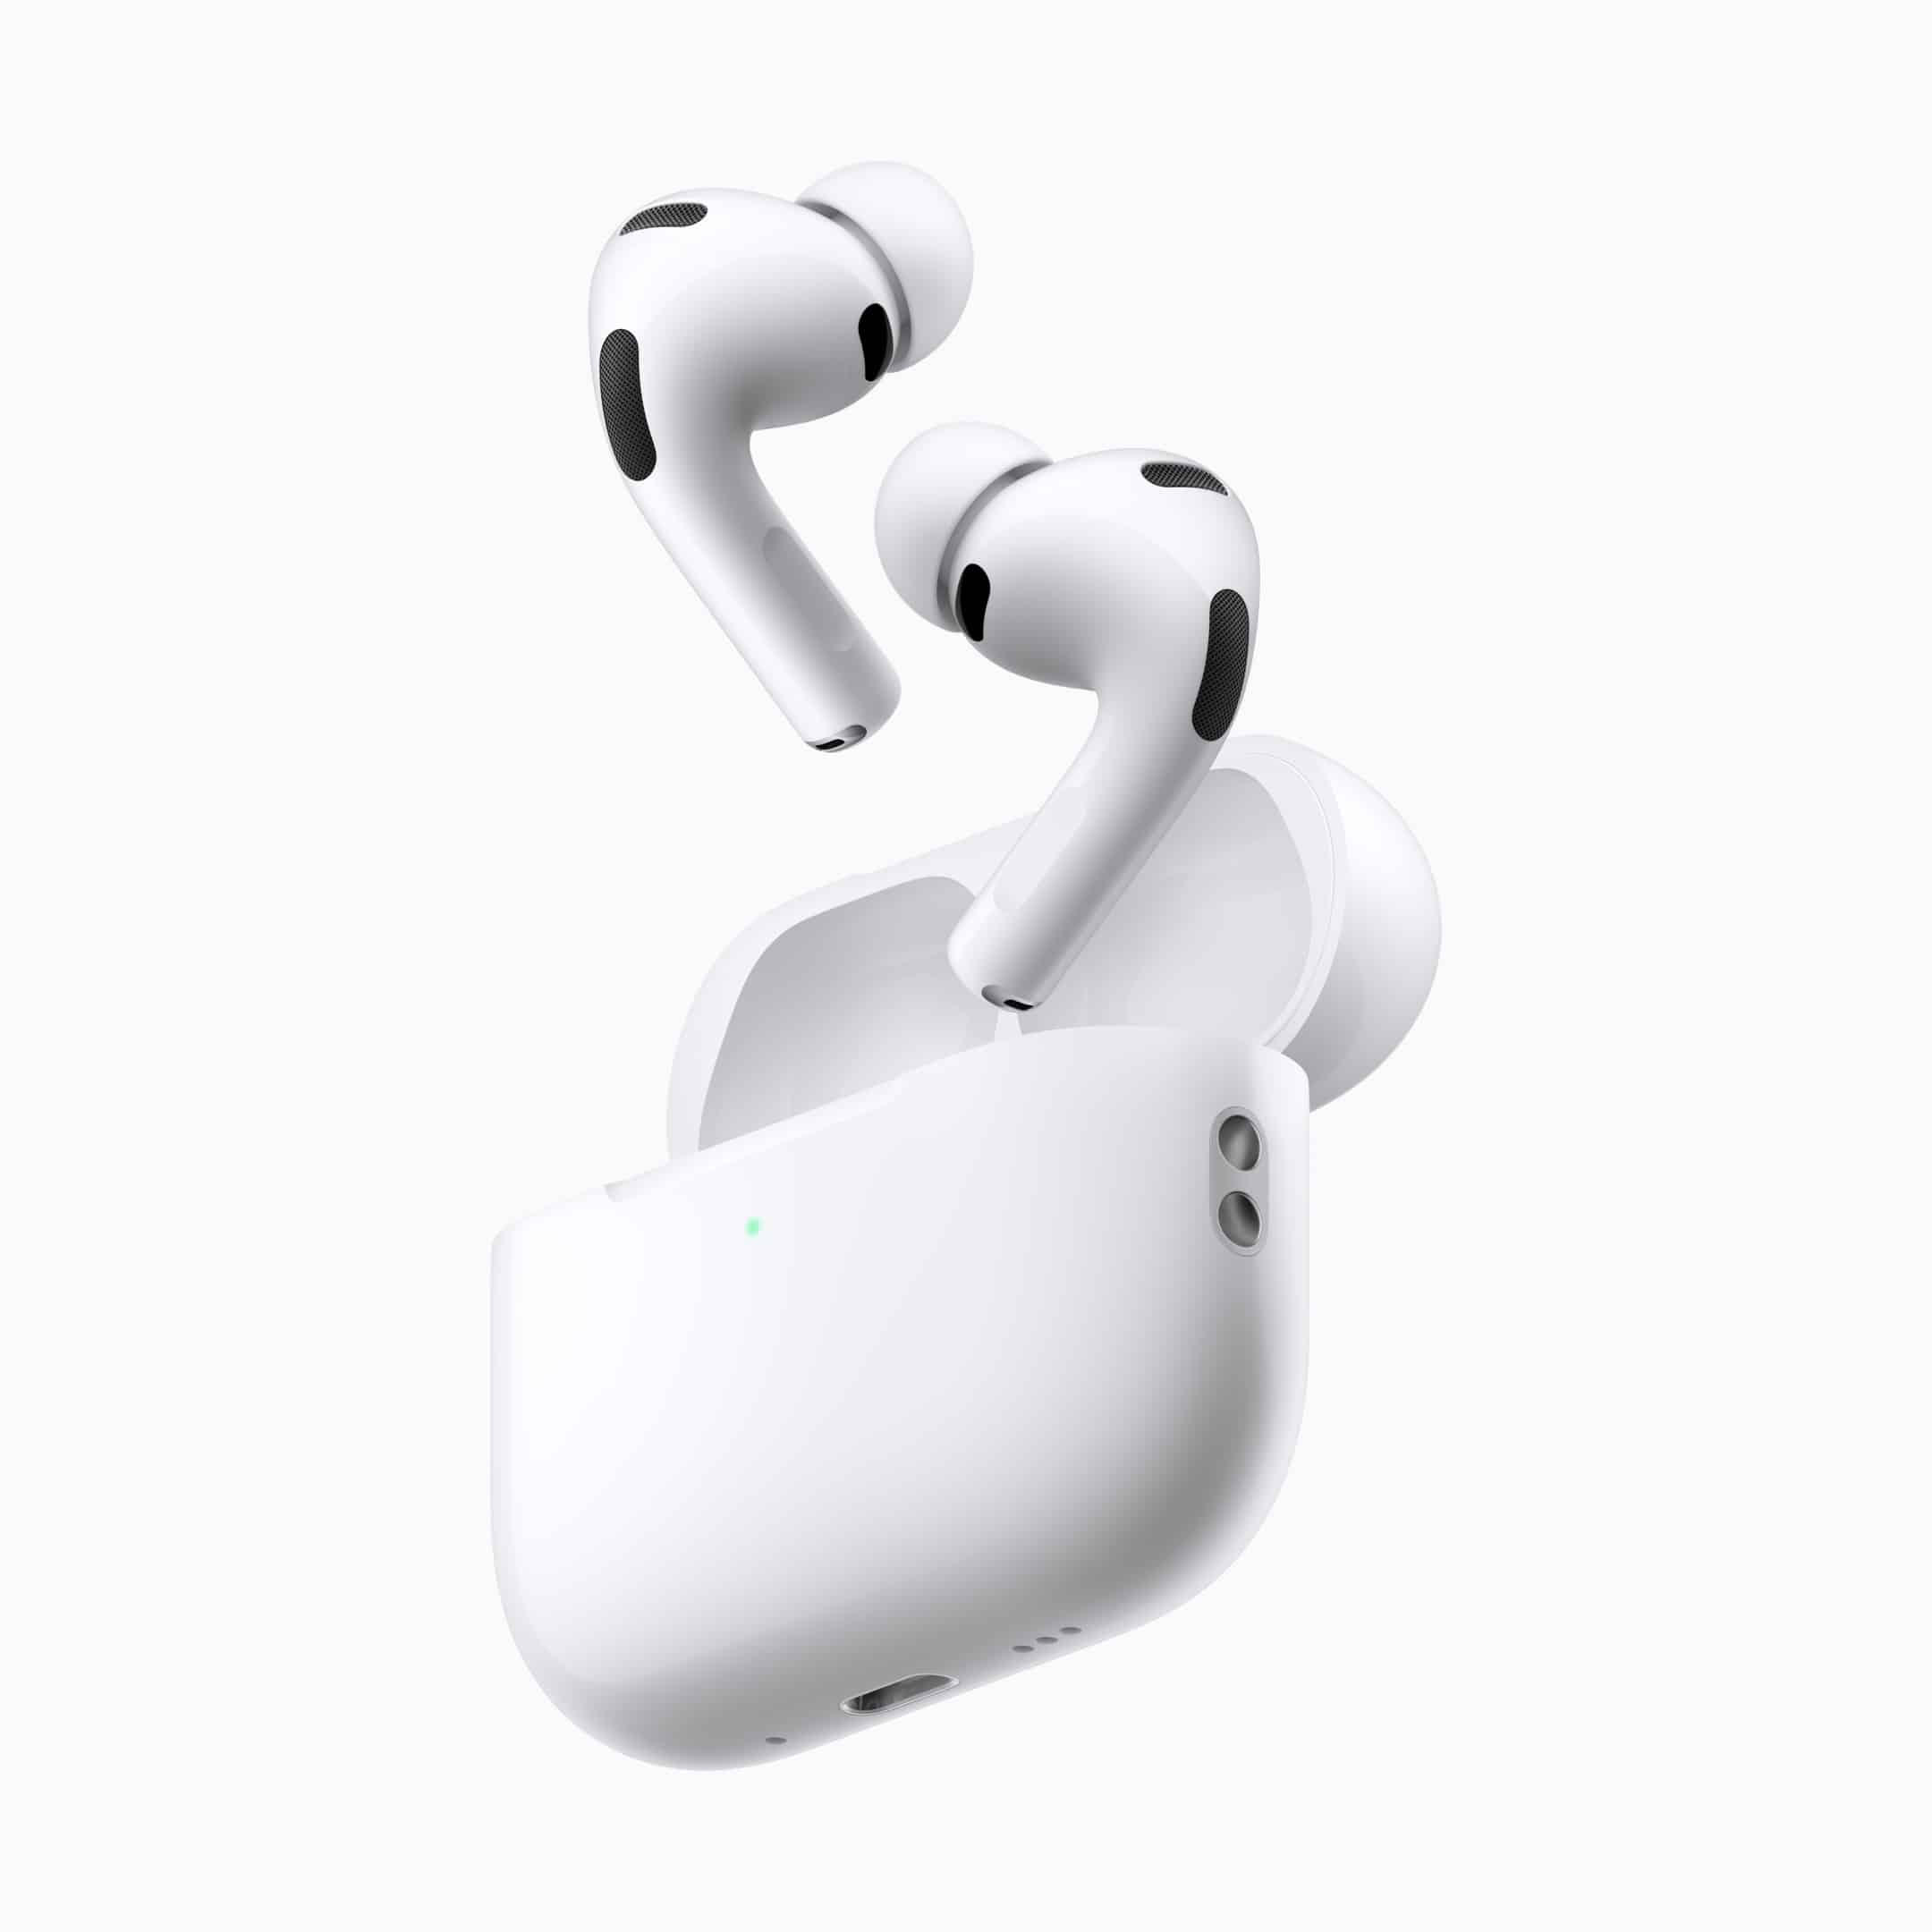
A pair of white AirPods Pro 3 wireless earbuds with black accents are shown above an open white charging case, all set against a plain white background—perfect for seamless audio and features like live language translation from Apple.
Image Credit: Apple Inc.

Apple Supplier Strategy Is Not Simply About China

The reported decision does not mean Apple is moving its complete production network toward China.

Apple has spent several years expanding device assembly and component production in India, Vietnam and other countries. AirPods manufacturing has grown in India, while Macs, iPads and wearables are assembled across a wider group of Asian locations.

The Varta case concerns a particular component for which a Chinese supplier reportedly offered a more competitive price. It shows that diversification away from one country can coexist with cost-driven sourcing from that same country.

Apple may reduce its dependence on Chinese final assembly while continuing to purchase Chinese batteries, displays, enclosures or electronic components when suppliers provide the required scale and pricing.

That balance creates a difficult environment for European manufacturers. Political interest in domestic technology production does not guarantee that major customers will accept higher component prices.

Premium engineering can protect a contract when it produces a measurable advantage in battery capacity, safety, dimensions or lifespan. Once competing suppliers reach comparable performance, procurement decisions become increasingly sensitive to cost.

The Varta crisis suggests that manufacturing location and supplier history carried less weight than the economics of the next AirPods battery.

Varta Was Already Fighting Financial Failure

Apple did not create every problem affecting Varta.

The company entered the current dispute after years of debt, costly investments, volatile customer orders, supply-chain problems and weaker demand in parts of its energy-storage business. A cyberattack in early 2024 also disrupted production and delayed financial reporting.

Varta warned that its earlier restructuring plan might fail after Apple reduced AirPods production. By mid-2024, the company had reached a point where it could no longer service its debt without another intervention.

A pre-insolvency restructuring reduced financial liabilities from approximately €485 million to €200 million. Porsche and majority shareholder Michael Tojner agreed to provide new capital, while creditors supplied additional financing.

Existing shareholders lost their investment as Varta was removed from the stock market. The process preserved the operating company but demonstrated how little financial room remained for another major disruption.

Varta reported a loss of €64.5 million for 2024. Although that was an improvement from the previous year, the business remained dependent on successful restructuring and stronger performance from its surviving divisions.

The Apple contract loss therefore did not independently bring down a healthy battery group. It struck a manufacturer that had already narrowly avoided insolvency.

Aerial view of a large industrial complex—possibly one of the key Apple suppliers—surrounded by trees, parking lots with cars, and several buildings. There are roads and green fields nearby, with a small round building in the lower right corner, perhaps connected to the facility's production or storage of CoinPower cells amid the recent Varta crisis.
Image Credit: Wikipedia

Porsche Cannot Protect Every Varta Business

Porsche participation gives Varta a future in automotive batteries, but it does not rescue the Nördlingen button-cell operation.

The automaker invested in the restructuring and took control of the V4Drive business, which develops high-performance cylindrical lithium-ion cells for hybrid and performance vehicles. Porsche gains greater access to battery technology while helping retain part of that expertise in Germany.

Varta also continues producing household batteries and energy-storage systems. Those businesses serve different customers and do not depend on the machinery used for tiny CoinPower cells.

Employees affected by the Nördlingen closure may be offered positions at other locations, although Varta has not indicated how many can realistically be transferred. The company and its works council are negotiating measures for the workers whose roles will disappear.

The shutdown leaves a modern production unit without enough demand only a few years after wireless earbuds were presented as one of Varta most promising growth markets.

Its remaining automotive operation now has the security of a strategic customer with a direct ownership interest. The microbattery division learned the cost of building a factory around a customer that never made the same commitment.

The post Varta Crisis Deepens After Apple Battery Defection appeared first on AppleMagazine.

  •  

The U.S. Is Pulling Back on Energy Efficiency

The Trump administration is undoing fuel-saving efforts even as war in Iran, data centers and heat waves are pushing up gasoline and electricity costs.

© Michael Hickey/Getty Images

A dishwasher at a General Electric plant in Louisville, Ky. The Energy Department has moved to repeal 17 standards for dishwashers, washing machines, kitchen appliances and more.
  •  

Trump admin secures record $265 billion TSMC investment in U.S. semiconductor manufacturing, adding 4 new facilities for total of 12

TSMC

In a major boost to American domestic manufacturing, the Trump Administration today announced that Taiwan Semiconductor Manufacturing Company (TSMC) is committing an additional $100 billion in investments for advanced semiconductor facilities in the United States. This brings TSMC’s total planned investment to $265 billion — one of the largest foreign direct investments in American history.

The announcement, made jointly by the White House and the Department of Commerce, highlights the success of strategic trade and investment partnerships, particularly the historic U.S.-Taiwan deal signed in January 2026. As a direct result, TSMC will build four additional advanced semiconductor manufacturing and packaging facilities, bringing its U.S. footprint to 12 leading-edge facilities, primarily in Arizona.

Building on Momentum

This latest expansion builds on previous commitments. TSMC’s original plans started at around $65 billion, which were later increased. The new infusion underscores sustained momentum under the current administration’s focus on reshoring critical supply chains.

In a statement, U.S. Commerce Secretary Howard Lutnick emphasized the job-creating impact, “President Trump’s leadership is driving companies to invest in American manufacturing. TSMC’s announcement of an additional $100 billion investment following our historic deal on trade and investment with Taiwan will create tens of thousands of American jobs and bring advanced semiconductor manufacturing back to America.”

TSMC Chairman and CEO Dr. C.C. Wei echoed the sentiment, crediting collaboration with the administration and strong U.S. customer demand, “We appreciate the strong collaboration and support of the Trump Administration, Secretary Lutnick and our leading U.S. customers… This is to support the strong multi-year demand from our leading U.S. customers, and we believe this investment will further foster the development of the U.S. semiconductor ecosystem, strengthen the supply chain, and support significant job creation in the United States.”

Economic and Strategic Impact

The investments are expected to generate significant construction and high-tech jobs, along with billions in indirect economic output. Beyond direct facilities, the broader U.S.-Taiwan trade and investment framework is catalyzing an additional $500 billion in Taiwanese investments — $250 billion in direct semiconductor and related enterprises, plus another $250 billion to strengthen the full supply chain in the U.S.

This move addresses long-standing concerns about reliance on overseas production for advanced chips, especially those critical for AI, defense, automotive, and consumer electronics. By expanding domestic capacity with a world-leading foundry like TSMC, the U.S. strengthens its position in the global semiconductor race while creating high-paying opportunities for American workers.

The Trump Administration’s approach, which combines diplomatic deals, incentives for onshoring, and a focus on national security, continues to yield concrete results in rebuilding America’s industrial base.
‎
MacDailyNews Take: With 12 state-of-the-art facilities on track, America is poised to capture a much larger share of advanced chip production. This not only bolsters economic competitiveness, but also enhances supply chain resilience against geopolitical risks.


‎
Please help support MacDailyNews — and enjoy subscriber-only articles, comments, chat, and more — by subscribing to our Substack: macdailynews.substack.com. Thank you!

Support MacDailyNews at no extra cost to you by using this link to shop at Amazon.

The post Trump admin secures record $265 billion TSMC investment in U.S. semiconductor manufacturing, adding 4 new facilities for total of 12 appeared first on MacDailyNews.

  •  

Advanced Recycling Hits a Rough Patch

In the past weeks, two sites in the United States have halted operations.

© Maddie McGarvey for The New York Times

Unlike traditional mechanical recycling, advanced recycling can theoretically process mixed or contaminated plastics that otherwise would end up in landfills.
  •  

In Europe, Tesla Sales Are Rising Despite Views on Elon Musk

Price cuts and low-interest-rate loans are luring buyers, including people offended by the company’s chief executive.

© Michael Nguyen/NurPhoto, via Associated Press

A Tesla Supercharger station in Germany. Tesla’s sales have rebounded sharply in Europe alongside sales of all electric cars.
  •  
❌