❌

Reading view

Apple Presses for 20% Cut in iPhone 18 OLED Panel Prices on 'Chipflation'
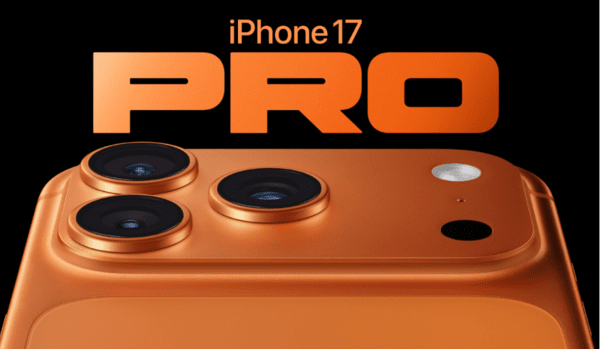
Apple's iPhone 17 Pro. (Photo: Apple)

Apple is strongly demanding lower display panel prices as rising memory semiconductor prices push up the cost of building iPhones.

According to industry sources on July 24, Apple has proposed a price of about $70 for organic light-emitting diode (OLED) panels for the iPhone 18 Pro Max, which it will unveil this year. The industry estimates that Samsung Display and LG Display are supplying the panels at an average of $66.5, even lower than that figure. That is about 20% below the previous model.

iPhone OLED prices have fallen with each new product in the past as well. Depending on supply timing and conditions, iPhone 16 Pro Max panels at times exceeded $100, but fell to the $80 range for the iPhone 17 Pro Max. Panels for the iPhone 18 Pro Max are about 20% lower than that. On top of the usual generational price decline, the size of the reduction has grown this time, according to industry officials.

Notably, the OLED panels for the iPhone 18 will use M16, the latest organic material set, which improves luminous efficiency, lifespan and color characteristics. Panel makers must adjust process conditions and stabilize yields to suit the new material. Product specifications and production difficulty have risen, yet prices have instead fallen.

Rising memory semiconductor prices have worked as a negative factor, as smartphone makers seek to absorb the cost increase by cutting procurement costs for other components such as displays and camera modules.

Samsung Display President Lee Cheong said on July 22 at K-Display 2026 that "this year is extremely difficult because of chipflation," adding that "very strong pressure is coming in to lower component and display prices." LG Display President Jeong Cheol-dong also said of the pressure to cut prices that the company is "being affected to some degree," but that it is "at a manageable level because we are pursuing cost innovation."

According to market research firm UBI Research, Samsung Display is expected to supply 46 million OLED panels for the bar-type iPhone 18 this year, comprising 2 million for the standard model, 18 million for the Pro and 26 million for the Pro Max. LG Display's expected volume is 41.09 million panels, made up of 1.09 million for the standard model, 19 million for the Pro and 21 million for the Pro Max.

"Apple is demanding steep price cuts from panel suppliers on the grounds of rising memory prices," an industry official said. "Supply prices are falling even for high-specification products using the latest organic materials, so panel makers' second-half earnings will vary depending on supply volumes, yields and the extent of cost reductions."
  •  

Low-Res Flexible OLED Adoption Rises Amid "Chipflation"

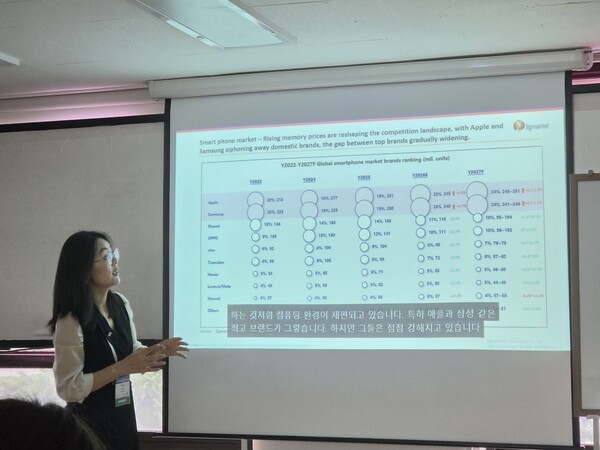
Lisa Lee, CEO of Sigmaintell, speaks during a media briefing held in Gangnam-gu, Seoul, on July 23. (Photo: THE ELEC)

Smartphone makers are expected to expand the use of lower-resolution flexible organic light-emitting diode (OLED) panels in mid- and low-end models as memory prices rise. Rather than reducing OLED adoption, companies are seeking to lower cost pressure by adjusting specifications for components such as memory capacity and display resolution.

Lisa Lee, chief executive officer of market research firm Sigmaintell, said during a media briefing held at the Fastfive shared office in Gangnam-gu, Seoul, on July 23 that "smartphone brands are considering applying flexible OLED displays with slightly lower resolutions to low-end markets." She added that "device makers are looking for ways to reduce costs by combining different specifications."

Smartphone manufacturers are asking component suppliers, including panel and camera makers, to lower prices in order to offset rising memory costs. They are also reviewing adjustments to product configurations, including system-on-chip (SoC) specifications, memory capacity and display resolution.

Sigmaintell said SoCs account for a larger share of smartphone component costs than panels and cameras, meaning manufacturers are likely to restructure the overall cost structure of products rather than seek price reductions from individual components alone. The company said product strategies may differ by segment, with mid- and low-end devices reducing memory capacity or screen resolution while premium models maintain existing specifications.

"Panels and cameras are less expensive than SoCs, limiting the potential for cost reductions," Lee said. "Brand companies are looking for ways to lower costs not only in panels and cameras but also across other components."

Smartphone makers are seeking to maintain OLED adoption partly to reduce the burden on consumers caused by higher prices. Keeping existing specifications unchanged could significantly increase manufacturing costs for budget smartphones, making price increases unavoidable.

Instead of raising prices alone, manufacturers are expected to maintain product competitiveness by offering features that consumers can directly perceive, such as OLED displays. "Even if prices increase, companies will likely provide new features along with the higher price," Lee said. "Applying OLED to new products is one possible approach."

Flexible OLED panels use bendable substrates instead of glass. They have traditionally been used mainly in premium smartphones, but their adoption has expanded into mid-range and budget devices as Chinese panel manufacturers increase supply and panel prices decline.

The smartphone market is expected to contract again next year. Sigmaintell forecasts global smartphone shipments will decline 3.3% to 1.0264 billion units next year from 1.0614 billion units this year. If rising memory prices and weakening demand for budget smartphones intensify, shipments could fall further to 975 million units.

The decline in smartphone demand is expected to continue through the first quarter of next year, with the pace of contraction slowing from the second quarter. The Chinese market is expected to experience a larger decline than the global market due to its higher share of low-end smartphones.

The memory shortage is being driven by rising demand for artificial intelligence (AI) servers. Sigmaintell said consumer memory supply is being reduced as demand for DRAM and high-bandwidth memory (HBM) used in AI servers increases.

Rising memory prices are also expected to affect smartphone shipments by manufacturer. Sigmaintell expects Apple and Samsung Electronics to maintain or expand their market shares due to stable component supply chains, while Chinese smartphone makers with higher exposure to mid- and low-end products will face greater pressure from rising costs.

However, the decline in smartphone sales is not expected to immediately translate into lower demand for OLED panels. Smartphone makers continue to transition products from liquid crystal displays (LCDs) to OLEDs, while adoption of lower-specification flexible OLED panels could increase in mid- and low-end models.

"Even if the overall smartphone market shrinks, the share of flexible OLEDs will continue to expand," Lee said. "In particular, we expect penetration of low-cost flexible OLED products to increase."

  •  

Display Industry Calls for Government Support to Foster Inorganic Light-Emitting Display Sector

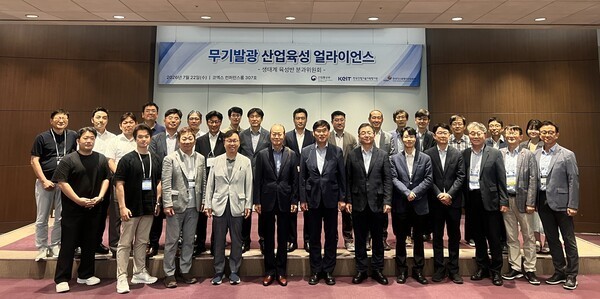
Representatives from 21 member companies pose for a group photo during the 2026 Regular Meeting of the Inorganic Light-Emitting Display Subcommittee at COEX in Seoul on July 22. (Photo: Korea Display Industry Association)

South Korea's display industry has begun formulating policy recommendations to accelerate development of the inorganic light-emitting display industry, including microLED technologies. The proposals will be submitted to the government in October.

The Korea Display Industry Association (KDIA) announced on July 22 that it held the 2026 Regular Meeting of the Inorganic Light-Emitting Display Subcommittee at COEX in Seoul.

The meeting brought together 21 companies spanning materials, components, equipment, panel manufacturing and finished products, including subcommittee chair Seoul Viosys. Participants discussed policy measures needed to expand the market for inorganic light-emitting displays and strengthen the industry's global competitiveness.

Inorganic light-emitting displays use inorganic materials as light-emitting devices and encompass technologies such as microLED, quantum dot (QD) and nanoLED displays. Compared with organic light-emitting diode (OLED) displays, they offer longer operating life and higher brightness. However, commercialization has progressed slowly because of high production costs and the lack of standardized manufacturing technologies.

The South Korean government has operated the Inorganic Light-Emitting Industry Alliance since 2023. In April 2024, it launched the industry subcommittee to collect feedback and address challenges facing companies in the sector.

During the meeting, participants identified industry needs in four key areas: infrastructure and standards, technology development, tax incentives and policy support, and workforce development. They also emphasized the need for government measures to encourage private-sector investment and research and development.

KDIA said it will consolidate the industry's recommendations and submit them as policy proposals at the next meeting of the Inorganic Light-Emitting Industry Alliance, scheduled for October.

In 2025, the government launched a 484 billion won initiative to build an ecosystem for inorganic light-emitting displays. The program aims to strengthen domestic capabilities in core technologies while developing supply chains for materials, components and manufacturing equipment.

Overseas, Taiwan's AUO launched a microLED smartwatch with Garmin in 2025, while Chinese display manufacturers are also expanding production capacity for the technology.

"Inorganic light-emitting displays are a future growth engine that South Korea must secure to maintain its leadership as an unrivaled display powerhouse," said Lee Seung-woo, executive vice president of the Korea Display Industry Association. "The association will serve as a central platform to help the government and industry work together as one team and turn that vision into tangible results."

  •  

LG Display Posts 107.7 Billion Won Operating Loss in Q2, Returns to First-Half Profit

LG Display returned to a cumulative operating profit in the first half despite seasonal weakness and one-off costs related to workforce optimization. (Photo: THE ELEC)

LG Display returned to a cumulative operating profit in the first half of the year despite the seasonal slowdown in demand and one-off costs related to workforce optimization.

The company said on July 22 that it posted revenue of 5.6121 trillion won and an operating loss of 107.7 billion won for the second quarter.

Revenue rose 0.4% from 5.587 trillion won a year earlier. The operating loss narrowed by 8.4 billion won from 116.1 billion won in the second quarter of 2025.

For the first half of the year, LG Display reported cumulative revenue of 11.1461 trillion won and an operating profit of 39.0 billion won. Compared with revenue of 11.6523 trillion won and an operating loss of 82.6 billion won in the same period of 2025, revenue declined 4.3%, while the company returned to profitability. First-half earnings improved by 121.6 billion won year over year.

The first half is typically a seasonally weak period for the display industry as device manufacturers adjust component inventories ahead of new product launches in the second half of the year. The second quarter also included one-off costs related to workforce optimization.

LG Display said it maintained first-half profitability by further strengthening its OLED-centered business structure despite seasonal weakness and one-time expenses. Excluding those one-off factors, the company's core business also remained profitable during the second quarter.

In the second half, LG Display plans to strengthen its competitiveness through technology-driven cost innovation. Beyond simple cost reductions, the company will improve efficiency across development, manufacturing and production by accelerating its AI transformation (AX), further enhancing its business fundamentals.

In its small- and medium-sized display business, LG Display will focus on differentiated technologies to strengthen competitiveness in the high-end segment. The company said its stable technology development and mass-production capabilities will allow it to respond flexibly to changes in market demand.

In the large-sized display business, LG Display aims to reinforce its leadership in the premium market with differentiated technologies and cost-competitive products. As the monitor market continues to shift from liquid crystal display (LCD) to OLED technology, the company plans to expand its lineup of high-value products, including gaming OLED monitors, and increase shipments.

"We will continue improving our full-year performance and further solidify a stable earnings structure by advancing cost innovation and strengthening business competitiveness in the second half," said Kim Sung-hyun, chief financial officer of LG Display.

  •  
❌