❌

Reading view

EU Tech Regulation Creates a Costly Split for Apple

EU tech regulation, Digital Markets Act, Apple Europe sales, Apple regulation, European Union, Siri AI, iPhone features, device interoperability, App Store changes, alternative marketplaces, iPhone Mirroring, AirPods translation, Apple privacy, iPhone security, app sideloading, platform competition, DMA compliance, Apple Intelligence, European technology, government control

EU tech regulation is no longer limited to App Store payment rules or competition disputes hidden from ordinary consumers. It is beginning to determine which features reach European devices, how quickly they arrive and how deeply third-party companies can interact with the iPhone, iPad and Mac.

The Digital Markets Act was designed to reduce the control of large technology platforms over software distribution, payments, browsers, digital assistants and connected hardware. For Apple, compliance has already produced alternative app marketplaces, web distribution, third-party payment options, additional default-app controls and expanded access to iPhone technologies.

The next phase reaches much deeper into the operating system. European regulators want competing accessories, cloud services and AI assistants to receive access to capabilities traditionally reserved for Apple’s own products.

Apple argues that some of those demands could weaken privacy and security. The European Commission says the company is responsible for creating compliant systems that preserve both competition and user protection.

Between those positions sits a large and commercially significant group of customers. Europe generated $28.06 billion in Apple sales during the quarter ending March 28, 2026, up from $24.45 billion one year earlier. Six-month European sales reached $66.20 billion, compared with $58.32 billion during the same period of fiscal 2025.

Europe therefore represented more than one-quarter of Apple’s latest quarterly revenue. It is too valuable to leave behind, but increasingly difficult to serve with the same software experience available elsewhere.

EU Tech Regulation Is Splitting Feature Availability

Regional differences once centered mainly on language support, licensing agreements or local services. EU tech regulation is creating a more structural divide.

Apple has blamed Digital Markets Act requirements for delaying Siri AI across the European Union. The company says regulators expect competing AI assistants to receive extensive access to personal information, apps and device actions before Apple can reserve those capabilities for its own assistant.

The disagreement concerns more than answering questions. Siri AI is designed to read personal context, understand onscreen information and complete actions across apps. That may include finding messages, accessing files, making purchases or sending information on the user’s behalf.

Opening those capabilities to outside AI systems requires new permission structures, technical interfaces and safeguards. Apple says it cannot release its assistant first and add competing access later without risking regulatory action. The Commission says Apple had sufficient time to design an interoperable solution.

Other delayed European features have included iPhone Mirroring on Mac, Live Translation through AirPods and certain location-based Maps capabilities. Each feature touches a different part of the ecosystem, but all depend on privileged communication between Apple devices, software and services.

The consequence is becoming visible at purchase. Two customers can buy the same iPhone model at similar prices and receive different capabilities because one lives inside the European Union.
A black background with a glowing sphere in the center, featuring colorful light waves—red, orange, blue, and green—swirling horizontally inside the sphere, evoking a futuristic Siri AI interface.
Image Credit: Apple Inc.

Feature Adoption Becomes Slower and Less Predictable

Delayed availability can weaken the adoption of new hardware features even when the devices themselves continue selling well.

Siri AI is intended to become a central part of newer iPhones, iPads and Macs. Buyers who cannot access it lose part of the justification for newer chips, additional memory and on-device AI processing. Developers also face a smaller addressable audience for apps built around the new assistant.

AirPods Live Translation presents a similar problem. A feature designed to demonstrate the combination of iPhone processing, microphones and wearable audio becomes unavailable in a region built around dozens of languages and frequent cross-border travel.

iPhone Mirroring affects the relationship between iPhone and Mac. Users outside the EU can interact with the phone from macOS, while European users may receive notifications without gaining the complete experience.

These differences do not necessarily stop hardware sales. Apple’s newest results show strong European demand despite years of regulatory conflict. They can, however, reduce the speed at which customers use the ecosystem’s newest capabilities.

The effect may grow as software becomes a larger part of hardware differentiation. A faster processor has limited emotional value when the feature designed to demonstrate it is unavailable.

Apple Sales Show Why Europe Cannot Be Ignored

Apple does not report European Union revenue separately. Its Europe segment also includes countries outside the bloc, along with India, the Middle East and Africa. The official segment remains the best regularly published measure of the region’s commercial weight.

European sales rose approximately 15% year over year in Apple’s latest reported quarter. During the first six months of fiscal 2026, the segment expanded by roughly 14%.

Those figures weaken the argument that regulation is already driving customers away from Apple hardware. Demand remains strong, supported by the iPhone 17 family, Mac sales, services and the company’s installed base.

The financial risk is more gradual. Regional software fragmentation can raise engineering costs, delay launches and make European devices less competitive against products able to offer complete feature sets.

Apple must maintain separate distribution rules, payment systems, browser options and eligibility checks. Developers must decide whether alternative stores, external payments or EU-specific business terms justify additional work. Support teams must explain why features differ between countries using the same operating-system version.

A market responsible for more than $28 billion in one quarter can absorb considerable compliance expense. It can also influence Apple’s global product decisions when regulators demand interfaces that cannot be restricted to Europe easily.

A Slow Transfer of Ecosystem Control

The escalating regulatory environment also creates a more fundamental concern: control over complex technology ecosystems can gradually move away from the companies that designed them and toward government committees, regulatory bodies and administrative processes.

That transfer rarely happens through one dramatic order. It develops through repeated obligations covering app distribution, payment systems, browser engines, digital assistants, hardware access, data portability and interoperability. Each requirement may appear narrow when considered alone. Together, they can redefine who determines how the ecosystem operates.

Apple built its platform around tight integration between hardware, software, services and security. Regulators increasingly treat parts of that integration as market power that must be opened to competitors. The danger is that an ecosystem designed as one coordinated environment becomes subject to decisions made by committees that do not carry direct responsibility for product quality, reliability or long-term maintenance.

This can become a slow trap. Once a platform is required to expose one layer, regulators may use that access as the basis for demanding another. A payment exception can be followed by alternative app stores. Alternative stores can lead to broader installation rights. Device interoperability can expand into access for AI assistants, personal data and system actions.

The boundaries of the platform are then set less by engineering judgment and more by regulatory negotiation.

Government agencies have legitimate authority to address competition and consumer harm. The concern appears when regulation shifts from preventing abusive conduct to directing product architecture. At that point, public authorities begin influencing feature design, release timing, software permissions and the relationship between first-party and third-party services.

That creates consequences beyond Apple. Any company considering a tightly integrated product may decide that deep integration invites intervention. Businesses could avoid building ambitious ecosystems if successful coordination later becomes grounds for forced access.

Innovation then becomes shaped by what regulators are likely to permit rather than by what engineers believe will produce the safest or most coherent experience.
A large black Apple logo on a white background, with the shadow of a hand holding a padlock to the right side, symbolizing security or privacy in an era of AI and strict App Store rules around personal data sharing.
Image Credit: Ink Drop / Alamy Stock Photo

Competition Gains Come With Real Consumer Choices

EU policy has produced benefits that Apple rarely emphasizes. Users can install apps through alternative marketplaces or directly from authorized developers. Developers can offer external payment methods, promote different prices and avoid relying entirely on Apple’s distribution system.

Alternative browser engines can compete with WebKit, while users have more control over default apps. Contactless payment access has expanded beyond Apple Pay, allowing competing wallet providers to use the iPhone’s NFC technology under approved conditions.

Interoperability requirements could also improve third-party accessories. Smartwatches, headphones and other devices may gain better notification access, background connectivity and proximity pairing with the iPhone.

These changes can increase competition and reduce the advantage Apple gives its own services and accessories. A third-party smartwatch should not become artificially less useful simply because it was not made in Cupertino.

The difficulty is separating legitimate platform access from unlimited access. A notification interface is one thing. An autonomous AI assistant capable of reading messages, accessing files and acting across apps introduces a different level of sensitivity.

Privacy and Security Risks Are Not Theoretical

Alternative app distribution increases user choice, but it also moves some responsibility away from the App Store. Apple continues to notarize apps distributed through approved alternative channels, checking for known malware and severe fraud. That process is narrower than a complete App Store review.

Purchases made outside Apple’s payment system also fall outside its normal refund and billing support. Users may need to resolve disputes directly with the developer or payment provider.

A malicious marketplace, deceptive payment page or compromised developer account can create opportunities for fraud. Enterprise users face additional concerns when employees install software from sources their organization has not approved.

The AI question reaches further. A third-party assistant may need permission to access messages, photos, calendars, documents and app controls. Even a reputable provider can collect more information than the user expects or introduce vulnerabilities through poorly designed integrations.

Apple can build permission prompts, app isolation and revocation controls, but technical access always creates some exposure. Security depends on how narrowly permissions are defined, how visibly they are used and whether the operating system can stop unauthorized actions.

The Commission maintains that interoperability and privacy can coexist. Apple maintains that regulators are demanding access before adequate protections are ready. Both positions contain a legitimate concern: dominant platforms should not block competition, and competition should not require users to surrender control of personal data.
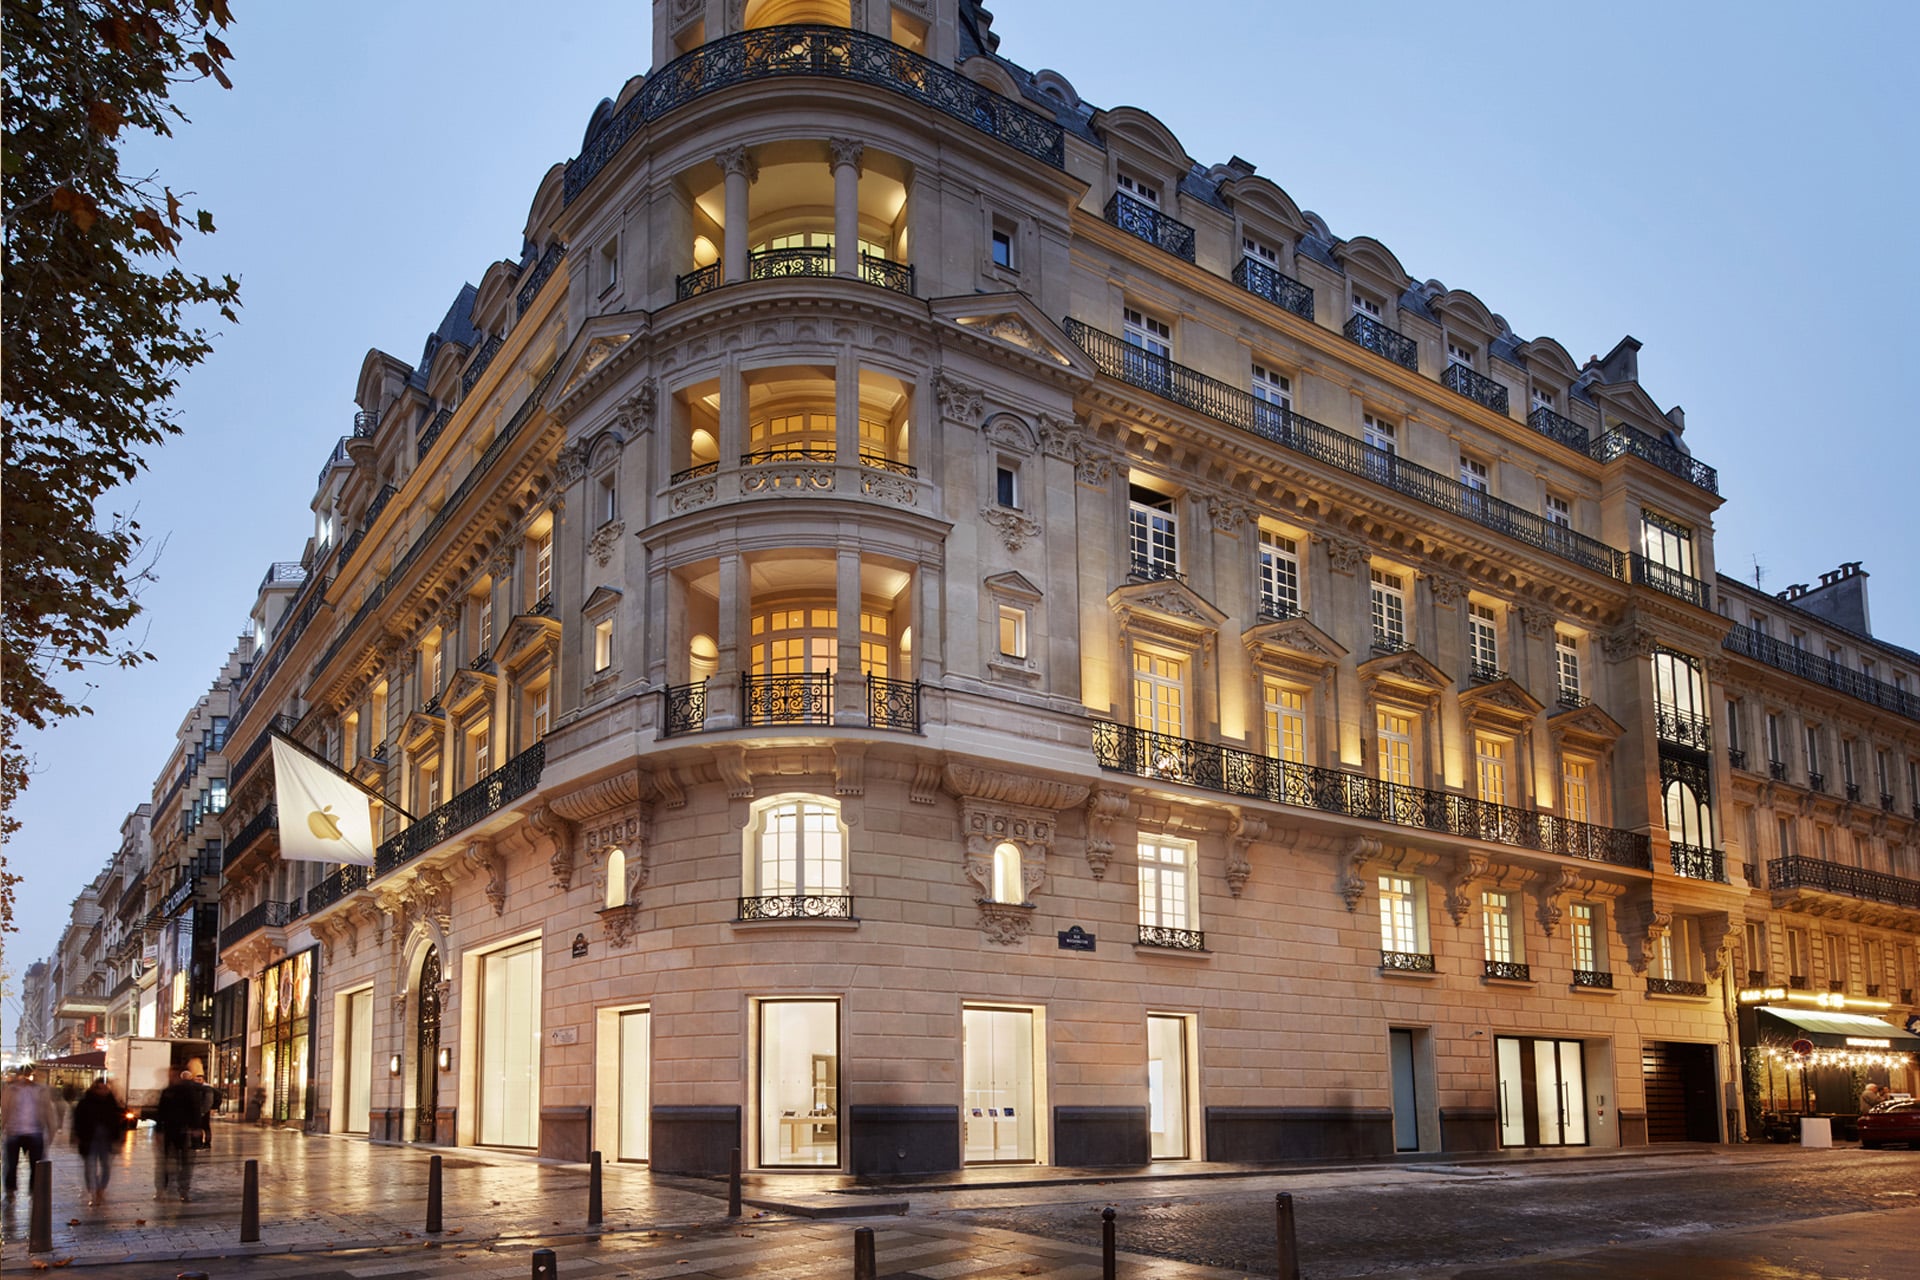
Elegant, historic Parisian building on a street corner at dusk, with warm lights glowing from large windows and ornate balconies—blending classic charm with Apple Store architecture. Pedestrians stroll nearby, passing a white flag with a gold emblem by the entrance.
Image Credit: Apple Inc.

Government-Controlled Architecture Creates Accountability Gaps

When regulators require a company to alter its architecture, responsibility can become blurred.

Apple remains the company customers blame when an iPhone feature fails, a third-party marketplace distributes a harmful app or an outside assistant misuses personal data. Regulators may have required the access, but they do not operate the device, provide technical support or repair the damage to the platform’s reputation.

This creates an accountability gap. Government committees can mandate openness without assuming the commercial and security consequences of that openness. Apple must comply, maintain the system and explain the outcome to users.

The same problem applies to delayed features. Regulators may argue that Apple chose not to release a service, while Apple may argue that the required conditions made the launch unsafe or technically impractical. Customers are left with less functionality and no simple way to determine who caused the delay.

Over time, the ecosystem can become a negotiated compromise rather than a product with one coherent direction. That may satisfy formal compliance while producing a weaker experience for everyone involved.

The risk is not that governments will literally operate Apple’s software. It is that committees increasingly define the conditions under which Apple can design, connect and release its own features. Control shifts through constraints.

The Industry Will Follow Europe’s Experiment

The consequences extend beyond one company. Google, Meta, Microsoft, Amazon and other platform operators face related European obligations. Hardware makers must consider whether ecosystem advantages can survive when core services are required to support rivals.

Smaller developers may gain new distribution and payment choices, but they may also inherit more compliance, customer-service and security responsibilities. Accessory companies could compete more effectively while becoming accountable for handling sensitive device data.

Other governments are watching. Rules introduced in Europe can influence legislation elsewhere, particularly when companies decide that maintaining one global technical framework is easier than operating several regional versions.

Apple is unlikely to abandon Europe or stop adapting its products. Its sales provide too much evidence of the region’s importance. The company will continue negotiating, appealing decisions and building compliance systems while withholding features it considers unsafe under current demands.

European customers may receive more app stores, payment choices and accessory compatibility. They may also wait longer for headline features included with the same hardware elsewhere.

The deeper consequence may be a technology industry that becomes more cautious about building tightly integrated products. Companies may design around anticipated regulatory demands from the beginning, limiting exclusive features, reducing private-system integration or avoiding innovations that depend on controlled access.

EU tech regulation began as an effort to constrain dominant platforms. Its long-term effect may be to transfer part of the power to shape those platforms from companies and users to regulatory institutions.

That shift deserves scrutiny equal to the market power it is intended to correct. Competition rules can restrain abuse. They can also become a slow mechanism for placing product design, security choices and ecosystem evolution under government supervision.

Shady Control and Bureaucracy

The danger grows when regulatory discretion becomes buried beneath permits, approvals, negotiations and technical committees that operate beyond meaningful public scrutiny.

The more power officials hold over which features, contracts or technologies may proceed—and when—the greater the opportunity for lobbying, favoritism and selective enforcement to influence outcomes. What begins as oversight can gradually become a system in which delay itself is leverage, while responsibility disappears inside layers of administration.

For the technology industry, that risks replacing transparent product decisions with political access, negotiated exceptions and regulatory influence exercised far from the consumers expected to live with the consequences.

The post EU Tech Regulation Creates a Costly Split for Apple appeared first on AppleMagazine.
  •  

Goooool v goal: English speakers flock to Telemundo for lively World Cup coverage

The Spanish-language broadcaster has won over millions of US viewers with its energetic commentary during games

Soccer fans looking to watch the 2026 World Cup on US television have been presented with two very different options this tournament.

The first is Fox Sports, a cousin of Fox News owned by the same parent company and the sole network airing matches in English in the US. Audiences tuning in to Fox, which acquired the exclusive English broadcast rights in 2015, are met with coverage that reflects the network’s “America first” aesthetic, with promos for pro-Donald Trump talkshows, advertising breaks during games and the frequent, grating presence of host Alexi Lalas.

Continue reading...

© Photograph: Sarah Yenesel/EPA

© Photograph: Sarah Yenesel/EPA

© Photograph: Sarah Yenesel/EPA

  •  

Apple widens OpenAI trade secrets fight with preservation orders

Dozens of former Apple employees now working at OpenAI have been put on notice after Apple reportedly sent legal letters ordering them to preserve documents and communications relevant to its trade secrets lawsuit against OpenAI. 

The Financial Times reports that “around 40” employees have been targeted with these letters, which repeat Apple’s claim that its confidential information might have been exfiltrated, alleging “trade secret misappropriation and breach of contract.”  The letters also require them to arrange to meet with Apple’s lawyers.

The underlying lawsuit

This comes on the heels of Apple’s explosive lawsuit against OpenAI in which Apple accused the AI company (and former Apple Vice President Tang Tan) of extensive coordinated data theft. Tan was at Apple for 24 years and is now Chief Hardware Officer at OpenAI. 

Apple’s lawsuit is defined by claims OpenAI took a range of steps to pry confidential Apple data from existing Apple employees, including using information such as internal project code names, to gain even more knowledge during interviews. The company says the evidence it has presented so far is only the “tip of the iceberg” concerning OpenAI’s approach.

The lawsuit requests that OpenAI be prevented from using any Apple information during the development of its hardware. Apple is also seeking damages and suing two former employees for breach of contract for violating their employment agreements.

The letters are significant. They represent formal directives that require former Apple staff to preserve documents, messages, emails, and other communications that could be relevant to the case. The demand reflects Apple’s belief that the alleged misuse of confidential information could be more widespread across the competing company. What’s critical is that orders of this kind override any standard data destruction policy and deletion of the requested information becomes a legal offense. 

Why this matters beyond the protagonists

In making its move, Apple shows this is not a dispute about just one or two hires, but an attempt to constrain the movement of intellectual property between the two firms. With AI hardware emerging as the next major battleground in tech, the case could become a defining one; whatever resolution is eventually reached could define the extent to which former employees can carry experience and knowledge between competing firms. The case might also define what the line is between experience and knowledge and the sharing of trade secrets.

This is important, because modern hardware development relies on far more than just finished designs. Product design leans into supplier relationships, manufacturing assumptions, physics, extensive prototyping, and product-roadmap priorities. If courts treat those accumulated insights as protectable secrets, hiring between major technology companies could become far more legally sensitive.

The Jony Ive question

The case comes as Apple prepares to combat OpenAI in hardware. Its competitor is now working with legendary former Apple designer Jony Ive. Ive is not named in the litigation, but Apple will be keen to find out whether confidential product knowledge, design processes, or supply-chain insights have travelled with former staff into OpenAI’s device work.

Ultimately, for Apple, it’s about protecting its many blueprints for whatever hardware the company expects will come after the iPhone.

For its part, OpenAI has refuted Apple’s lawsuit, arguing that it is “not aware of any evidence” that the lawsuit has merit. “We have no interest in other companies’ trade secrets,” said OpenAI spokesperson Drew Pusateri. “We remain focused on building innovative technology that empowers people everywhere.” The company’s lawyers also claim it did respond to Apple’s initial inquiries on the matter.

What’s at stake

The significance of Apple’s newly-shared communication preservation orders is that if discovery uncovers evidence supporting Apple’s claims, the case could complicate OpenAI’s hardware plans and create unwelcome scrutiny ahead of any future public offering.

You can follow me on social media! Join me on BlueSky,  LinkedIn, Mastodon and subscribe to The Core.

  •  

China, Russia, and 27 others create World AI body, without US

China has created an international organization to set standards and introduce regulation for AI, inviting 28 other countries to join — but the US, a leading AI powerhouse is not part it.

The World Artificial Intelligence Cooperation Organization (WAICO) was established by 29 countries, including China, Russia and Brazil, at a ceremony in Shanghai, China, on July 16. Notably absent are the US, the European Union and its member states, the UK, Japan and South Korea.

Chinese AI companies have made a concerted effort to provide an alternative to US dominance. While the US is clearly ahead, Chinese enterprises are looking to narrow the gap in various areas: the open-weight model market, AI cyber protection and open source AI.

WAICO has been some years in development and has been designed to set some universal guidelines in AI. Researchers say WAICO differs in three ways from other initiatives to create global AI organizations: membership open to any sovereign state, there is no regime-type test for entry, and its agenda is built around development and the global capability divide.

The signing ceremony to create WAICO comes just days after Demis Hassabis, CEO of Google DeepMind, called on the US to take a lead in global AI regulation. “The US is well-positioned to take the first step in developing such a framework. It could establish a new Standards Body modelled on a federally overseen public-private partnership or self-regulatory organization, much like the Financial Industry Regulatory Authority (FINRA), with a board that includes independent leading technical experts and open-source representatives,” Hassabis wrote.

  •  

Can Meta really compete in the cloud business?

Meta is reportedly planning a cloud business that would sell access to AI computing power and models, extending its internal infrastructure into a commercial service for outside developers and enterprises. Reuters, citing Bloomberg’s reporting, noted that the planned offering would allow customers to access AI models hosted on Meta’s infrastructure and pay based on usage, effectively positioning the company in the infrastructure-as-a-service and AI platform markets. On the surface, this seems like a logical next step. If you are already spending enormous amounts of money to build AI infrastructure, there is a natural temptation to ask whether some of that investment can be monetized beyond your own internal use.

I have seen this pattern before. A company builds sophisticated internal systems, recognizes their value, and then begins to imagine that becoming a cloud provider is simply a matter of exposing those capabilities to external customers. It sounds straightforward, especially given the excitement around AI and the demand for high-performance infrastructure. But cloud computing is not just another distribution model. It is not simply a matter of offering on-demand multitenant services and charging a fee. It is a deeply operational, trust-based business in a market that punishes companies that do not fully understand what enterprise customers require.

A crowded neocloud market

The first problem Meta faces is that this is not an open opportunity. The neocloud space, meaning purpose-built AI infrastructure delivered as a service, is already crowded and increasingly difficult to enter. Amazon, Microsoft, and Google dominate the conversation for obvious reasons. They have years of cloud operating experience, broad service portfolios, global reach, mature ecosystems, and deeply established enterprise relationships. Oracle remains a serious player as well, especially in enterprise applications, data platforms, and performance-sensitive workloads. IBM still matters in hybrid cloud, operations, and industries where governance and regulatory rigor remain central.

That list alone should give Meta pause. These companies are not just infrastructure vendors. They are experienced cloud operators. They have spent years building not only the underlying platforms, but also the native capabilities enterprises now expect by default. Those capabilities include security, governance, identity management, observability, support, compliance, billing controls, resilience planning, and integration with the broader enterprise technology estate. These are not secondary features. They are part of the core value proposition.

This is why late entry into the cloud market is so hard. A new provider is not just competing on price or capacity. It is competing against accumulated trust. Enterprises are not casual buyers. They are selecting long-term operating environments for applications, data, AI models, and business-critical processes. They want confidence that the provider understands how these services will be consumed, governed, and supported over time. Meta is entering a market where the incumbents already have a major head start on all of those fronts.

Harder than it looks

Over the years, I have had many technology companies come to me and say they wanted to reposition their technology in the cloud space, either as software as a service or infrastructure as a service. In the beginning, enthusiasm is always high. The technology is impressive. The market size looks attractive. The revenue models appear compelling. Investors love the story. Then we begin to walk through what it really means to operate as a cloud provider, and the optimism usually fades fast.

The questions become very practical and very uncomfortable. How will tenants be isolated? How will identity and access controls work across different kinds of customers? What governance models will be built in natively? How will workloads be monitored, optimized, and secured? What does support look like 24 hours a day, across regions, across industries, across compliance boundaries? How will outages be handled, communicated, and remediated? How will the platform integrate with existing customer tools for operations, policy management, and security response? How much investment will it take just to become credible before you even begin to differentiate?

Once companies fully understand the complexities, market dynamics, and the capital and execution required to compete even with secondary players, many of them back off. They realize that cloud technology is not a packaging exercise. It is a transformation in how a company designs, operates, supports, sells, and evolves technology. That is why I remain skeptical when any company assumes it can translate internal infrastructure excellence into external cloud success without a very long, disciplined commitment.

Meta’s market readiness

Of course, Meta is not lacking in financial resources. If any company can afford to spend aggressively in this space, it is Meta. The company has the capital to build infrastructure, absorb losses, hire experienced talent, and stay in the market long enough to make a serious attempt. I would never argue that Meta is too small or too poor to try. Quite the opposite. If there is any non-traditional entrant with the financial scale to force itself into the conversation, Meta would be high on the list.

But money does not erase complexity. It only gives you the chance to confront it. The real question is not whether Meta can afford to become a cloud provider. The question is whether Meta has what it takes to become an excellent cloud provider. Those are two very different things. Enterprises are not going to move meaningful workloads to a new platform simply because the company behind it is wealthy or technically famous. They are going to ask whether the provider understands enterprise consumption patterns, enterprise risk, enterprise governance, and enterprise operations.

That is where the challenge becomes much more serious. Meta has extensive experience running infrastructure for itself. That is valuable, but internal operating excellence is not the same thing as external service maturity. Running systems for your own workloads allows a high degree of control over architecture, standards, priorities, and operating assumptions. Running systems for paying customers requires flexibility, consistency, transparency, and support across a wide range of use cases that you do not control. Those are very different disciplines, and companies often underestimate the gap between them.

What exactly is Meta?

Another concern here is strategic clarity. Meta already has a complicated market identity. It is a social media company, an advertising platform company, a hardware company, an AI company, and still, in the minds of many, the company that spent billions pursuing the metaverse. If it now wants to be viewed as a serious cloud infrastructure provider, it will need to explain not only what it is offering, but why customers should believe this is a durable long-term commitment and not just another adjacent experiment.

That uncertainty can be damaging. Customers want stable providers with clear strategic intent. They do not want to architect important systems around a platform if they suspect the provider may lose interest, shift direction, or reframe the business after a few years of uneven results. Cloud computing requires patience, consistency, and deep customer orientation. It is not a market where strategic ambiguity helps.

This could become confusing for Meta internally as well. Building a true cloud business demands focus. It demands years of investment in areas that may not be glamorous but are absolutely necessary, such as governance, operations, controls, support frameworks, partner programs, and enterprise sales alignment. If the company is not willing to make those sacrifices fully and for the long term, the initiative will struggle.

  •  

Is Apple bringing chip manufacturing home?

Apple’s recently announced $30 billion multi-year agreement with Broadcom is significant because it means billions of chips for Apple devices will be made in the US, supporting hundreds of jobs. 

This is Apple’s biggest US procurement deal so far, but it won’t be the last; when it announced the arrangement, Apple confirmed it is, “working with the administration and businesses across the US to help create an end-to-end silicon supply chain in America.”

That statement implies that the 15 billion chips Broadcom will produce won’t be the only processors in Apple devices to carry tiny little “Made in the USA” slogans. Broadcom is making custom silicon components and wireless connectivity technologies such as RF/wireless chips (Wi-Fi, Bluetooth, cellular, FBAR filters) and ASIC work, rather than application processors. But they are still chips for Apple devices.

TSMC doubles down

That’s why it is significant that TSMC confirmed plans to extend its own manufacturing in America. It already has a $165 billion US commitment; now, it is investing an additional $100 billion in four more chip plants — including one dedicated to churning out the company’s most advanced 2nm (and smaller) processors. 

“We believe this investment will help to further foster the development of the US semiconductor ecosystem, strengthen the supply chain, and support an increasing number of high-tech, high-paying jobs in the United States,”  CEO C.C. Wei told analysts.

TSMC has also confirmed plans to invest in packaging facilities for processors, which is basically the process where memory, processor, and networking nodes can all be combined and packaged on the chip. That sort of packaging is needed to make the final SoC chip. That means TSMC factories in the US will be able to churn out the advanced processors used in Apple’s current and, presumably, future devices.

The bill so far

That’s three investments — in processor manufacturing, packaging, and Broadcom radios and chips — all of which are strategically important to Apple devices. TSMC makes the brains, Broadcom brings the connectivity. Total value so far: $295 billion, around 1.5 times Apple’s annual revenue in the Americas.

It isn’t all about Apple. TSMC has other clients, and Apple is no longer the company’s biggest customer thanks to the drive to AI. But it is still an important one. That means at least some of TSMC’s newly invested US manufacturing capacity will be dedicated to making chips for Apple. The open question is how much US-manufactured chips will cost in contrast to those made elsewhere.

It’s bigger than two deals

These aren’t the only chip-focused partnerships Apple has made domestically. Apple’s American Manufacturing Program (AMP) launched in August 2025 as part of a $600 billion four-year US investment commitment. TSMC and Broadcom were both named AMP partners, but they weren’t alone, and some arrangements have already been announced:

  • GlobalFoundries is bringing mixed-signal chip manufacturing to make advanced ICs for Face ID.
  • Texas Instruments expanded production for analog/power chips.
  • Samsung is making a new chip-making process at its Austin, TX fab, described by Apple as having “never been used before anywhere in the world.”
  • Apple became the “first and largest customer” of Amkor’s new advanced packaging/test facility in Arizona.
  • Corning is expanding glass production.
  • Applied Materials is making chip manufacturing equipment under AMP.

Bundle all these deals together and it’s crystal clear that Apple’s $600 billion investment is at least in part focused on the technologically advanced components on which its devices are built. These components also have the advantage in being incredibly small, which means they are easy and cheap to ship for final assembly at increasingly automated final production locations worldwide. 

So, is it coming home?

That’s the strategy: keep the high-value, hard-to-automate work — and the jobs it requires — in America, while leaving final assembly flexible enough to go wherever that makes sense now or in the future. Is Apple bringing manufacturing home? Partially, in that the bits that matter the most — brains and networking— are coming back, even if assembly is not.

You can follow me on social media! Join me on BlueSky, LinkedIn, Mastodon, and subscribe to the human-curated daily Apple news briefing at The Core.

  •  
❌