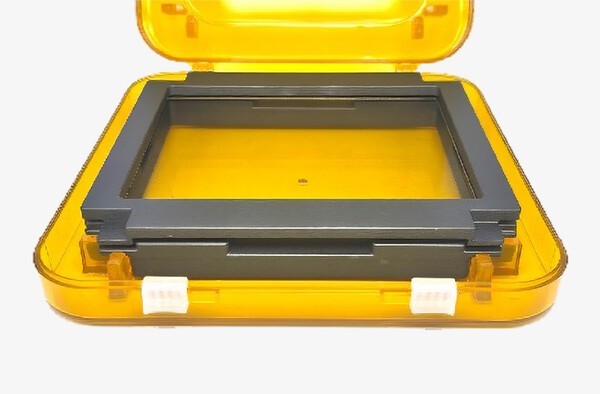
aweXome Ray said on Aug. 11 it has secured 7.5 billion won in a Series B bridge financing round, with investors recognizing the technological and commercial potential of its carbon nanotube (CNT)-based extreme ultraviolet (EUV) pellicle membrane.
Strategic investors included S&S Investment, an affiliate of S&S Tech, a manufacturer of photomasks and EUV pellicles, as well as Wonik Investment Partners. Wonik Investment Partners and Hanwha Investment & Securities participated through a jointly managed fund. Other investors included Reinvestment, L&S Venture Capital, KNET Investment Partners, Union Investment Partners, and Ascendo Ventures.
The company said participation by pellicle manufacturers, semiconductor materials and equipment companies, and financial investors demonstrates industry recognition of both the technological competitiveness and commercialization potential of its CNT-based pellicle membrane. It added that the participation of a defense-focused fund jointly managed by Wonik Investment Partners and Hanwha Investment & Securities also highlights the potential application of its CNT fibers and membranes in aerospace and defense.
The proceeds will be used to stabilize production of EUV pellicle membranes, strengthen quality control systems and support customer supply programs. aweXome Ray has established a dedicated cleanroom production line for EUV pellicle membranes in Anyang, Gyeonggi Province, to produce qualification samples and support initial customer shipments. The company said customer evaluations are currently underway and expects initial commercial supply and revenue once qualification is completed.
aweXome Ray is developing CNT-based membranes for EUV pellicles used in advanced semiconductor lithography. Pellicles protect photomasks carrying semiconductor circuit patterns from contamination during the EUV exposure process, requiring both high EUV transmittance and exceptional heat resistance. The company said CNT materials, which are lightweight, thin and highly heat-resistant, are well suited for next-generation pellicles designed for high-power EUV exposure environments.
The company has also strengthened its pellicle business with additional industry expertise. Hong Sung-chul, a senior executive at S&S Investment, joined aweXome Ray's board as an outside director in March. A former Samsung Electronics engineer with experience in semiconductor photomask and pellicle development, Hong will support customer qualification and technical engagement.
In February, Lee Dong-wook, who previously led advanced materials commercialization at LG Chem and EcoPro BM, joined the company as Chief Product Officer (CPO). He oversees the pellicle business division and is responsible for converting research and development achievements into commercial products and customer supply.
aweXome Ray is also participating in a government-funded pellicle technology development project under South Korea's Deep Tech Challenge program administered by the Ministry of SMEs and Startups. The company is carrying out a 3.6 billion won research and development project and has been selected for the Korea Technology Finance Corporation (KIBO) Unicorn Bridge program, securing 600 million won in funding and eligibility for up to 20 billion won in technology guarantees. The company plans to combine private investment with government R&D support to advance its technology and accelerate commercialization.
The company is also stepping up preparations for an initial public offering (IPO). After signing an investment agreement with Jeju Special Self-Governing Province in March, it relocated its headquarters to the Jeju Science Park. Having been selected as one of the province's IPO support companies, aweXome Ray is preparing to appoint an IPO underwriter and undergo a preliminary technology assessment. The company aims to pursue a technology-track listing in 2028 while advancing customer qualification and initial product shipments.
Hong Sung-chul, senior executive at S&S Investment, said aweXome Ray possesses differentiated CNT-based EUV pellicle membrane technology and strong commercialization potential.
"With its production line now in place and customer qualification underway, the company has entered the commercialization stage. We will actively support the establishment of a stable supply chain and successful market entry," he said.
Chief Executive Officer Kim Se-hoon said the new production line and funding round represent an important milestone in transforming aweXome Ray from a research-focused company into an advanced materials supplier capable of serving customers.
"We will successfully complete customer qualification, accelerate commercialization of our CNT-based EUV pellicle membrane, and strengthen our competitiveness in the global semiconductor materials market," he said.
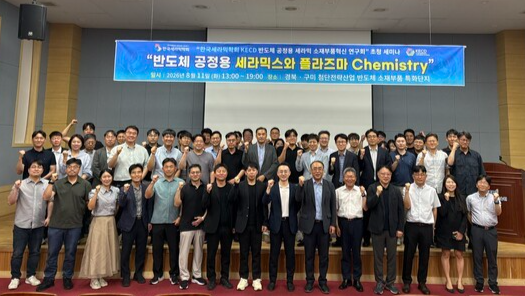
The Semiconductor Process Ceramics Materials and Components Innovation Forum Seminar hosted by KECD on Aug. 11. (Photo: KECD)
The Semiconductor Process Ceramics Materials and Components Innovation Forum Seminar hosted by KECD on Aug. 11. (Photo: KECD)
Semiconductor ceramics materials suppliers and their customers are expanding technical collaboration while strengthening industry-academia-research partnerships to reinforce the semiconductor supply chain.
The Engineering Ceramics Division (KECD) of the Korean Ceramic Society said on Aug. 11 it hosted the Semiconductor Process Ceramics Materials and Components Innovation Forum Seminar at the IT Medical Convergence Technology Center in Geumo Techno Valley, Gumi, North Gyeongsang Province. The event was jointly organized with the Semiconductor Process Ceramics Materials and Components Innovation Forum and the Gyeongbuk–Gumi Semiconductor Specialized Complex Promotion Team.
The seminar brought together semiconductor manufacturers and equipment companies including Samsung Electronics, SK hynix, SEMES, Lam Research Korea, Wonik IPS, TES, and Eugene Technology. A total of 30 companies participated overall, including ceramics materials and components suppliers such as Wonik QnC, Komico, Mico Ceramics, TCK, Worldex Industry, CMTX, and LKN Engineering.
The seminar focused on "Ceramics and Plasma Chemistry for Semiconductor Manufacturing Processes." Presentations covered plasma resistance characteristics of ceramic materials used in etching and deposition chambers, particle reduction technologies and design strategies for high-durability ceramics. Researchers from Korea Aerospace University, the Korea Research Institute of Standards and Science (KRISS), Kumoh National Institute of Technology, and the Korea Institute of Materials Science (KIMS) presented their latest research.
Following the seminar, participants held an industry-academia networking session to discuss expanding technical collaboration and joint research among companies and research institutes. The promotion team said it plans to make the seminar a regular event and use it as a platform for future commercial cooperation.
Lee Hyun-kwon, head of the Gyeongbuk–Gumi Semiconductor Specialized Complex Promotion Team, said the event marked the first opportunity for leading semiconductor manufacturers and materials suppliers in South Korea to share commercialization technologies and on-site industry requirements.
He added that the Gyeongbuk–Gumi Semiconductor Specialized Complex will strengthen its role as a collaborative platform linking companies with one another as well as with research institutions.
Avaco said on Aug. 11 it has begun operating a pilot production line, developed in collaboration with affiliate AVATEC, to validate through-glass via (TGV) processes for next-generation semiconductor packaging substrates.
The companies completed construction of the pilot line in the first half of this year. The line supports large-format glass substrates measuring 515 × 510 millimeters and integrates laser drilling, etching, seed-layer deposition and optical inspection into a single process flow.
In addition to evaluating the performance of individual production tools, the pilot line is designed to verify process integration and repeatability in mass production. AVATEC, drawing on its manufacturing experience in display glass etching and thin-film processing, will oversee process operation and production stability.
Avaco has been investing in TGV equipment and process technologies since 2023. Its flagship second-generation TGV laser drilling system, AXIUM AP-250K, is capable of processing up to 10,000 via holes per second using dual optical heads. The company said the system achieves tolerances below 5 micrometers, enabling uniform processing across large-area glass panels.
The company has also secured alkaline wet etching technology and seed-layer deposition equipment for post-laser processing. By combining physical vapor deposition (PVD) with hybrid deposition techniques, Avaco is advancing process technologies for controlling high-aspect-ratio structures and forming uniform metal layers, both of which are critical for TGV substrates.
An optical inspection system has also been installed to inspect defects generated during the manufacturing process. The system performs full inspection of TGV hole geometry and processing quality and will be linked with an automated production line to validate quality control systems for mass production. The company added that it has secured a variety of glass materials through non-disclosure agreements (NDAs) with major glass suppliers.
The two companies plan to provide TGV glass substrate samples incorporating laser drilling through seed-layer deposition in 2026. The samples will range in size from 100 × 100 millimeters to 515 × 510 millimeters. In 2027, they plan to expand sample offerings to include metallized substrates incorporating laser drilling, etching, deposition, via filling and planarization processes.
Avaco said it is currently discussing technology collaboration and future mass production with multiple overseas customers. Once the pilot line has completed process and equipment validation, Avaco plans to expand its TGV equipment business, while AVATEC will participate in commercialization of glass substrates by leveraging its etching technology and process operation expertise.
An Avaco official said the company believes that validating the entire manufacturing process—not just individual tools—is essential for entering the glass substrate market.
"Through our collaboration with AVATEC, we will organically combine equipment, process technology and mass production expertise to establish an integrated TGV solution capable of delivering the production-ready products our customers require," the official said.
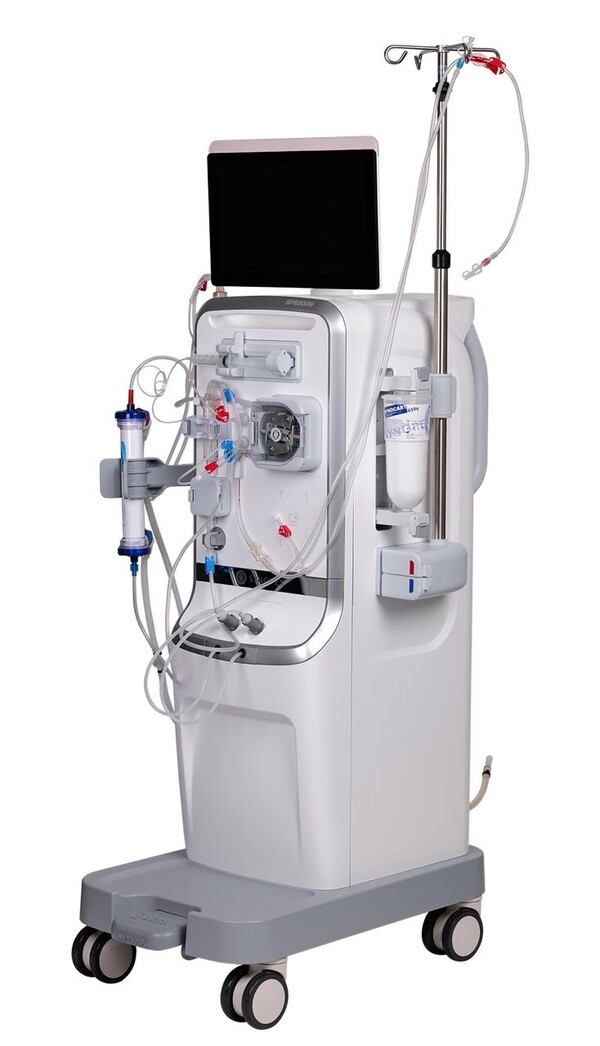
Synopex said on Aug. 11 it has received marketing approval from South Korea's Ministry of Food and Drug Safety (MFDS) for its hemodialysis (HD) machine, paving the way for domestically developed products to enter a market that has been entirely dependent on imported systems.
Hemodialysis is a treatment that removes waste products and excess fluid from the blood of patients with chronic kidney disease. The procedure relies on several key medical devices, including hemodialysis machines, dialyzers and water purification systems.
With the approval, Synopex said it has completed the localization of the three core medical device solutions used in hemodialysis: dialyzers (hemodialysis filters), portable water purification systems for hemodialysis machines and HD machines. The company had previously obtained MFDS approvals for 11 hemodialysis filter products, a continuous renal replacement therapy (CRRT) system for critically ill patients and a portable water purification system for hemodialysis equipment.
The HD machine was developed under a national project led by the Korea Medical Device Development Fund (KMDF) in collaboration with researchers from the Department of Nephrology and the Department of Biomedical Engineering at Seoul National University Hospital. In 2024, KMDF designated the localization of the three core hemodialysis medical devices as one of its 10 flagship national projects.
Synopex is developing an upgraded follow-up model of its CRRT system for critically ill patients. It is also working on a mass-production version of its HD machine equipped with hemodiafiltration (HDF) functionality. The company plans to seek regulatory approval and commercialize the HDF-equipped model in the future.
Kang Chang-ho, head of Synopex's Artificial Kidney Sales Division, said the MFDS approval for the HD machine marks "a historic starting point" in establishing medical sovereignty in South Korea's hemodialysis device market, which has long relied entirely on imported products.
He added that the company is preparing for mass production of the HD machine alongside its dialyzers and water purification systems, which are already being introduced to the market.
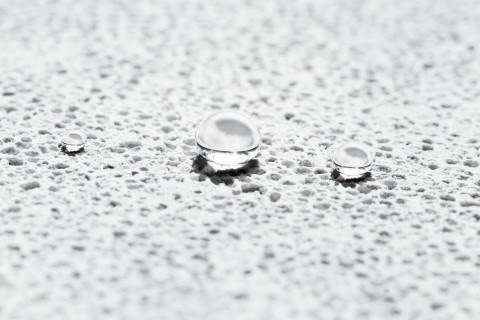
Water droplets formed on the surface of autoclaved lightweight concrete (ALC) after treatment with LC4004WR RainGuard. (Photo: Wacker Chemicals Korea)
Water droplets formed on the surface of autoclaved lightweight concrete (ALC) after treatment with LC4004WR RainGuard. (Photo: Wacker Chemicals Korea)
Wacker Chemicals Korea said on Aug. 11 it has launched RainGuard, a premium water-repellent treatment for building exteriors designed to reduce moisture penetration and improve the durability of exterior walls.
The new product, LC4004WR RainGuard, is a water-based penetrating water repellent that maintains water vapor permeability, allowing moisture inside building materials to escape. It can be applied to concrete, brick and mortar using spray, roller or brush application methods.
Without forming a separate coating film on exterior surfaces, the product reduces water absorption by approximately 20% to 25% compared with conventional products, according to the company. It also increases the water contact angle by about 10%, enhancing the beading effect. Wacker said early water-repellent treatment is important because prolonged exposure to moisture can lead to reduced thermal insulation performance, efflorescence and cracking in building exteriors.
The product was developed using Wacker's silane- and siloxane-based water-repellent technology from Germany. The water-based emulsion preserves the breathability of building materials while providing excellent beading performance and weather resistance. It is designed for use as a water-repellent treatment for mineral-based exterior building materials.
South Korean semiconductor inspection equipment maker Nextin will begin production qualification testing of two inspection systems with a European semiconductor manufacturer, marking its first supply of inspection equipment for logic semiconductor production.
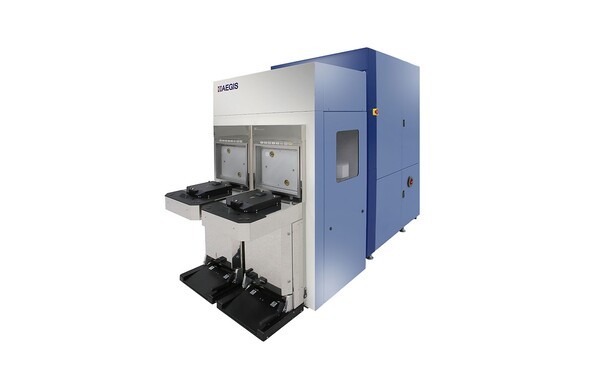
According to industry sources, Nextin plans to deliver its front-end inspection system AEGIS 3 and back-end inspection platform KROKY to the customer in the third quarter. The equipment will be installed on the customer's production line for evaluation of performance and suitability for mass production. The identity of the customer was not disclosed.
A Nextin official said the company could not reveal the customer due to a non-disclosure agreement (NDA) but noted that the logic semiconductor market has high entry barriers and currently represents a larger share of global semiconductor equipment investment than the memory segment.
Among European semiconductor manufacturers operating front-end fabrication facilities are STMicroelectronics, NXP Semiconductors and Bosch. These companies primarily produce chips using mature process technologies of 28 nanometers and above, including automotive microcontroller units (MCUs) and power semiconductors.
Nextin's AEGIS system is a front-end 2D imaging inspection tool used during wafer fabrication, where microscopic circuit patterns are formed on semiconductor wafers. The system illuminates the wafer surface and captures circuit images using multiple CMOS sensors. It detects nanometer-scale pattern defects and foreign particles by comparing captured images with reference patterns.
The tool incorporates both bright-field (BF) and dark-field (DF) optical inspection technologies. Bright-field inspection uses reflected light, while dark-field inspection relies on scattered light, allowing customers to select inspection modes according to process requirements.
KROKY is an optical defect inspection platform designed for semiconductor back-end processes. The system uses high-performance time-delay integration (TDI) sensors to enable fast, high-density imaging.
Target applications include power semiconductors based on silicon carbide (SiC) and gallium nitride (GaN), as well as advanced packaging structures for high-bandwidth memory (HBM), including through-silicon vias (TSVs), redistribution layers (RDLs) and final assembly inspection. By performing BF and DF inspections within a single system, KROKY can reduce process time and improve throughput. The platform also incorporates AI-based deep-learning algorithms to enhance defect classification accuracy.
The product family includes two models: KROKY-W and KROKY-R. KROKY-W is designed to evaluate thin-film uniformity before device wafers are diced into individual chips. KROKY-R inspects individual dies after dicing and can identify defects such as cracks, chipping and wafer warpage with high precision.
Given the technical requirements of the mature-node manufacturing processes commonly used by European semiconductor producers, industry sources expect the production qualification process to take approximately six months. If evaluations are completed successfully within the first and second quarters of 2027, the customer could proceed with formal purchase orders and volume production supply agreements.
Nextin plans to leverage the qualification program as a reference case to expand its customer base in the global logic semiconductor market.
Lotte Energy Materials has entered the market for ultra-thin copper foil used in artificial intelligence (AI) data centers and is considering a third capacity expansion based on binding customer agreements.
The company disclosed its third-phase expansion strategy on Aug. 6, centered on ultra-thin copper foil products. Ultra-thin copper foil, measuring between 1 and 3 micrometers in thickness, is a next-generation circuit material used in AI data center optical transceivers and semiconductor packaging applications. The product is significantly more difficult to manufacture than conventional circuit foil due to its extremely thin profile.
Lotte Energy Materials currently supplies reverse-treated foil (RTF) and high-voltage low-profile (HVLP) copper foil for AI data center optical transceivers. The materials are used in the inner and outer layers of transceiver substrates. RTF products range from 12 to 70 micrometers in thickness, while HVLP products range from 12 to 35 micrometers.
The company plans to expand its portfolio into the thinner ultra-thin copper foil segment to target the rapidly growing optical transceiver market.
The ultra-thin copper foil market is currently dominated by Japan’s Mitsui Chemicals. However, rising investment in AI data centers has created an opportunity for new entrants. Demand for ultra-thin copper foil has surged as optical networking transitions toward 800G and 1.6T architectures. At the same time, North American customers have increasingly sought non-Chinese supply chains. Lotte Energy Materials is currently the only company operating a circuit foil production base in South Korea.
The company emphasized that any third-phase expansion will depend on securing binding agreements with customers. Future investment decisions will be based on confirmed demand commitments rather than speculative capacity additions.
“Customer demand for additional expansion is strong, and we are reviewing a third expansion phase either at available space within our domestic facilities or at a new site,” the company said. “The project will proceed once binding customer contracts are signed and economic feasibility is secured.”
Lotte Energy Materials added that it plans to determine the timing and scale of investment through discussions with customers and is already conducting preliminary preparations, including concept design work, due to strong demand from key clients.
The broader circuit foil business is also shifting toward AI-related applications. Demand has expanded beyond traditional IT products into high-end copper foil for AI accelerators, network switches and optical transceivers.
High-value-added HVLP products currently account for roughly 20% of circuit foil sales. Following completion of the second expansion phase next year, the proportion is expected to exceed 50%. Some production lines dedicated to AI-focused HVLP products are already being operated exclusively for specific customers.
The company began mass production earlier this year of HVLP 1 and HVLP 2 products used in AI networking equipment supplied to Nvidia systems. Production yields have reached approximately 60%, and commercial shipments began in the second quarter after customer qualification procedures were completed.
Production capacity for HVLP 3 and HVLP 4 products designed for Nvidia’s next-generation Rubin platform was secured through the first expansion phase completed in May. Initial mass production began in the second quarter, and related revenue is expected to increase in the second half as Rubin shipments expand.
Lotte Energy Materials completed its first expansion phase in May, increasing annual circuit foil production capacity from 3,700 metric tons to 6,700 metric tons.
The second expansion phase, currently under construction, will add annual capacity of 16,000 metric tons. Major equipment contracts have been finalized and manufacturing has begun. The company plans to accelerate equipment delivery schedules and start operating part of the new production lines in the second quarter of 2027, ahead of the original timetable, with full operations beginning in the fourth quarter.
The company also reported second-quarter consolidated revenue of 286.4 billion won and an operating loss of 9.2 billion won. Despite higher copper foil sales volumes and increased revenue from AI-focused high-end products, earnings remained in the red due to initial expansion costs and production stabilization expenses.
“Both pricing and demand are entering a more stable phase,” Chief Executive Officer Kim Yeon-seop said. “We believe a turnaround is only a matter of time and can be achieved in the near future.”
Chinese display maker Visionox is preparing a follow-on investment for its 8.6-generation OLED production line, with industry attention focused on whether South Korean equipment suppliers such as YAS can secure orders after missing out on the first phase.
According to industry sources on Aug. 6, Visionox is planning a second-phase investment for its V5 fab under construction in Hefei, Anhui Province. While the exact timing has not been finalized, the project is widely expected to begin in the first quarter of 2027.
The V5 facility is designed for a total production capacity of 32,000 glass substrates per month. The first phase covers 8,000 substrates per month, while the second phase will add the remaining 24,000 substrates per month—three times the size of the initial investment.
The first phase included equipment supplied by South Korean companies such as AP Systems, SynusTech and ICD. Applied Materials (AMAT) won the order for the deposition equipment, widely considered the most critical tool in the production line. The company began delivering equipment in May and is currently conducting installation, commissioning and process validation for Visionox's ViP technology, a fine-metal-mask (FMM)-less OLED manufacturing process. Yield rates on the line are reportedly in the 30–40% range.
Although both AMAT and YAS deposit organic materials onto substrates by heating solid organic emissive materials in a vacuum environment, their approaches differ significantly.
AMAT uses a vertical deposition architecture in which 8.6-generation glass substrates are positioned upright during processing. The system integrates deposition, substrate transfer and encapsulation processes within a connected vacuum environment. Maintaining uniform film thickness across large vertically transported substrates is a key technical challenge.
YAS, by contrast, employs a horizontal architecture in which substrates remain flat while organic materials are deposited from evaporation sources located beneath them. The system maintains a constant distance between the evaporation source and substrate to ensure uniform film formation across the entire panel. As a result, chamber structures, transfer systems and overall equipment configurations differ substantially from those used by AMAT.
AMAT benefits from operational data and process conditions accumulated from the first-phase V5 line. If Visionox selects the same equipment for the expansion, previously developed deposition recipes and process parameters can be reused. Adopting YAS equipment, however, would require fresh validation of both equipment performance and manufacturing processes because of the different substrate-handling architecture.
Commenting on the possibility of YAS participating in the second phase, a Visionox official said, "We are currently validating the AMAT equipment, but yields remain low and pricing is high. If we adopt YAS equipment, we would need to conduct new verification work, so there are many factors to consider."
Visionox had also previously considered applying the conventional FMM process to portions of the V5 line. In May last year, the company discussed introducing FMM deposition equipment from Japan's Canon Tokki and South Korea's Sunic System. However, it ultimately chose the ViP approach.
According to Visionox, the likelihood of reverting to FMM technology in the second phase remains low.
Asked whether poor yields on the initial ViP line could lead the company to reconsider FMM technology, a Visionox official said, "Even if yields do not meet expectations, there is almost no possibility of returning to the FMM method. If we were to go back to FMM, it would raise questions about the rationale behind the investment, and we do not know whether the Hefei government would approve such a move."
Visionox is expected to determine the supplier for the second-phase deposition equipment based on the results of equipment installation, commissioning and ViP process validation on the first production line.
For the first-phase investment, Visionox selected lithography equipment from Canon, excimer laser annealing (ELA) and laser lift-off (LLO) systems from AP Systems, plasma-enhanced chemical vapor deposition (PECVD) and sputtering equipment from Applied Materials, and certain sputtering tools from ULVAC. Dry etching equipment was supplied by Tokyo Electron and ICD, while logistics and material-handling systems for array and deposition processes were provided by SynusTech.
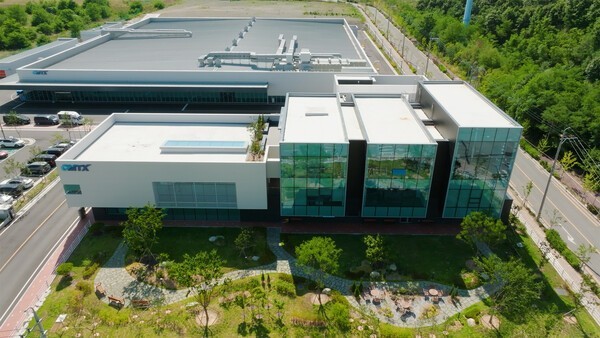
CMTX’s M Campus in Gumi, North Gyeongsang Province (Photo: CMTX)
CMTX’s M Campus in Gumi, North Gyeongsang Province (Photo: CMTX)
CMTX said through its shareholder communication platform that it has no plans to issue convertible bonds (CBs) or bonds with warrants (BWs), dismissing concerns raised after its recent extraordinary general meeting.
The company said amendments approved at the extraordinary shareholders’ meeting held on July 22 included the introduction of an independent director system in line with revisions to Korea’s Commercial Act, as well as an increase in the issuance limits for CBs and BWs. “We currently have no plans to issue CBs or BWs,” CMTX said.
Following shareholder approval, CMTX increased the issuance limit for both CBs and BWs to 50 billion won each from 10 billion won previously. The company said the move was intended as a preparatory measure to provide flexibility for future mergers and acquisitions (M&A) and strategic investment opportunities. It added that it currently holds approximately 90 billion won in cash and cash equivalents and has secured 100 billion won in available credit facilities from financial institutions, making external fundraising unnecessary at this time.
CMTX said that if it had been planning a large-scale issuance of CBs or BWs in the near future, it would have raised the limits by a substantially larger amount. The company described the amendments as a minimum-level revision designed to address potential future needs. It also emphasized that any future financing decisions would be made with the goal of minimizing dilution for existing shareholders.
The company also revised its articles of incorporation to reflect changes to the Commercial Act, including replacing outside directors with independent directors and increasing the required proportion of independent directors from at least one-quarter of the board to at least one-third.
Through its recently launched shareholder communication forum, CMTX said it plans to continue sharing key management information, including earnings analysis, investment and capacity expansion progress, new customer acquisition, and shareholder return policies.
HanWool Semiconductor on Aug. 6 unveiled its strategy for AI-based multilayer ceramic capacitor (MLCC) back-end manufacturing equipment, highlighting an ultrasound inspection system and a second-generation mounter capable of conducting high-speed, full-scale inspection of internal defects.
The company aims to expand its presence in automotive electronics and AI server markets by transforming MLCC inspection methods. As demand grows for high-reliability MLCCs, inspection requirements are extending beyond external appearance to internal structures and evolving from sample-based checks to high-speed, 100% inspection.
HanWool is developing an “AI-based ultrasound full inspection system” capable of non-destructively detecting microscopic cracks, delamination and voids inside MLCCs. The system combines AI-driven judgment technology with ultrasound signal analysis to overcome the limitations of conventional sample inspections while improving both inspection speed and reliability.
A key element of the strategy is the company’s proprietary deep-learning inspection platform, HaWAIe. The platform is designed to detect defects such as microcracks, chipping, electrode failures and foreign materials that are difficult to identify through visual inspection or rule-based algorithms. HanWool plans to expand its use beyond visual inspection equipment to ultrasound inspection systems and process automation equipment.
The company is also developing a second-generation mounter designed for high-value-added MLCC production. HanWool said the new system will improve production yield and throughput by more than 30% compared with existing equipment while supporting ultra-small MLCC products.
“The MLCC inspection market is rapidly evolving from simple visual inspection toward high-speed full inspection capable of identifying internal defects,” a HanWool Semiconductor official said. “Through commercialization of our AI ultrasound inspection system and second-generation mounter, we aim to secure a leading position in the market for high-value MLCC manufacturing equipment.”
Simmtech reported a sharp increase in second-quarter earnings as sales of package substrates for artificial intelligence semiconductors continued to expand.
The company disclosed on Aug. 5 that it recorded consolidated revenue of 514.6 billion won and operating profit of 62.9 billion won for the second quarter.
Compared with the same period last year, revenue increased 51.0% while operating profit surged 1,034.4%, more than elevenfold. On a sequential basis, revenue rose 21.8% and operating profit increased 358.7%.
For the first half of 2026, Simmtech posted cumulative revenue of 936.9 billion won and operating profit of 76.6 billion won.
The company's operating margin reached 12.2% in the second quarter, up 10.6 percentage points from a year earlier and 9.0 percentage points from the previous quarter.
Net profit totaled 44.9 billion won, compared with a net loss in the year-earlier period, marking a return to profitability.
Simmtech expects growth to continue in the second half of the year.
In a separate disclosure, the company forecast second-half consolidated revenue of 1.0719 trillion won and operating profit of 163.1 billion won. The projected operating profit exceeds the company's first-half operating profit by more than two times.
The company said demand for system IC package substrates is expected to remain strong, while sales of products for SOCAMM are set to expand in earnest.
As a result, the proportion of high-value-added products used in AI applications is expected to increase further during the second half of the year.
Taiwan-based GlobalWafers has formally acknowledged growing supply shortages in the silicon wafer market, signaling a potential shift toward higher wafer prices as demand from artificial intelligence and advanced semiconductor applications accelerates.
During its second-quarter earnings conference call on Aug. 4, GlobalWafers said supply-demand imbalances are already emerging across the semiconductor wafer industry.
"The supply-demand imbalance in the wafer industry is already underway," the company said. "Our 12-inch (300mm), 8-inch (200mm) and 6-inch (150mm) production lines are effectively operating at full utilization, and supply constraints have already appeared for certain advanced 12-inch products."
The company attributed the tightening market to rapidly growing demand from AI semiconductors, high-bandwidth memory (HBM), silicon photonics and advanced packaging technologies.
GlobalWafers said both memory and logic chip manufacturers are increasingly seeking to secure long-term production capacity, turning potential shortages into a reality.
Similar trends are emerging across the broader wafer industry.
German wafer supplier Siltronic said during its earnings announcement on July 30 that inventory levels at memory and logic customers have normalized and customers have begun rebuilding safety stock inventories.
The company added that inventory replenishment is expected to further increase wafer demand and that requests for 300mm wafers are coming not only from existing customers but also from new ones.
Industry leader Shin-Etsu Chemical reported on July 24 that shipments of 300mm wafers increased by double-digit percentages both year over year and sequentially.
Japanese wafer manufacturer SUMCO also indicated in May that customer inventory adjustments were approaching completion.
South Korea's SK Siltron has been expanding production capacity through the phased startup of new facilities, but industry sources said demand growth is outpacing those additions.
The structure of long-term agreements (LTAs) is also changing.
Historically, LTAs were primarily designed to ensure stable wafer supplies for customers. Increasingly, however, they are being used as tools to secure future manufacturing capacity in anticipation of supply shortages.
Contract durations are also lengthening, with agreements increasingly extending from the traditional three-year range to five to eight years.
Last month, GlobalWafers signed a 10-year LTA with Micron, one of the longest agreements in the wafer industry's history. The contract, which begins next year, includes strategic financial support in the form of upfront payments.
The company said most of its revenue in the second half of this year and the first half of next year is expected to come from LTAs.
Shin-Etsu Chemical has stated that all of its 300mm wafer shipments are currently supplied under LTAs. Siltronic said roughly two-thirds of its shipments are sold through similar agreements.
Some memory customers are already requesting supply allocations for two to three years into the future.
Signs of pricing pressure are also emerging.
As supply tightens, prices in the spot market have started rising ahead of contract prices.
Siltronic said prices for non-LTA 300mm wafers have begun increasing, while GlobalWafers expects spot prices in the second half of 2026 to be higher than in the first half.
The industry expects price increases to eventually spread to long-term contracts as well.
GlobalWafers said it is discussing price increases with customers to reflect higher costs for raw materials, energy, logistics and labor.
"Existing LTAs will maintain their contracted prices, but future agreements will incorporate pricing mechanisms that reflect market conditions, product mix changes and industry developments," the company said.
Siltronic echoed the view, stating that prices must recover to levels that justify reinvestment as some LTAs come up for renegotiation in 2027 and 2028.
"We need broad and meaningful price increases," the company said.
The wafer industry has spent the past two years coping with shipment declines and pricing pressure after customer inventories surged beginning in 2023.
That trend began to reverse in late 2025 as inventories of 300mm wafers declined and inventory coverage levels fell further during the first quarter of this year, signaling the end of the industry's inventory correction cycle.
Many suppliers now view the second quarter of 2026 as the beginning of a new upcycle.
Industry participants expect supply shortages and price increases to become more pronounced from the second half of 2027.
Current shipment growth is being supported by higher utilization rates at existing semiconductor fabs. However, once new memory facilities being built by Samsung Electronics, SK hynix and Micron begin production, wafer demand could roughly double from current levels.
iVisionWorks is developing a semiconductor wafer inspection system. (Photo: KLA)
iVisionWorks is developing a semiconductor wafer inspection system. (Photo: KLA)
Machine vision inspection system company iVisionWorks has begun developing semiconductor wafer inspection equipment, the company announced on Aug. 5.
The new system will be a wafer metrology and inspection platform built on a high-sensitivity optical architecture. The market is currently dominated by overseas suppliers such as KLA and Hitachi High-Tech. iVisionWorks said it aims to develop a product that can compete on both defect detection capability and inspection speed.
The company plans to complete proof-of-concept (PoC) testing in the second half of this year and finish a prototype in the first half of next year. The prototype will then be used for customer evaluations.
Wafer inspection systems are used to identify defects generated during semiconductor manufacturing processes. Their performance has a significant impact on production yield and manufacturing efficiency.
Demand for wafer inspection equipment has been rising rapidly as the global expansion of artificial intelligence drives increased semiconductor production.
According to market research firm Fortune Business Insights, the global semiconductor defect inspection equipment market was valued at approximately $6.14 billion in 2025 and is projected to reach about $13.41 billion by 2034.
"We are concentrating our company-wide capabilities on entering the semiconductor inspection equipment market," said Gil Gi-jae, Chief Executive Officer of iVisionWorks.
"The semiconductor inspection equipment market has high technological barriers to entry, but we intend to leverage our accumulated precision optical technologies to establish a position in the sector and secure a new growth momentum," he added.
iVisionWorks currently supplies machine vision inspection equipment for secondary battery manufacturing processes.
Machine vision systems are automated measurement and identification platforms that combine optical hardware, software and image-processing technologies to inspect products and manufacturing processes.
Apple in China occupies a position unlike the company’s presence in any other country. China is simultaneously a major consumer market, a critical manufacturing center, an extensive developer economy and the home of Apple’s most determined hardware competitors.
That combination creates an opportunity few technology companies can ignore. China has hundreds of millions of affluent mobile users, a strong appetite for premium devices and a digital economy built around smartphones.
It also creates unusual complexity. Apple must compete with Huawei, Xiaomi, Oppo and Vivo while satisfying Chinese regulations, navigating tensions between Beijing and Washington and reducing its manufacturing dependence without damaging the supplier network that helped make the iPhone possible.
The latest market figures show why Apple cannot treat China as a business it has already lost. IDC estimated that Apple captured 18.1 percent of Chinese smartphone shipments during the second quarter of 2026, placing it second behind Huawei at 22.6 percent.
Apple’s shipments increased by 24.4 percent from the previous year even as the wider Chinese smartphone market contracted. The recovery demonstrated that Chinese demand for the iPhone remains substantial when product design, storage, performance and pricing align with consumer expectations.
The same figures also show why the position can never be considered secure. Huawei remains ahead, local brands respond quickly and a few percentage points can separate several major vendors.
Apple in China Still Has Room to Grow
China is already one of Apple’s largest markets, but its scale means that even established product categories contain room for expansion.
The country has a large premium smartphone segment, extensive 5G coverage and consumers accustomed to using mobile devices for communication, payments, shopping, entertainment, transport and work.
An iPhone purchase can also lead to AirPods, Apple Watch, iPad, Mac, iCloud storage and paid applications. The commercial opportunity is therefore larger than the initial handset transaction.
Apple’s strongest advantage is its integrated ecosystem. An iPhone can share passwords, photographs, messages and files with a Mac or iPad, while AirPods and Apple Watch extend the experience without requiring separate accounts and setup systems.
That continuity becomes more valuable as households accumulate devices. Replacing one iPhone is relatively easy. Leaving an ecosystem containing several products, purchased applications, cloud storage and shared family services involves greater friction.
Apple also benefits from a premium identity that remains recognizable in China. Local manufacturers now produce sophisticated flagship phones, but the iPhone continues to operate as both a personal computer and a luxury consumer product.
The importance of that status should not be exaggerated. Chinese buyers are technically informed and increasingly willing to support domestic brands. Brand recognition can attract attention, but it does not excuse weak features or an uncompetitive product cycle.
Recent iPhone Demand Shows the Opportunity
Apple’s 2026 recovery offers a useful example of how quickly its position can improve.
China’s smartphone shipments fell 4.3 percent during the second quarter as memory and component costs pushed several manufacturers toward higher prices. Apple and Huawei held prices more stable, giving buyers a reason to purchase while competing brands became more expensive.
The iPhone 17 generation also addressed several areas where Apple’s standard models had appeared conservative beside Chinese flagships. Stronger base specifications made the regular iPhone more competitive without requiring every customer to move into the Pro tier.
This matters in a market where consumers compare display technology, camera systems, storage, battery life, charging and AI features closely. Apple cannot depend entirely on iOS loyalty when domestic companies introduce visible hardware improvements at several price levels.
The rebound does not establish a permanent trend. Smartphone demand in China remains affected by economic confidence, upgrade cycles, government incentives and the timing of major shopping festivals.
Apple’s position can also look different according to the research firm and whether a report measures shipments or consumer sales. Quarterly rankings should be treated as evidence of momentum rather than a final judgment on the market.
The important signal is that Chinese consumers have not broadly rejected the iPhone. Demand can return rapidly when the product and price create a convincing upgrade.
Huawei Makes China Apple’s Hardest Market
Huawei gives Apple a competitor with advantages unavailable to most global smartphone manufacturers.
The company combines strong national recognition with advanced cameras, communications technology, custom chips, local services and an expanding HarmonyOS ecosystem. Its return to premium smartphones removed the opening Apple had gained when U.S. restrictions disrupted Huawei’s access to important components.
Huawei can also position its products as part of China’s technological self-reliance. That message carries commercial and political weight beyond a conventional comparison between two phones.
Apple must therefore compete against product quality and national sentiment simultaneously. An iPhone can offer strong performance and still lose a purchase to a domestic flagship viewed as technically capable and strategically important.
Xiaomi, Oppo and Vivo add different pressures. They move quickly across price categories, experiment with folding designs, adopt larger batteries and provide features adapted to local applications and buying habits.
Chinese phone makers also operate inside a retail and software environment they understand directly. They can build relationships with local platforms, carriers and commerce services without translating a global strategy into Chinese requirements.
Apple follows a more centralized product model. That consistency protects the identity of the iPhone, but it can make the company slower to answer features gaining popularity inside one country.
Services Depend on Local Rules
Apple in China is not only an iPhone business. The installed device base creates demand for applications, cloud storage, entertainment, subscriptions and digital purchases.
China has an enormous developer community producing games, commerce platforms, social services, education tools and productivity software. The App Store connects those developers with high-value iPhone and iPad customers.
The relationship is commercially important but politically complicated. Apple must operate the mainland App Store according to Chinese law, including rules affecting games, generative AI, communications services and content.
Applications available elsewhere may be absent from the Chinese storefront. Developers may also need licenses or regulatory approval before distributing certain categories of software.
Apple changed commission rates and related policies for the mainland China storefront in March 2026. The company described the adjustments as part of maintaining a strong business opportunity for Chinese developers.
Regulatory and developer pressure has not disappeared. Complaints involving commissions, distribution restrictions and payment policies continue to challenge Apple’s control of the platform.
The company cannot simply copy its response from another region. European rules focus heavily on alternative marketplaces and interoperability, while China combines competition concerns with content regulation, data localization and licensing requirements.
Every concession must therefore be designed for a distinct legal environment without fragmenting iOS into an unmanageable collection of regional systems.
China Is Also Part of the Product
Apple’s relationship with China extends far beyond the devices sold there.
For more than two decades, Apple and its manufacturing partners built a dense network of factories, component suppliers, engineers, logistics operators and toolmakers across the country.
That network does more than provide low-cost labor. It can place specialists from several suppliers near an assembly site, modify production lines quickly and increase output to enormous volumes during a product launch.
China’s infrastructure also supports the less visible stages of manufacturing. Components require precision tooling, testing equipment, chemicals, packaging, subassemblies and experienced quality-control teams before final assembly begins.
Apple has expanded iPhone production in India and moved parts of its Mac, iPad, Apple Watch and AirPods supply chains to countries including Vietnam. It is also increasing semiconductor and component commitments in the United States.
Those investments reduce the danger of relying on one country, but they do not recreate China’s complete manufacturing environment immediately.
A factory in another region may assemble an iPhone while still depending on Chinese machinery, materials, subcomponents or engineering support. Production diversification is therefore a gradual redistribution of individual stages rather than a clean departure.
Apple must reduce concentration risk without weakening the manufacturing system responsible for its product quality, scale and launch schedules.
Image Credit: AFP Photo
Trade Tensions Turn Efficiency Into Risk
The same China supply chain that provides Apple with extraordinary efficiency also exposes the company to political decisions outside its control.
Tariffs can raise the cost of devices exported from Chinese factories. Export restrictions can limit access to materials or production equipment, while sanctions may affect suppliers and technology partners.
Chinese government policies can influence the use of foreign devices inside state agencies and companies. U.S. rules can restrict the technologies available to Chinese firms that also participate in Apple’s supplier network.
Apple cannot solve these problems through product design alone. It must maintain relationships with two governments whose technology policies increasingly emphasize security, domestic production and strategic independence.
Moving more assembly to India gives Apple additional flexibility, particularly for iPhones destined for the United States. China nevertheless remains important as a production center and consumer market.
An aggressive withdrawal could damage supplier relationships and local sales. Moving too slowly could leave Apple vulnerable to another trade disruption.
The company is trying to preserve Chinese capabilities while creating enough capacity elsewhere to keep a political dispute from becoming a worldwide product shortage.
Retail Stores Give Apple a Direct Relationship
Apple’s physical stores remain an important advantage in China because they give the company direct contact with customers.
The stores allow buyers to compare models, receive technical support, attend educational sessions and enter the ecosystem without depending entirely on a carrier or reseller.
That experience is particularly valuable for premium products. A customer considering a Mac, Apple Vision Pro or high-end iPhone may need more explanation than someone replacing an inexpensive handset.
Retail locations also communicate long-term commitment. A prominent store represents more than a sales channel; it signals that Apple intends to remain part of the local technology market.
Online commerce is equally important. Chinese consumers are accustomed to large shopping festivals, aggressive promotions and rapid delivery through domestic platforms.
Apple must balance its controlled global pricing with a market where discounts can change quarterly rankings. Too little flexibility makes the iPhone appear expensive, while frequent reductions can train customers to delay purchases and weaken its premium image.
The strongest 2026 performance came partly from avoiding price increases while component costs were forcing rivals to reconsider their pricing. That advantage may disappear when competitors adjust their supply chains or launch another cycle of promotions.
Chinese Consumers Set a Higher Product Standard
China is often discussed as a sales problem for Apple, but it also functions as a demanding test of the iPhone.
Domestic flagship phones compete through larger batteries, rapid charging, advanced camera hardware, folding displays and deep integration with local digital services.
Features considered experimental elsewhere can become established expectations more quickly in China. Apple’s slower adoption cycle may look disciplined in one market and conservative in another.
The company must decide which expectations represent durable improvements and which are temporary specification contests. Copying every local feature would weaken Apple’s focused product strategy, but ignoring major changes creates openings for rivals.
This pressure can benefit Apple globally. Competition in China forces the company to defend the value of its standard iPhone, improve battery efficiency, strengthen cameras and make software features more useful outside English-speaking markets.
The opportunity is therefore not limited to selling more devices. China can reveal where Apple’s global assumptions no longer match the most competitive part of the smartphone industry.
Daeduck Electronics' flip-chip ball grid array (FC-BGA) manufacturing facility at its headquarters.
Daeduck Electronics' flip-chip ball grid array (FC-BGA) manufacturing facility at its headquarters.
Daeduck Electronics reported record quarterly results as demand for semiconductor substrates used in artificial intelligence (AI) servers and data centers continued to expand. Operating profit surged 3,599% from a year earlier.
The company said on July 31 that it posted consolidated revenue of 401.0 billion won and operating profit of 70.3 billion won for the second quarter of 2026. Revenue increased 63% year over year, while operating profit jumped 3,599%. Compared with the previous quarter, revenue rose 16% and operating profit increased 37%.
Operating margin reached 17.5%, up 2.7 percentage points from 14.8% in the first quarter.
Growth was driven by higher sales of high-value semiconductor substrates for AI and data center applications.
"Performance continued to improve on the back of growing demand for high-performance semiconductors in AI and data center markets and strengthened business competitiveness," the company said.
Revenue from the company's core package substrate (PKG) business reached 343.5 billion won, up 65% from a year earlier and 18% from the previous quarter. Demand increased for controllers, optical modules and networking products used in AI data centers. Sales of automotive radar and advanced driver assistance system (ADAS) products also expanded. Improved product mix, higher productivity and favorable foreign exchange rates contributed to profitability.
Revenue from the multilayer board (MLB) business totaled 57.5 billion won, rising 53% year over year and 4% sequentially. The company began mass production of next-generation AI products and saw increased sales for semiconductor inspection equipment and electronic design automation (EDA) applications. Demand for high-margin products in aerospace and defense markets also remained stable.
The company's revenue mix continued to shift toward AI-related products. Flip-chip ball grid array (FC-BGA) substrates accounted for 26% of revenue, up from 23% in the previous quarter. Flip-chip chip-scale package (FC-CSP) products represented 48% of revenue, compared with 46% in the prior quarter, reflecting stronger sales of high-value products for AI servers and data centers.
By contrast, the share of memory-related chip-scale package (CSP) products—including NAND flash, low-power DRAM (LPDDR5), SOCAMM and Compute Express Link (CXL) products—declined to 23% from 25%.
Daeduck Electronics expects growth to continue in the third quarter. The company plans to expand mass production of large-area substrates for AI data centers and accelerate new product development. It also aims to address growing demand for high-performance networking products and physical AI-related applications.
Sunic System's Suwon headquarters. (Photo: THE ELEC)
Sunic System's Suwon headquarters. (Photo: THE ELEC)
Sunic System said it will expand financial support for its partner companies following an upgrade to its corporate credit rating.
The company announced on July 31 that it recently received an A+ credit rating from a state-owned bank, a level it described as the highest available for mid-sized companies.
Sunic System said the evaluation reflected its stable financial structure, business performance and competitiveness in the global organic light-emitting diode (OLED) deposition equipment market. The assessment also took into account the company's efforts to develop next-generation businesses, including OLEDoS and perovskite technologies, as well as plans to expand its production infrastructure.
The company added that its ratings from major credit assessment agencies have also improved compared with the previous year.
Based on the upgraded credit profile, Sunic System has launched a financing support program for its suppliers. The company will recommend partner firms requiring facility investment or working capital financing to the Korea Credit Guarantee Fund (KODIT). Recommended firms receive preferential treatment when raising funds from financial institutions through KODIT's preferential guarantee program for partner companies.
Sunic System said it is the first case in which a general mid-sized company, excluding defense firms, has used KODIT's preferential guarantee program for partner companies to arrange financing support for its partners.
Tesla is asking a federal judge for emergency access to a supplier’s plant in Troy, Texas, so it can haul out the tooling it needs to keep building the Cybertruck.
The supplier, Angstrom Automotive Group, is closing the plant and won’t let Tesla in. Tesla says that without those dies, several thousand Cybertrucks already committed to customers don’t get built.
MacBook Neo helped Apple move against the global PC market in the second quarter of 2026, delivering double-digit Mac shipment growth while most leading computer manufacturers sold fewer units than a year earlier.
Preliminary data from IDC estimates that Apple shipped 6.7 million Macs during the quarter, up 10.1% from 6.1 million in Q2 2025. Its worldwide market share rose from 8.5% to 9.9%, placing the company within a fraction of the 10% threshold.
The rest of the industry moved in the opposite direction. Global shipments fell 4.9% year over year to 68.2 million units, ending nine consecutive quarters of growth. A separate Omdia estimate placed the decline at 3.6% and Apple growth at 15.9%, but both research groups identified the same pattern: the Mac gained ground while established Windows PC vendors contracted or remained flat.
IDC directly connected the Apple increase with the arrival of its lowest-priced notebook. MacBook Neo began shipping in March, giving the model its first complete quarter of retail availability between April and June.
MacBook Neo Drives Mac Shipment Growth
MacBook Neo entered the market as an alternative for buyers previously priced out of the Mac lineup.
The 13-inch notebook launched at $599 with an A18 Pro chip, 8GB of unified memory, a Liquid Retina display and up to 16 hours of video playback. It also brought macOS, Apple Intelligence and integration with the iPhone ecosystem into a price range commonly occupied by mainstream Windows laptops and Chromebooks.
That positioning attracted students, families and first-time Mac customers who did not need the performance or display technology of a MacBook Air or MacBook Pro. The four-color aluminum design also gave the entry model a more recognizable identity than the older Mac notebooks that frequently remained on sale through discounts.
IDC had already identified the computer as an unusual source of strength when it revised its notebook forecast earlier in 2026. Demand exceeded initial expectations in several markets, and reported inventory shortages appeared shortly after the March launch.
The effect became much more visible in Q2. MacBook Neo was available for the entire three-month period, allowing Apple to increase production, expand retail distribution and serve customers who could not obtain the computer during its first weeks.
The entry model also widened the Mac lineup without replacing the MacBook Air. Buyers seeking more memory, faster ports, longer wireless web use or additional external-display support could continue moving toward the M5-powered Air, while the less expensive machine handled education, office work, web browsing and communication.
That separation allowed Apple to reach lower price points without reducing the value of its premium notebooks.
Image Credit: Apple Inc.
Lenovo, HP and Dell Lose Shipments
Apple remained the fourth-largest traditional PC vendor, but its performance contrasted sharply with the companies above it.
Lenovo retained first place with 16.6 million units and 24.4% market share. Its shipments declined 2.1% from the previous year.
HP experienced the steepest drop among the top five, falling 9% to 13 million units. Dell shipped 9.3 million computers, representing a 5% decline. Asus remained nearly flat at 5 million units, up only 0.2%.
Manufacturers outside the five largest brands collectively suffered a 10.5% contraction, indicating that weaker demand and component inflation placed even more pressure on smaller companies.
The figures measure shipments into distribution channels or directly to end users, not confirmed retail purchases by individual consumers. A manufacturer can therefore record shipment growth while some inventory remains unsold in stores or warehouses.
MacBook Neo demand appears to have been strong enough to support Apple production increases rather than simply filling channels. The company reportedly doubled its annual production target after the initial response, although later quarters will reveal how much of Q2 reflected lasting demand rather than launch-period enthusiasm.
Apple also benefits from operating at a scale that provides leverage with memory, storage and semiconductor suppliers. Smaller PC brands face greater difficulty securing components at competitive prices when shortages intensify.
Memory Costs Reverse the PC Recovery
The Q2 contraction arrived after manufacturers and commercial customers accelerated purchases during late 2025 and early 2026.
Buyers expected memory and storage prices to rise, encouraging some businesses to replace computers earlier than planned. Vendors also increased inventories while components remained available.
That activity supported nine quarters of market growth but borrowed demand from later periods. Once the early purchases were completed, the industry faced a more difficult combination of expensive components, cautious consumers and elevated retail prices.
The memory shortage is closely connected to the AI infrastructure boom. Chipmakers are dedicating more production capacity to high-bandwidth memory used by data center accelerators, limiting the supply of conventional DRAM needed for personal computers.
IDC expects little relief before the end of 2027 or early 2028. The research company forecasts an 11.3% decline in worldwide PC shipments across 2026, with the fourth quarter potentially falling 20% from the previous year.
Computer revenue may not decline at the same pace. Manufacturers have raised prices faster than shipments have fallen, allowing them to collect more money from fewer units.
That strategy creates another problem. Retailers and distributors can become trapped with expensive inventory if customers refuse the new prices, forcing promotions or production reductions later.
MacBook Neo initially softened that pressure by giving Apple a new product near the bottom of the notebook market. Its original $599 price made the Mac competitive with midrange Windows machines at the moment many rivals were becoming more expensive.
Image Credit: Freepik
The Price Increase Creates the Next Test
The strongest Q2 MacBook Neo shipments were recorded while most customers could still buy the computer at its introductory price.
Apple raised the U.S. starting price to $699 in late June as memory and storage costs affected the Mac and iPad lineups. The education price remained at $599, preserving the original offer for eligible students and educators.
A $100 increase changes the comparison with discounted Windows notebooks and places the entry model closer to older MacBook Air configurations available through third-party retailers.
Apple must now determine whether the appeal came primarily from the low launch price or from the combination of macOS, battery life, design and iPhone integration.
The company remains better positioned than many rivals to absorb supply disruption, negotiate long-term component agreements and promote several notebooks at different prices. MacBook Neo also uses an iPhone-class A18 Pro processor rather than an M-series chip, providing another way to manage silicon costs and production capacity.
IDC expects the full PC market to deteriorate during the second half of 2026. Apple will enter that period with almost 10% worldwide share, but the September quarter will be the first to measure MacBook Neo demand almost entirely at the higher $699 retail price.

 Login