Apple today
announced financial results for its third fiscal quarter of 2026, which corresponds to the second calendar quarter of the year.
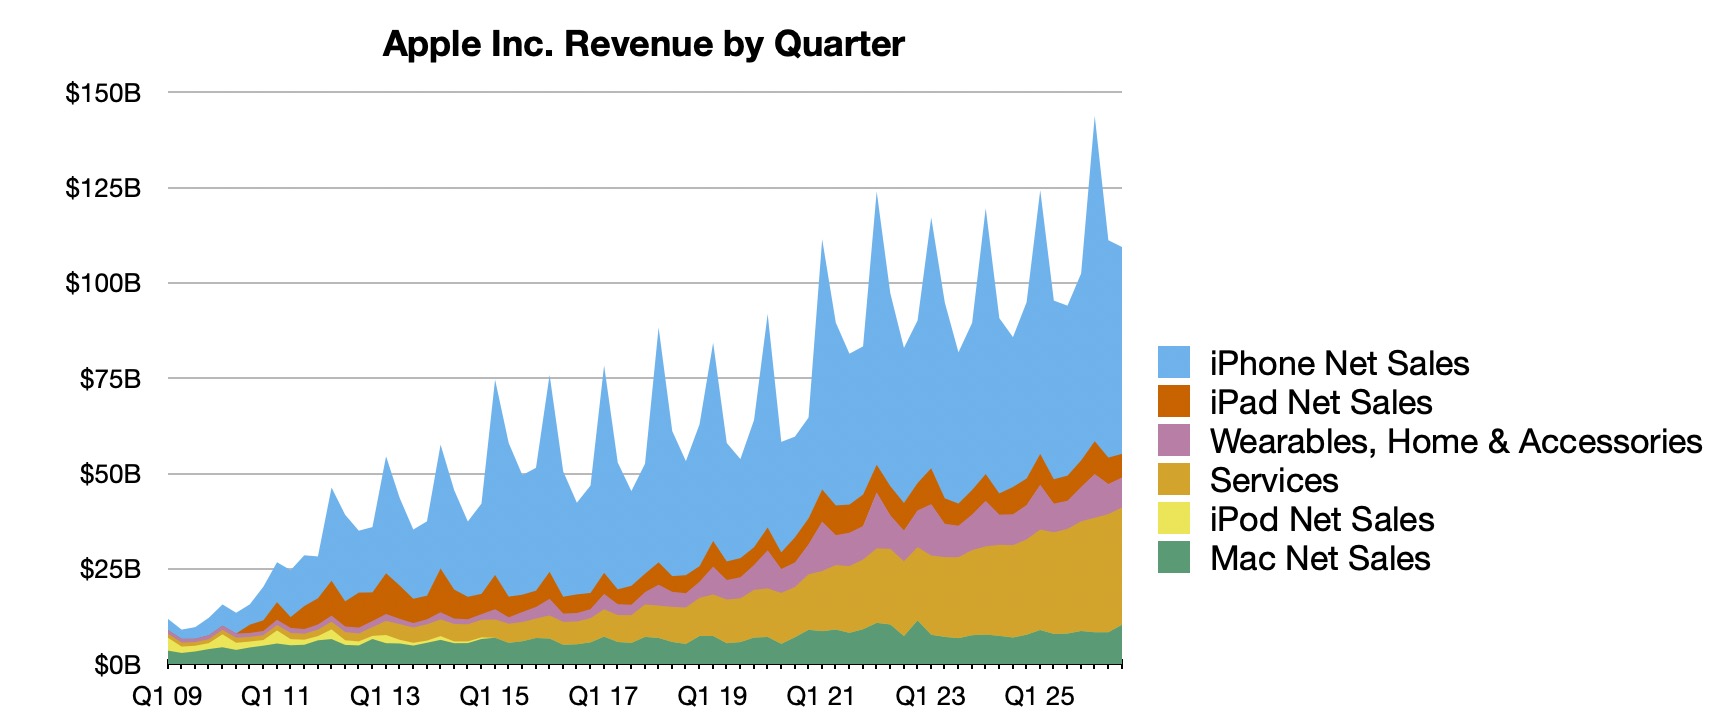
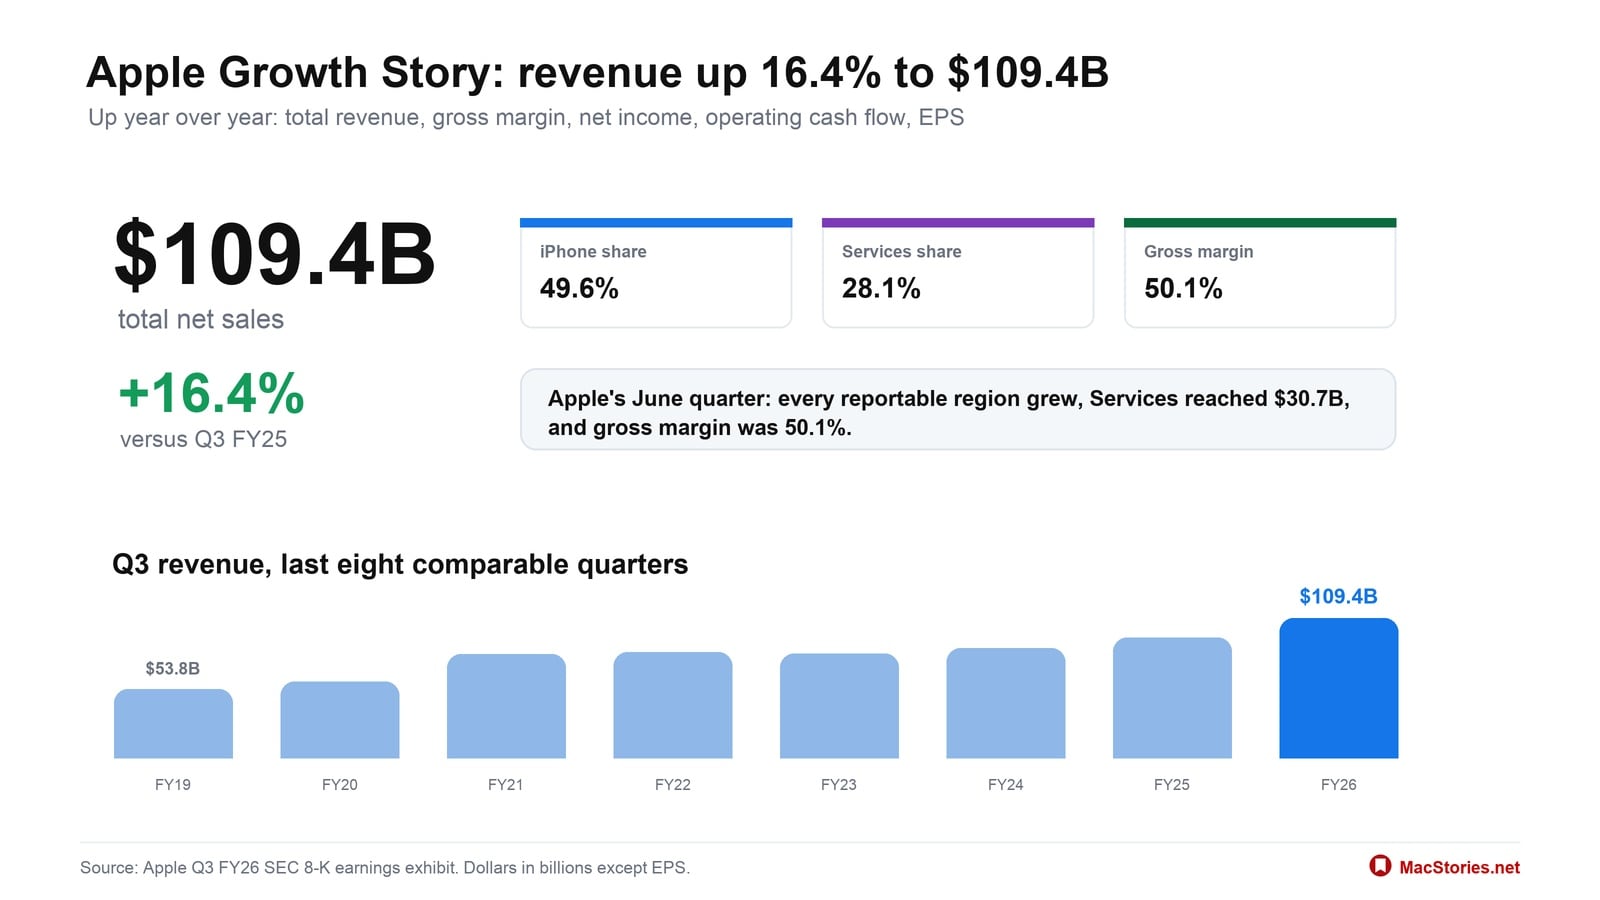
For the quarter, Apple posted revenue of $109.4 billion and net quarterly profit of $29.8 billion, or $2.02 per diluted share, compared to revenue of $94.0 billion and net quarterly profit of $23.4 billion, or $1.57 per diluted share, in the
year-ago quarter.
Apple set new June quarter records for total revenue and earnings per share, as well as for iPhone, Mac, and Services revenue.
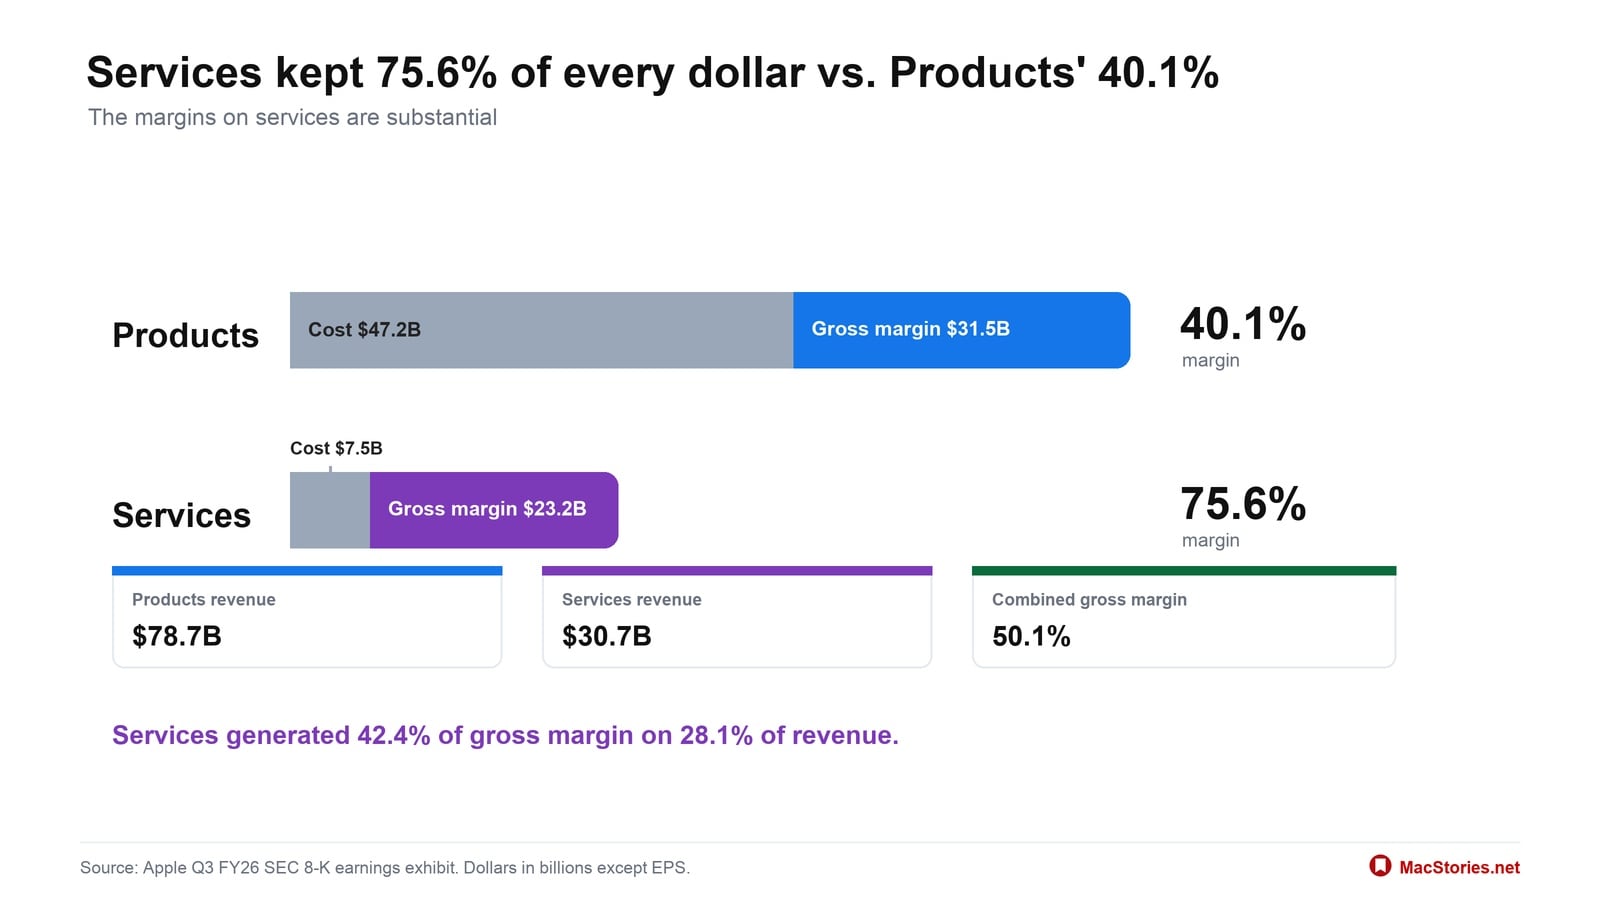
Gross margin for the quarter was 50.1 percent, compared to 46.5 percent in the year-ago quarter. Apple also declared a quarterly dividend payment of $0.27 per share, payable on August 13 to shareholders of record as of August 10.
"Today, Apple is proud to report our strongest June quarter ever, with double-digit revenue growth across iPhone, Mac and Services, and in every geographic segment," said Tim Cook, Apple's CEO. "At WWDC26, we were thrilled to introduce the all-new Siri AI, alongside all of Apple's latest software innovations and important new child safety features."

Apple will
provide live streaming of its fiscal Q3 2026 financial results conference call at 2:00 p.m. Pacific, and
MacRumors will update this story with coverage of the conference call highlights.
Conference call recap ahead...
1:38 pm: "We are very pleased with our record business performance during the quarter, which set new June quarter records for both EPS and operating cash flow," said Kevan Parekh, Apple's CFO. "Our installed base of active devices also reached a new all-time high across all major product categories and geographic segments."
1:39 pm: After declining around 1.4% in regular trading today, Apple's share price is currently down another 2.5% in after-hours trading following the earnings release.
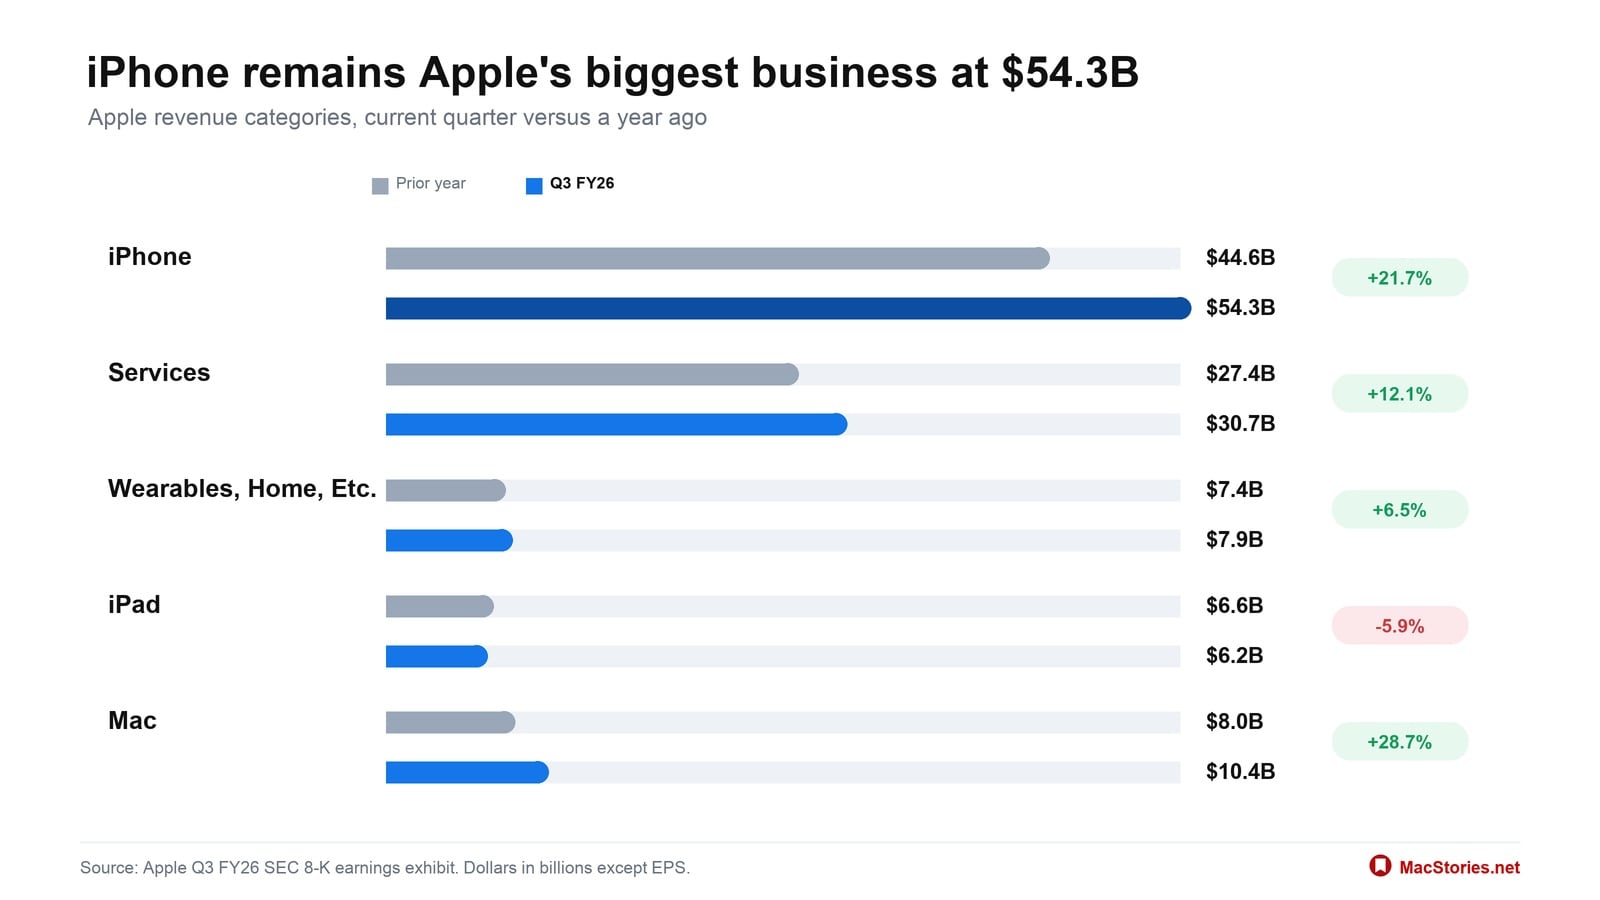
1:42 pm: Mac revenue was up 28.7% year-over-year, while iPhone revenue was up 21.7%, Services revenue was up 12.1%, and Wearables, Home and Accessories revenue was up 6.5%. The only product segment that saw a year-over-year decline was
iPad, which was down 5.9%.
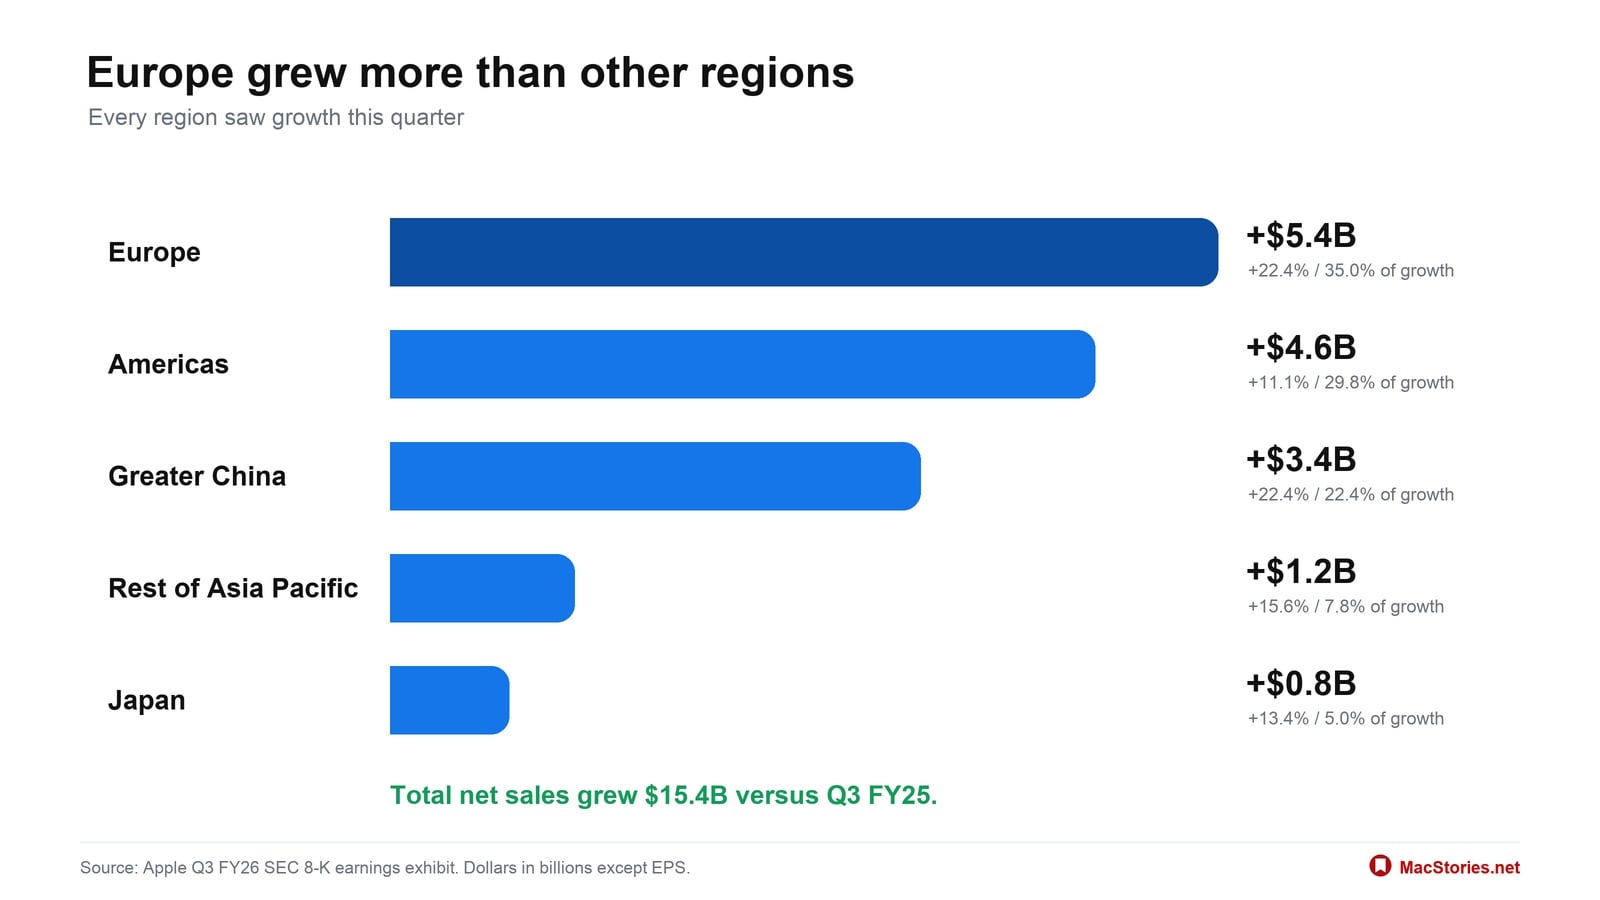
1:45 pm: Looking at Apple's geographic segments, Europe and Greater China each saw a 22.4% increase in revenue, Japan was up 13.4%, and the Americas had an 11.1% increase. The Rest of Asia Pacific outside of Greater China and Japan had a 15.6% increase.
1:55 pm: Apple's stock price is now down nearly 4.5% in after hours trading, just minutes before
Tim Cook's final quarterly earnings call as CEO.
2:01 pm: The call is now beginning with the standard warnings about forward-looking statements from Suhasini Chandramouli, Apple Investor Relations chief. On the call is CEO Tim Cook, CFO Kevan Parekh, and, for the first time, incoming CEO John Ternus.
2:02 pm: "Good afternoon everyone, and thanks for joining the call. Today, Apple is pleased to report $109.4 billion in revenue, up 16% from a year ago and a June quarter record."
2:03 pm: The company had supply constraints and foreign exchange headwinds, but still reached the record.
2:03 pm: "We achieved June quarter records in every geographic segment... We achieved June quarter records in both developed and emerging markets."
2:04 pm: Tim is going over the announcements from WWDC, including and especially
Siri AI. "The reviews from early users have been phenomenal."
2:04 pm: "We are feeling incredibly enthusiastic about the impact it's going to have."
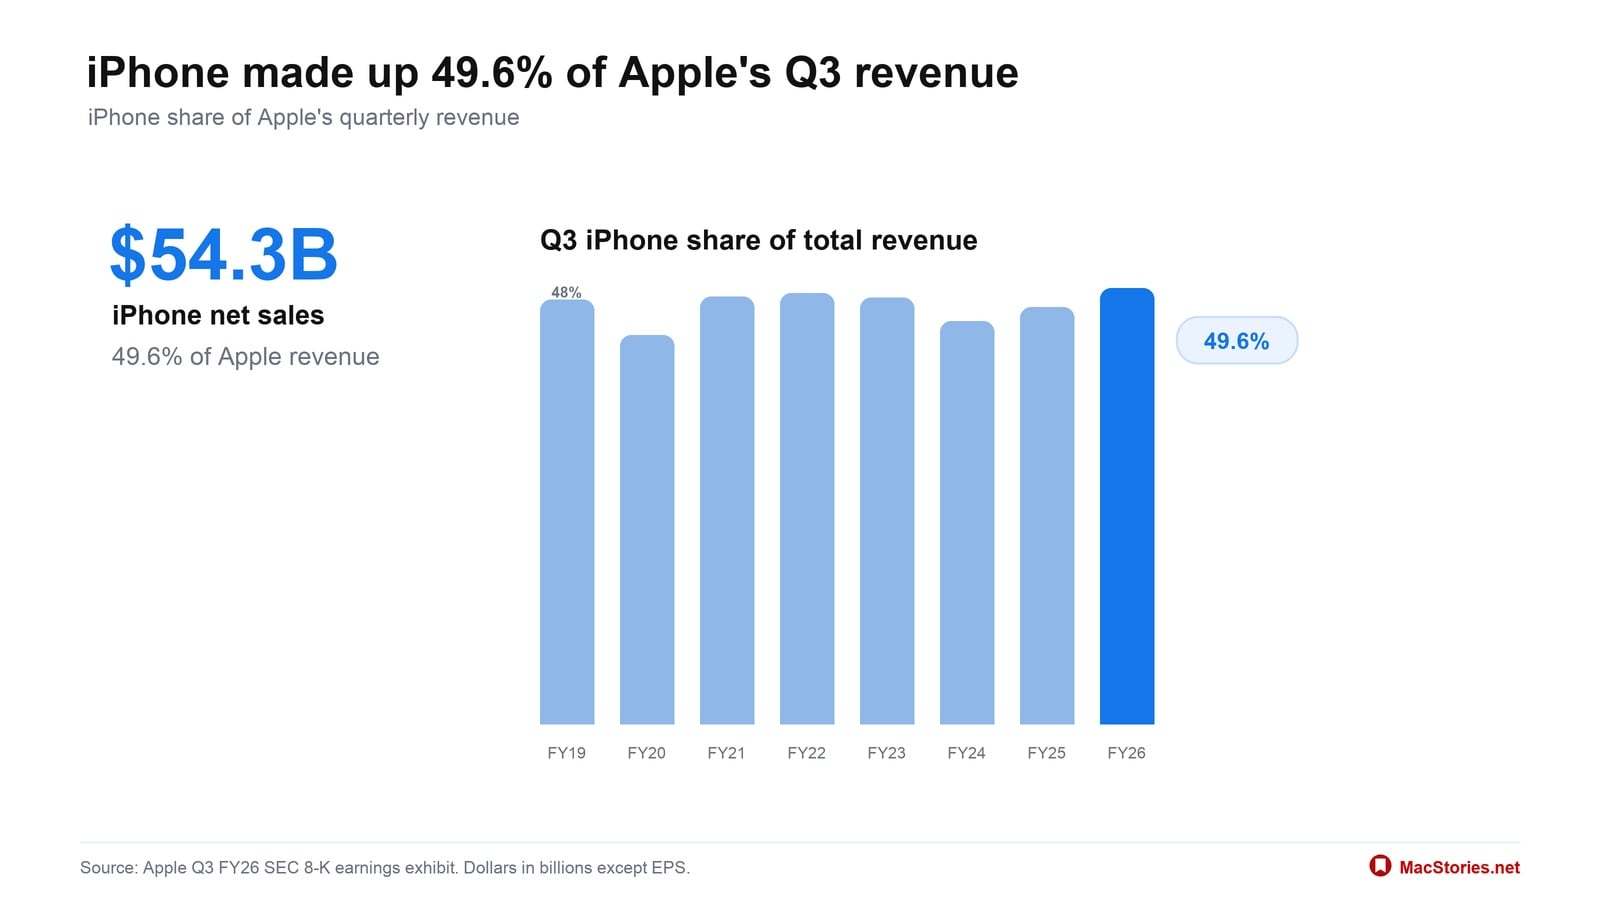
2:06 pm: Starting with iPhone, revenue was $54.3 billion, up 22% from last year. It was a June quarter record across every geographic segment and a record for upgraders. IDC says the company gained share globally during the quarter. "This is the most popular iPhone lineup we've ever had."
2:07 pm: Mac delivered its best June quarter yet, with $10.4 billion in revenue, up 29% from last year despite significant supply constraints. Driven by
MacBook Pro and
MacBook Neo. IDC says the company gained share globally and set a June quarter revenue record in developed markets and an all-time record in emerging markets, with particular strength in Greater China.
2:07 pm: "The Mac lineup delivers outstanding power-efficient performance, massive memory bandwidth, and next-level AI capabilities."
2:08 pm: MacBook Neo has been especially popular, with its distinctive design and excellent value resonating with customers around the world.
2:09 pm: iPad revenue was $6.2 billion for the June quarter. The addition of M4 to
iPad Air "has made it even more capable, delivering a significant performance boost."
2:09 pm: Revenue for Wearables, Home and Accessories was $7.9 billion, up 6% from a year ago, growing in every geographic segment.
2:10 pm: "We continue raising the bar across our AirPods lineup... with Live Translation powered by
Apple Intelligence, people are crossing language barriers and connecting like never before."
2:11 pm: "We began laying the groundwork for users to have the best possible experience with AI when we introduced a neural engine in 2017... Ever since then, we've innovated and invested deliberately in silicon systems and scalable unified memory architecture designed with AI at their core."
2:12 pm: "Apple has created the world's best hardware to experience AI, whether using Apple Intelligence, including Siri AI, or third-party offerings."
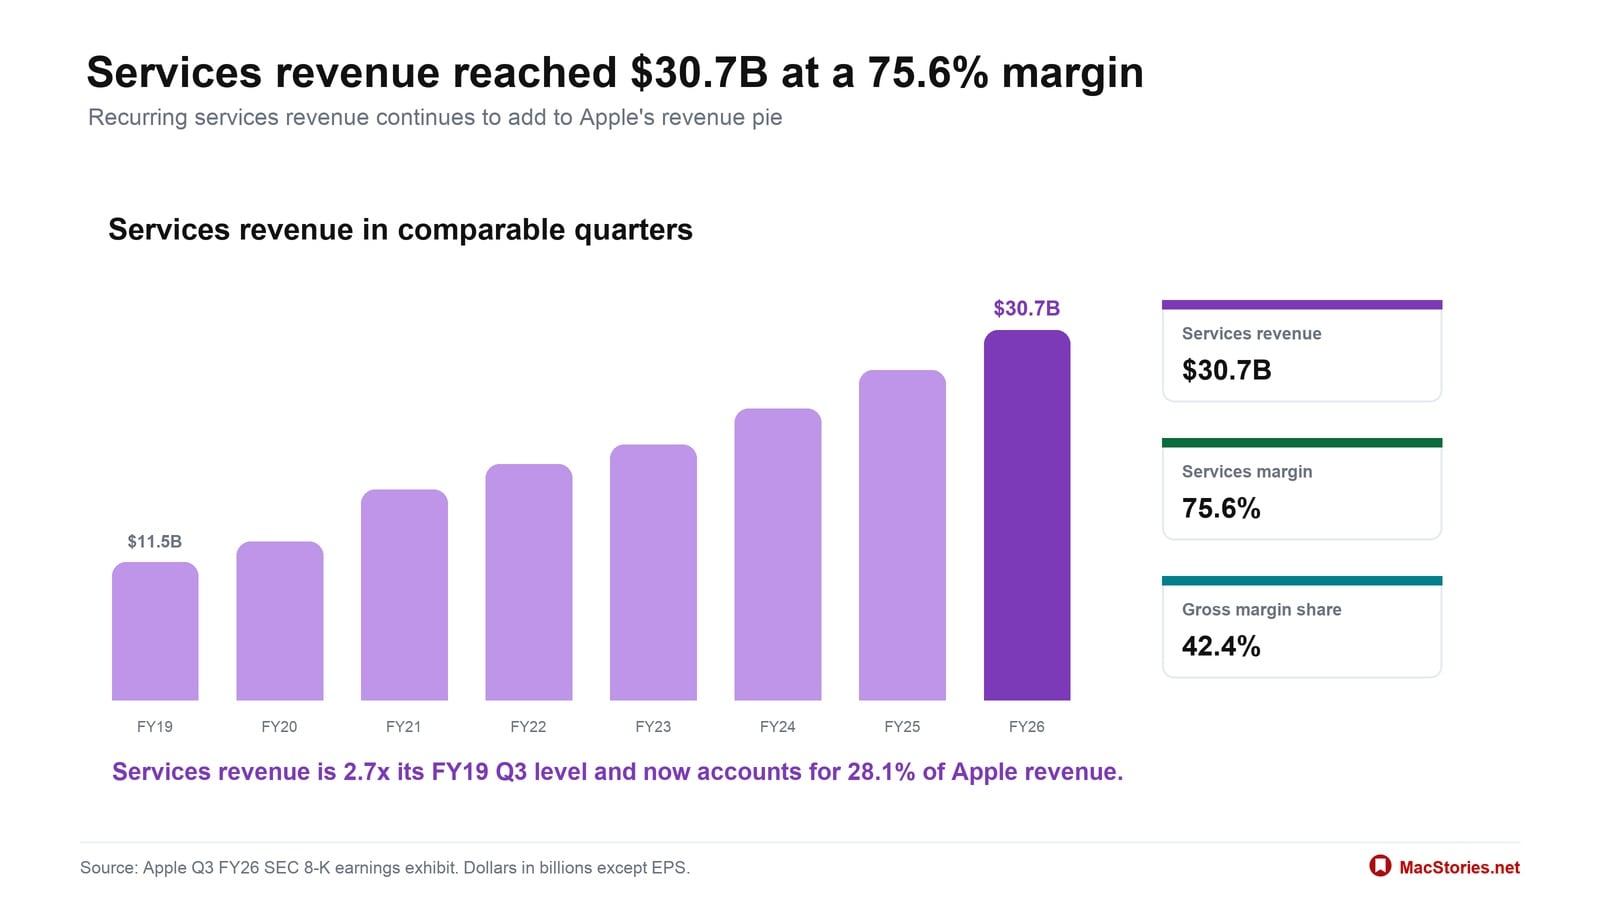
2:12 pm: Services revenue was $30.7 billion, up 12% from a year ago, "despite significant foreign exchange headwinds."
2:13 pm: Ted Lasso returns to
Apple TV next week for its fourth season, and the company just won a Tony Award, and has 89 Emmy Award nominations.
2:14 pm: "We're halfway through an unforgettable year of F1, and Apple TV subscribers have been tuning in all season."
2:14 pm: In Retail, Apple Upgrade was just launched for customers in the US.
2:15 pm: "In honor of Global Accessability Awareness Day, we unveiled new features to help users get more out of the products they use every day."
2:16 pm: "We're doing our part to invest in innovation close to home. Last year we made a $600 billion commitment to the US over four years, and now we've planned to reinvest the tariff refunds we've received into the US." There's a new agreement with Broadcom to design and produce custom silicon components and cutting-edge wireless connectivity technologies. The agreement is expected to exceed $30 billion in US spending.
2:17 pm: Apple is going to make the
Mac mini at the Advanced Manufacturing Center in Houston, and will train employees and suppliers in how to build products.
2:17 pm: "We will remain guided by our north star: building products and services to enable people to do magical things."
2:18 pm: "I couldn't be more excited to watch our phenomenal story of innovation continue to unfold, and I've never been more confident that the best is yet to come."
2:18 pm: Kevan is on now to go into more detail on financials. Revenue of $109.4 billion was up 16% year over year. Product revenue was $78.7 billion, up 18% year over year. Install base reached a new all time high of over 2.5 billion. Services revenue was $30.7 billion, up 12% year over year.
2:19 pm: Company gross margin was 50.1%, up 80bp sequentially, including a benefit of tariff refunds, with an impact of 2%. If you remove this impact, we would have been at the middle of the guidance range. Product margin was 40.1%, up 140 basis points. Tariff refunds had an impact of 2.5%.
2:20 pm: OpEx was $19.1 billion, up 23%, driven by investments in R&D. Net Income was $29.8 billion. $34.4 billion in operating cash flow, setting new June quarter records even when excluding tariff refunds.
2:20 pm: iPhone was $54.3 billion, up 22%. iPhone active install base grew to an all-time high and set a June quarter record for upgraders. iPhone was the top selling model in the US, urban China, the UK, France, Australia and Japan.
2:21 pm: Mac revenue was $10.4 billion, driven by the strength of MacBook Neo and MacBook Pro. Grew in both developed and emerging markets. Customer reception of MacBook Neo "has been incredible." Mac had its best quarter ever for customers new to the Mac and for upgraders.
2:22 pm: iPad revenue was at $6.2 billion, down 6% year over year against a difficult compare. More than half of customers who purchased an iPad were new to the product.
2:22 pm: Wearables, Home and Accessories revenue was $7.9 billion, up 6% year over year. More than half of customers purchasing an Apple Watch were new to the product.
2:23 pm: Services revenue was $30.7 billion, up 12%, despite "significant sequential FX headwinds."
2:23 pm: "We are optimistic about the long-term future of our Services business... we have an incredibly strong foundation for growth opportunities."
2:24 pm: Morgan Stanley has deployed more than 20,000
iPhone 17 devices, as part of a shift from employee-owned to corporate-owned devices for liability and security.
2:25 pm: Pinellas County Schools in Florida is transitioning 25,000 students from Windows devices to MacBook Neo.
2:25 pm: "About half of the MacBook Neo purchases by US education institutions replaced Windows and Chromebook devices."
2:26 pm: Ended the quarter with $147 billion in cash and $84 billion in debt. Returned $33 billion to shareholders, including $4 billion in dividends and $25.8 billion in share repurchases.
2:27 pm: Forward projections assume no changes to global tariff rates and that the global macroeconomic outlook does not get worse. "We also expect our September quarter total company revenue to be impacted by two main factors. First, we expect foreign exchange to be a sequential headwind of about two and a half percentage points to the year-over-year total company growth rate from the June quarter over the September quarter."
2:28 pm: Expect total company revenue to grow 9-11% next quarter, and expect iPhone revenue to be impacted by foreign exchange headwinds and supply constraints. iPhone reported growth rate is expected to be mid-teens year over year. Gross margin should be between 47% and 48%, with approximately 1% benefit related to tariff refunds. OpEx between $19.1 and $19.4 billion.
2:28 pm: Cash dividend of $0.27/share, payable on August 13.
2:29 pm: Tim is taking back over. "I just wanted to take a moment to say 'thank you' to all of you. From our shareholders, particularly our long-term shareholders, who have put their trust in us for so many years, to the analysts who have followed our company so closely."
2:29 pm: "I am beyond excited for John to step into his new role and lead Apple into its next era. He is truly one of the kind, and there is no better person to take the helm of the company."
2:29 pm: "I couldn't be more confident in his leadership, in our executive team, and in the extraordinary people at Apple that are determined to enrich the lives of our users all over the world. We have a bright future ahead, and I truly have never been more optimistic. So thank you all."
2:30 pm: Now we're moving to the Q&A with analysts.
2:32 pm: Q: Tim, best of luck, it's been a pleasure working with you over the years. On the 9-11% growth, that's a deceleration. How much of this is supply constraints vs FX?
A: We expect revenue to grow by 9-11% year over year, impacted by FX to be a sequential headwind of 2.5% to year over year total company growth rate. On supply constraints, we expect that to impact significantly, affecting iPhone, Mac and iPad. Combine those two factors, we get pretty close to the June overall company growth rate.
We did experience supply constraints primarily on the Mac and to a lesser extent to iPhone and iPad, driven by very high levels of demand and less flexibility in the supply chain than normal. The constraints are primarily driven by availability of the advanced nodes that our SOCs are produced on. Looking forward, we continue to expect high levels of demand, but with less flexibility on supply chain, and impact on the supply chain to increase significantly. To affect iPhone, Mac and iPad, we're seeing some very significantly constraints currently with limited flexibility in the supply chain to remedy it.
2:35 pm: Q: Apple has historically done a great job to deliver capability and utilty to customers without really making them pay disproportionately more. There are reports that suggest that you're seeking greater sourcing flexibility for memory. Can you just talk about is this building options really about ensuring that you have supply and it's a way to mitigate memory inflation, or is it more preserving a value proposition?
A: We paid more in March for memory than December quarter, and we paid more in the June quarter than March. We expect this to continue to get worse in September. We had some benefit from carry-in inventory, but we believe this will see decreasing benefit from this over time beyond the September quarter. Second, we are expecting lower costs on certain non-memory components that are in our BOM, and if you look beyond September we see the market pricing for memory continuing to increase which could drive an increasing impact on our business. In terms of sources of supply, primarily the DRAM market has three suppliers. If there were more suppliers, that would be good and it would help us on the supply side and perhaps the pricing side, though the pricing side is unclear. It could help on the supply side. We're evaluating all options.
2:37 pm: Q: On the Apple Upgrade program, do you see it shortening the replacement cycle for iPhone, and having an impact on Mac and iPhone and having an impact because those two haven't had benefits of subsidies?
A: If you look at the program, it makes it easier for customers to get their hands on our latest products with a leasing plan that's right for them. The residual values on Apple products tend to be much higher than residuals on the competition. It's a way to get into a product on an affordable basis, particularly for customers who want to upgrade on some kind of schedule. It is offered in our retail stores, not across all channels, so we'll see what the customer uptake is. The early feedback on it is quite positive, also it's only available in the US right now.
2:39 pm: Q: On Apple Intelligence and
iOS 27, can you talk about learnings from the public beta, will the new Siri AI be a demand driver for the iPhone this holiday, how does Apple intelligence usage in the open beta drive your thinking on compute costs and your ability to recover costs through
iCloud Plus?
A: We are off the charts excited about Siri AI. We released the developer beta immediately after the keynote. Developer feedback, reviewers and so forth have been overwhelmingly positive. Released as a public beta and the continued feedback is really great. I think it's a big idea to have AI based on your personal context and that's integrated across the operating system. It's early going and I don't want to say we have a complete plan for that, we do believe there will be people who want to use it a lot and so we will have some kind of upgrade possibilities on iCloud+ where people can buy up the stack, and we'll see how the pickup for that is. We could not be more excited about where the product is.
2:43 pm: Q: Wanted to ask about supply constraints, what we're struggling with after hours, how much do these supply constraints impact you in December and we did a pretty good job taking that number into the higher single digits, is there any guidance that you can give us there?
A: Let me talk about the constraints a little more, the primary issue is advanced nodes that we run our SOCs on. That's the primary supply constraint now. The root cause of it is not a regular supply issue. It's a demand forecast issue to be candid. Where iPhone and the Mac are both doing remarkably better than we thought they would do, and we had high expectations and it wasn't that our expectations were low. From iPhone's growth being 22% and Mac at 29%, these are extraordinary numbers and the supply chain has less flexibility than normal. We've been pulling supply ahead and at some point there's a limit to that. Now we have a quarter where we'll be scrambling on the supply side eventually.
Combined with foreign exchange impact, that's really what's built into the 9-11 percent growth rate. Beyond December we're not providing any color beyond the September quarter.
2:45 pm: A: This isn't a partner or supplier issue, it's a great issue in some ways, it's an incredibly strong iPhone and Mac product cycle that has yielded demand beyond expectations. In Arizona, we source more than 100 million components this year, so it is part of our $600 billion commitment to the US and we could not be more pleased with how that fab has ramped and is producing for us.
2:46 pm: Q: It is your intention to pursue some agreements to ensure access to supply at pre-agreed prices, when you approach product pricing, are you trying to protect margins or gross profit dollars? What's your thoughts on pricing?
A: We reluctantly raised prices and because we're in a 100-year flood on the memory pricing with exponential increases in memory prices. That was the rationale for it. In terms of our philosophy on dollars or percentages, we look at units revenue and margin and then come to a business judgement as to how to handle that. It's not a mathematical formula that gets us to a specific result or looking at one dimension of that. We look at all three dimensions, thinking about it over the long term instead of a 90-day clock.
2:49 pm: Q: 12% services growth was slightly below guidance, maybe FX played a role, can you help us understand the function factors underlying the deceleration, if that
App Store, some third-party data sources, is that a function of AI reprioritizing time away from the App Store? Just looking at the moving pieces on Services.
A: Let's walk from our 16% to second quarter to 12% in the June quarter, FX was the main driver in the year over year growth rates. Last year we had the theatrical release of F1, we also had some factors that impacted the App Stores, some headwinds in mobile gaming and some change to the business model in certain countries, and in the US a ruling on the link out for transactions. App Store set a June quarter revenue record. Several positive trends, strong double digit growth in a number of sectors. Revenue records in every category. Apple TV viewership set an all time high in the quarter.
Apple Pay saw a record number of users in both developed and emerging markets. Services continue to attract more customers, passing more than 1.5 billion paid subscriptions.
2:50 pm: A: When we step back and look at how we landed, I would say that we roughly met our expectations but saw some more softness on mobile gaming and the App Store. In September, FX will continue to be a headwind, impacting Services more than the whole company. FX will drive a 5% headwind from March to September quarter. We are going to see another 2.5% sequential headwind from June to September.
2:52 pm: Q: As you look at demand, how do you assess whether you're seeing pull-forward of demand from consumer or enterprise or education, and if you're factoring that into your views as we look forward.
A: You're talking about iPhone I presume, we've been running at this 24% growth rate for a while, it's not obvious that what you're asking is true. We've now had to increase prices on iPad and Mac, the price elasticity there it's too early to come to a conclusion of what happens there. It takes a little while for the channels to adjust since there's channel inventory, and takes a while for the consumer to respond so we'll understand that more in the weeks ahead.
2:53 pm: Q: Longer term, thematically, AI proliferates towards the edge, do you see AI opening additional opportunities and do you see other addressable markets evolving from AI over time?
A: These are enormous opportunities for Apple moving forward in AI. I'm so excited for Siri AI, where it is and where it's going. I'm excited about the feedback that we're getting there.
2:55 pm: Q: On Siri AI, do you expect that Siri AI will change the capital intensity despite you having the ability to do so much on the device, you have some requests that go into the back end in first and third-party cloud, is it right to think that the capital intensity will change in the future?
A: We use a hybrid model, so we use some third-party cloud and our own data centers, so there will be a mix but generally speaking, as you know, we have been growing OpEx and spending more on AI in general. Quite a bit more. There are other locations on the P&L besides OpEx that have AI expenditures, we'll see what Siri AI does from the cost side of it, but there's also the ability when people use it a lot for people to move up on an iCloud band as well. The balance of that is a bit uncertain at the moment.
2:56 pm: Q: To John, can you give us a high-level take on the competitive landscape, OpenAI hardware or SpaceX launching a phone that can bypass carriers?
A, from John Ternus: There's so much opportunity for us in this space, and we're very focused on our plans and very excited about it.
2:59 pm: Q: How do you launch Apple Intelligence and Siri AI in the rest of the world?
A: If you look at the EU, we're working closely with the commission. We want to launch everything, everywhere all of the time. We haven't been able to do that in the EU. We're trying to get to offer it there, we are allowed to offer it on the Mac there, it's not covered on the same regulations as the iPhone and iPad. We hope to reach some sort of solution.
If you look at China, last week we received approval to ship the original features of Apple Intelligence, things like cleanup and so-forth. We're working now through the rollout of those and there will be more work required down the road for Siri AI, but we're at the front end of that.
3:01 pm: Q: Not to beat this FX thing to death, but if we look at the gross margin, you delivered 48% in the quarter without tariffs, now guiding to 46.5%, how much of that is FX vs commodity costs etc?
A: On gross margin, we look at the change from 49.3 for March to 48.1 adjusted for June, that 120 basis point change, most of that is the memory cost impact. As Tim outlined earlier, we saw some partial offsets from carryin inventory and some favorable mix, we see the same dynamics as you go from 48.1 in June to the 46.5 midpoint of our range without any tariff refund impact. That 160 bp change, more than that is explained by memory offset by lower costs and favorable mix. FX was a pretty minimal impact versus memory, so the sequential change is really driven by memory.
3:01 pm: The call is now complete. Almost every analyst congratulated Tim on his tenure and wished him well for the future.
This article, "
Apple Reports 3Q 2026 Results: $29.8B Profit on $109.4B Revenue" first appeared on
MacRumors.comDiscuss this article in our forums

 Login